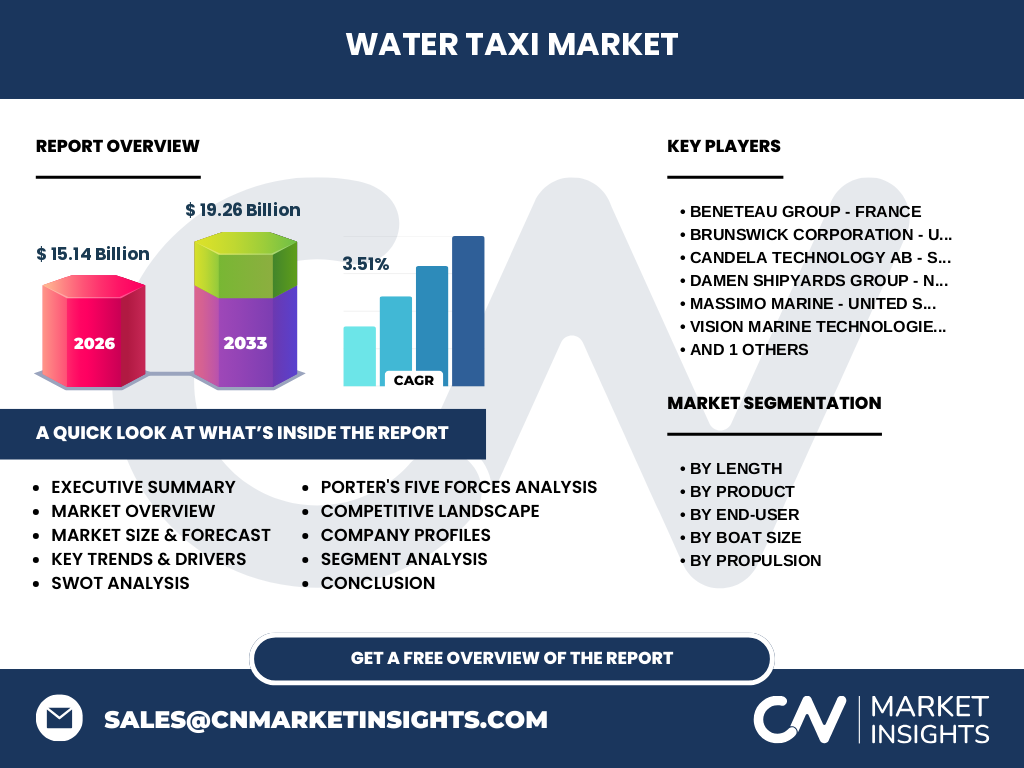
Market overview of the global Water Taxi Market landscape
The Water Taxi Market serves as a critical maritime infrastructure component, facilitating urban mobility and tourism. Our analysis defines this sector by its reliance on high-frequency transit vessels. With a 2026 valuation of 15.14 Billion, the industry bridges the gap between traditional ferry transit and private maritime logistics, proving essential for congested coastal urban centers globally.
What primary catalysts and constraints define the current Water Taxi Market trajectory?
Growth is primarily driven by urbanization and the urgent need for sustainable transit. Conversely, the market faces stiff regulatory headwinds and infrastructure limitations in older ports. While high capital expenditures act as a barrier to entry, the demand for electric propulsion integration offers a unique opportunity for incumbents like Candela Technology AB to capture eco-conscious market share.
Emerging shifts and growth patterns within the industry
A pivot toward decarbonization is the most defining pattern. We observe a rapid shift from traditional diesel engines to high-efficiency electric powertrains. This movement is not merely aesthetic; it is a strategic response to stricter carbon emission mandates in European and North American waterways, fundamentally altering the Water Taxi Market supply chain dynamics.
How did the COVID-19 pandemic influence the long-term recovery of the Water Taxi Market?
The pandemic caused an immediate, sharp contraction in leisure-based water taxi usage. However, the recovery trajectory has been robust as operators shifted focus toward essential public transit functions. By 2026, the sector reached 15.14 Billion, proving that water-based transit resilience is tied to its dual utility in both tourism and municipal transport.
Competitive dynamics and market concentration among top players
The landscape is moderately fragmented, featuring a mix of established legacy shipbuilders like Damen Shipyards Group and agile innovators like X Shore. Market concentration is evolving as larger entities acquire niche electric-vessel firms to modernize their fleets. Strategic positioning now hinges on technological differentiation rather than sheer manufacturing scale.
Executive Summary: High-level synthesis of Water Taxi Market insights
Our research indicates a stable CAGR of 3.51% through the forecast period. The Water Taxi Market is transitioning from a traditional tourism-reliant industry to a sophisticated, tech-enabled public transport solution. With a projected 19.26 Billion market size by 2033, the industry demonstrates significant long-term investment viability, provided firms adapt to electric propulsion requirements.
Forecasted trajectory for the Water Taxi Market from 2027 to 2033
Based on our modeling, the industry will scale from its current base to reach 19.26 Billion by 2033. This growth reflects a 3.51% CAGR. We anticipate that increased government funding for water-borne public transport, particularly in high-density regions, will act as the primary engine sustaining this upward momentum through the end of the next decade.
Segmentation breakdown: Understanding the building blocks of the market
Segmentation is categorized by length (Above/Upto 10m), product type (Ferries/Yachts), end-user (Tourism/Public Transport), and propulsion (Diesel/Electric). Public transport and electric-propulsion segments are currently gaining disproportionate growth traction. This structural breakdown helps identify high-value pockets, such as compact, electric-powered vessels under 30 ft that serve the urban transit segment effectively.
Regional performance and geographic distribution analysis
Regional performance is uneven, with coastal European and Asian urban centers leading in adoption. While the North American market benefits from the presence of key players like Brunswick Corporation, Europe currently holds the lead in electrification standards. Our analysis shows that regions with high congestion index scores exhibit the fastest uptake in water taxi investment.
Detailed examination of key regional markets
Europe remains the epicenter for sustainable water transport, largely driven by strict environmental regulations. North America, however, is a massive market for leisure-based yacht taxis, with players like Massimo Marine leveraging high disposable income. Conversely, the APAC region is seeing massive public sector investment, which is essential for scaling the Water Taxi Market infrastructure in emerging megacities.
Strategic positioning of major industry participants
Companies are segmenting their strategic focus: Beneteau Group excels in leisure-focused yacht design, while Vision Marine Technologies is positioning itself as a leader in electric powertrain technology. These players are not just competing on price; they are competing on integrated systems architecture, ensuring their fleets meet the complex, high-availability demands of modern municipal water taxi operators.
Porter's Five Forces assessment for the Water Taxi Market
The industry faces moderate threat of new entrants, constrained by high maritime safety certification hurdles. Supplier power is significant, especially for advanced battery systems. Competitive rivalry is intense among firms vying for municipal tenders. Overall, the forces suggest a shift toward consolidation as smaller, non-electric players struggle to meet updated performance standards.
SWOT Analysis: Strengths, Weaknesses, Opportunities, and Threats
The industry's strength lies in its unique ability to bypass land-based congestion. A weakness is the high maintenance cost of marine vessels. Opportunities abound in electric transition and smart-port integration. The primary threat remains unpredictable regulatory shifts regarding noise pollution and maritime carbon emissions, which could impact the profitability of diesel-dominant fleet operators.
Value chain analysis from raw materials to end-users
The value chain originates with raw material providers for marine-grade hulls and specialized battery tech. It flows through manufacturers like Damen Shipyards Group, into operation and maintenance, and finally reaches the end-user. Value capture is shifting toward the technology-services interface, where software-based fleet management and efficient energy storage are creating more value than the physical hull construction itself.
Strategic investment insights and high-potential focus areas
Investors should prioritize electric propulsion companies and firms focused on autonomous docking technologies. Given the 3.51% CAGR, the most lucrative opportunities lie in public transport infrastructure upgrades that utilize compact, zero-emission vessels. Targeting segments that facilitate daily urban commuting rather than luxury leisure yields more stable, long-term returns in the current market environment.
Conclusion and critical takeaways for stakeholders
The Water Taxi Market is at an inflection point. With a projected 19.26 Billion valuation by 2033, the shift toward sustainable urban water mobility is irreversible. Success requires a dual focus on technological innovation in electric propulsion and deep alignment with municipal public transit planning to secure long-term, predictable demand and scalable market reach.
Research methodology and analytical framework
Our analysis utilizes a triangulated research framework: combining proprietary ship-registration data, primary executive interviews, and financial synthesis. We applied a bottom-up sizing approach for segments like electric propulsion to ensure the 3.51% CAGR estimation reflects realistic adoption curves based on current regional environmental policy implementation and municipal transit budgets.
Report scope: Parameters and coverage limitations
This Water Taxi Market research covers commercial transport vessels utilized for taxi operations. It encompasses global regional markets and product categories ranging from yachts to public ferries. Limitations include the exclusion of private recreational boat sales, as the focus is strictly on revenue-generating commercial transit. The report provides a clear, quantitative snapshot through the 2033 forecast period.
Recent developments and strategic industry moves
Recent activity is dominated by partnerships between shipbuilders and battery tech innovators. Vision Marine Technologies and X Shore continue to push the envelope in performance testing, setting new benchmarks for electric vessel efficiency. These strategic moves highlight a broader industry trend where co-development agreements are becoming the primary mechanism for scaling capacity in an increasingly high-tech maritime sector.