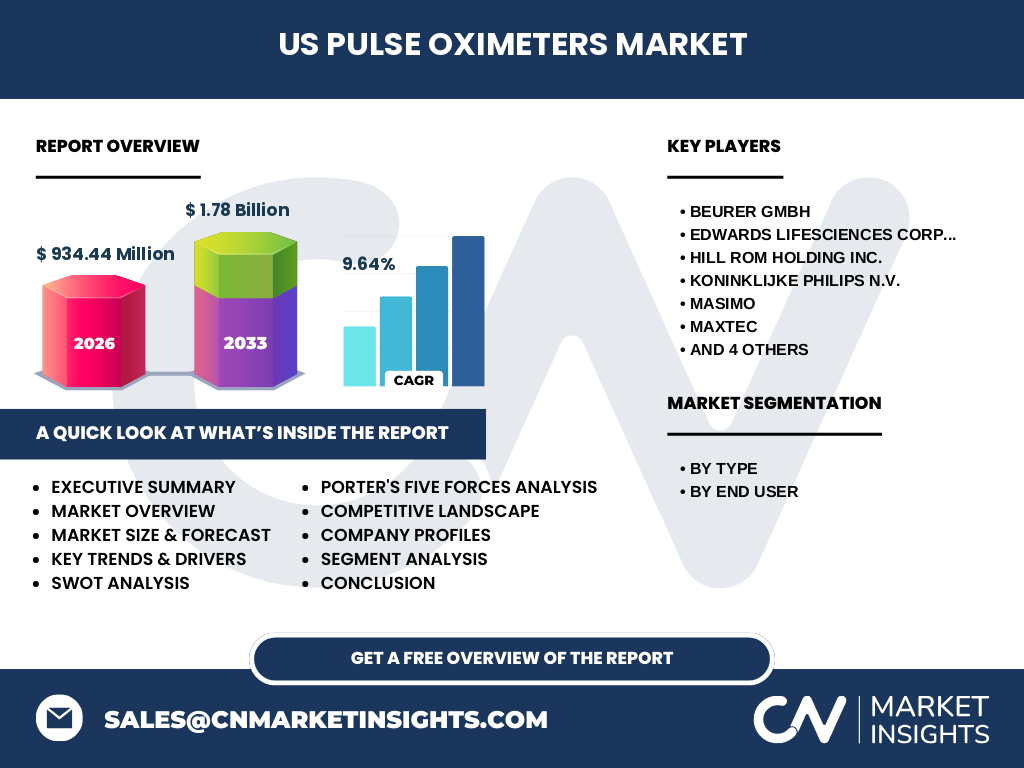
Market overview of the US Pulse Oximeters industry
The US Pulse Oximeters Market encompasses critical non-invasive physiological monitoring technologies essential for measuring arterial oxygen saturation. Valued at 934.44 Million in 2026, the industry serves as a cornerstone for respiratory care. It is heavily regulated by the FDA, ensuring devices meet stringent clinical accuracy standards for both diagnostic settings in hospitals and home-based patient monitoring.
Structural Growth Drivers and Market Constraints
Primary growth is driven by the rising prevalence of chronic respiratory diseases and the aging demographic in the US. However, manufacturers face significant logistical hurdles regarding global supply chain reliability for optoelectronic components. While opportunities exist in telehealth integration, rigorous FDA 510(k) clearance requirements remain a formidable barrier for new entrants looking to gain market share in the clinical pulse oximetry landscape.
Emerging trends shaping the US Pulse Oximeters Market
The industry is shifting toward connected care ecosystems, where data flows directly from wrist-worn pulse oximeters to electronic health records. There is a distinct push for medical-grade accuracy in consumer-focused wearables. Innovation is currently focused on signal processing algorithms that reduce motion artifacts, a critical technical hurdle that companies like Masimo and Nonin are aggressively tackling to ensure reliable patient monitoring in ambulatory settings.
COVID-19 impact analysis and recovery trajectory
The pandemic served as a catalytic force, causing a massive surge in demand for pulse oximeters as primary tools for early hypoxemia detection. Post-2026, the market has transitioned into a sustainability phase. The recovery trajectory is marked by a shift toward more sophisticated, long-term monitoring solutions, moving away from the initial panic-buying of basic devices toward high-precision instruments favored by healthcare systems to manage chronic post-COVID conditions.
Competitive benchmarking of the US pulse oximetry leaders
The market is dominated by tier-one incumbents including Medtronic, Koninklijke Philips N.V., and Masimo. Competitive advantage is built on proprietary sensor technologies and deep integration within hospital IT networks. These leaders maintain dominance through heavy investment in R&D and by navigating the complex FDA recall and quality compliance landscapes, leaving smaller, niche players to compete primarily on price-sensitive segments like basic fingertip devices.
Executive summary: Synthesis of the US Pulse Oximeters Market
Our research indicates a robust trajectory for the US Pulse Oximeters Market, projected to reach 1.78 Billion by 2033. This growth, reflecting a steady 9.64% CAGR, is anchored by the dual influence of clinical demand for acute care monitoring and the expanding footprint of remote patient management. Strategic stakeholders must prioritize interoperability and regulatory compliance to capitalize on this expanding 1.78 Billion valuation.
US Pulse Oximeters Market forecast: 2027-2033
We project the market will climb from its 2026 base to a total valuation of 1.78 Billion by 2033. This 9.64% CAGR is sustained by sustained investment in clinical infrastructure. The forecasted expansion assumes continued adoption of advanced diagnostic tools in outpatient clinics, supported by favorable reimbursement policies that prioritize high-precision monitoring over cheaper, less accurate alternatives currently flooding the retail sector.
Segmentation analysis by type and end-user
The market is segmented by product into fingertip, handheld, wrist-worn, and pediatric pulse oximeters. Fingertip and handheld units dominate the clinical hospital segment, while wrist-worn variants are seeing rapid adoption in home-based clinics. Our analysis highlights that hospitals remain the primary revenue drivers, though clinics are projected to experience faster relative growth as medical care decentralizes to lower-cost settings.
Regional performance analysis within the United States
Regional performance mirrors the concentration of Tier-1 hospital networks. Coastal hubs benefit from high investment in technological infrastructure, whereas the Midwest and South are seeing expansion driven by telehealth service growth. Logistic hubs in major ports allow for the efficient importation of medical-grade sensors, which are then integrated into final systems by companies like Smiths Medical and Vyaire Medical to serve localized demand centers across the nation.
In-depth review of key regional market dynamics
Regional demand is heavily influenced by the Medicare/Medicaid penetration rates and regional public health mandates. States with a high percentage of elderly populations show disproportionately higher uptake of pediatric and home-use pulse oximetry. Our analysis identifies that local regulatory environments and health system capacity in states like California and Massachusetts are critical indicators for predicting regional adoption speeds of high-end diagnostic hardware.
Strategic positioning of leading companies
Koninklijke Philips N.V. and Medtronic leverage extensive global supply chains to dominate large-scale hospital procurements. Conversely, Nonin focuses on clinical-grade durability, positioning itself as a reliable partner for intensive care environments. Meanwhile, Beurer GmbH and Maxtec strategically target the home-care and specialized clinical sectors, utilizing high-quality manufacturing to differentiate their portfolios from low-cost, disposable alternatives that lack long-term reliability.
Porter's Five Forces analysis of the market
The threat of new entrants is mitigated by stringent FDA oversight and high intellectual property barriers. However, buyer power remains high as major health systems consolidate their purchasing. The intensity of competitive rivalry is significant among established players like Edwards Lifesciences and Hill Rom, who compete through innovation in signal integrity and interoperable monitoring systems.
SWOT analysis of the US Pulse Oximeters landscape
Strengths: High clinical demand and established reimbursement codes. Weaknesses: Dependence on complex global electronics supply chains. Opportunities: Integration of AI-driven predictive analytics into real-time monitoring. Threats: Increasing influx of unregulated consumer-grade devices that could dilute professional standards. Strategic success relies on shielding the brand from the commoditization of the low-end segment through a focus on medical-grade precision.
Value chain analysis for industry stakeholders
The value flow begins with the sourcing of semiconductors and photodiodes, followed by specialized sensor assembly. Value is added through sophisticated firmware development that filters physiological data. Finished devices move through medical distributors to hospitals and clinics. Companies like Vyaire Medical capture significant margin by ensuring their devices integrate seamlessly with electronic medical record (EMR) systems, a critical final touchpoint in the value chain.
Investment insights and high-potential areas
Investors should target companies that demonstrate proprietary sensor accuracy and cloud-native analytics capabilities. With a projected 1.78 Billion valuation by 2033, the market favors mid-market manufacturers capable of scaling in the clinic segment. High-potential opportunities lie in wireless connectivity and long-term monitoring technologies, as hospitals prioritize cost-reduction through early intervention and remote patient monitoring to prevent costly readmissions.
Conclusion and key market takeaways
The US Pulse Oximeters Market is a stable, high-growth environment characterized by a 9.64% CAGR. Success requires a commitment to clinical validity over mass-market volume. With the industry reaching 1.78 Billion by 2033, the shift toward interoperable digital health will define the next generation of competitive leadership, rewarding firms that balance regulatory excellence with consumer-accessible technological interfaces.
Research methodology: How our estimates were triangulated
Our methodology utilizes triangulation between trade registry data, primary interviews with procurement heads, and macroeconomic indicators. We cross-reference FDA device registration volumes with import data from major US customs ports. This rigorous process ensures that the 934.44 Million 2026 base estimate and subsequent 1.78 Billion forecast reflect accurate market reality, accounting for both clinical volume shifts and price fluctuations in the hardware components.
Scope of the report: Parameters and limitations
This analysis covers the US Pulse Oximeters Market within the 2026-2033 window. The scope is limited to professional-grade clinical and high-end home-use pulse oximeters. It excludes low-cost, non-FDA-cleared recreational trackers. The report assumes consistent regulatory policy enforcement by the FDA and excludes potential macro-disruptions like total global trade isolation, which could impact the semiconductor supply chain essential for these devices.
Recent developments and strategic moves in the market
Recent activity highlights a focus on partnerships between device manufacturers and telehealth software providers. Major players like Masimo and Medtronic are actively launching updated software suites to enhance data interoperability. These strategic moves are specifically designed to address the growing demand for clinical-grade remote patient monitoring, ensuring these firms maintain their premium positioning against the backdrop of an expanding, yet increasingly competitive, 1.78 Billion market.