Overview of the Europe Industrial Machinery Market
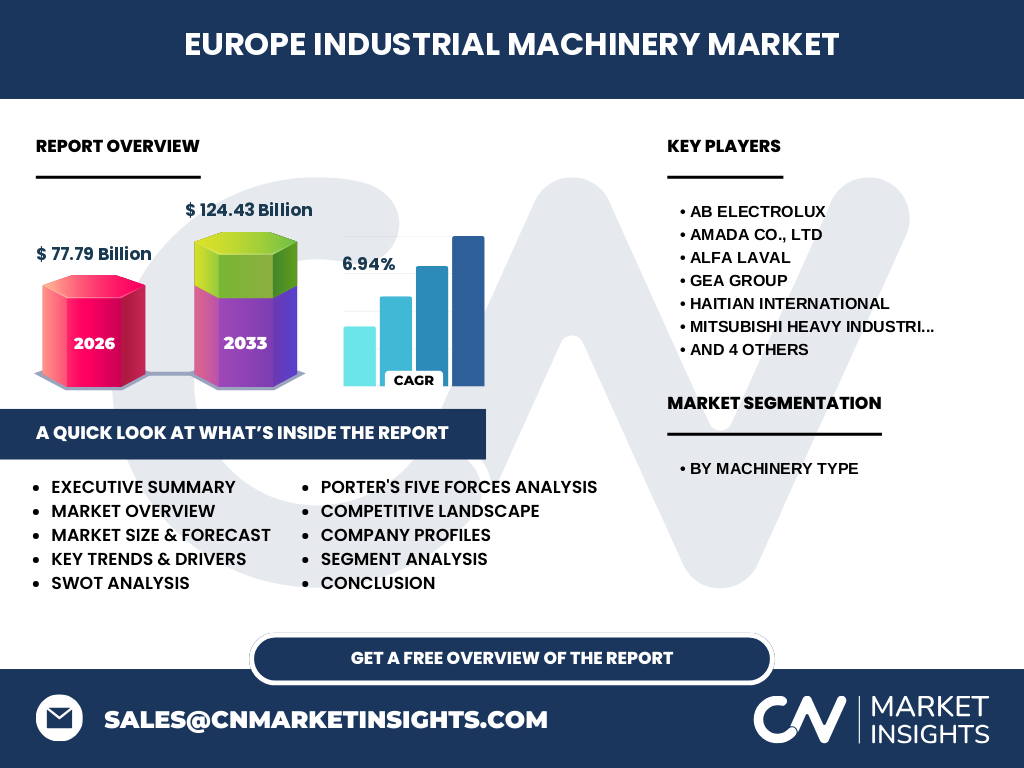
The Europe Industrial Machinery Market serves as the backbone of the regional manufacturing ecosystem. Valued at 77.79 Billion in 2026, this sector encompasses critical equipment for packaging, food processing, and metal forming. It is essential for maintaining EU industrial competitiveness, particularly as factories transition toward high-precision automation and energy-efficient mechanical systems to meet strict environmental standards set by the European Commission.
Structural Growth Drivers and Market Constraints
Our analysis reveals a CAGR of 6.94% through 2033, fueled by rapid automation in logistics and food safety mandates. However, the industry faces significant supply chain volatility regarding steel and aluminum prices. Furthermore, navigating complex REACH regulations and labor shortages in the precision engineering sector acts as a constraint, forcing OEMs to prioritize intelligent, low-maintenance machinery to offset rising operational overheads.
Emerging trends in European industrial automation
The shift toward Industry 4.0 is defining the current landscape. We observe a pivot toward predictive maintenance and IoT-integrated robotics. Companies like GEA Group are leading the charge in sustainable food processing equipment, focusing on reducing carbon footprints during thermal processing. These trends indicate that market leaders are moving away from traditional mechanical output toward data-driven, software-enabled machinery performance.
How did COVID-19 alter the trajectory of the market?
The pandemic acted as a catalyst for digitalization. While initial lockdowns halted production, the recovery trajectory post-2022 highlighted the need for autonomous packaging solutions. Industry players like Syntegon Technology GmbH adapted by scaling remote commissioning services, ensuring that machinery uptime remained high even when on-site technician access was restricted at major logistical hubs like the Port of Rotterdam or Hamburg.
Competitive Benchmarking and Strategic Positioning
The market shows moderate concentration with a focus on specialized engineering. Giants like Alfa Laval and Schuler Group maintain dominance through high-barrier-to-entry innovations in heat transfer and metal forming. Our research indicates that these firms leverage vertical integration to secure proprietary components, effectively distancing themselves from smaller, regional manufacturers that struggle with the increasing capital intensity of high-tech machinery development.
Executive Summary of the Europe Industrial Machinery Market
The market is set for sustained growth, reaching a projected 124.43 Billion by 2033. Our synthesis confirms that while traditional machinery remains vital, the value-add is shifting toward automation and sustainability. Investors should focus on companies demonstrating high R&D intensity, as these players are best positioned to navigate the 6.94% CAGR growth curve and capture share in a post-industrial modernization landscape.
What is the market forecast for 2027 to 2033?
The Europe Industrial Machinery Market is poised for significant expansion, with forecasts indicating a value of 124.43 Billion by 2033. This steady climb, underpinned by a CAGR of 6.94%, reflects the heavy investment by European firms in modernizing production lines to counter high labor costs and align with EU Green Deal decarbonization initiatives, ensuring long-term operational viability across diverse manufacturing sectors.
Segmentation Analysis of the European Industrial Machinery Sector
The sector is categorized into five key segments: Packaging Machinery, Food Processing Equipment, Plastics Processing Machinery, Metal Forming Machine Tools, and Woodworking Machinery. Each segment serves a unique role; for instance, metal forming is critical for the automotive sector, while packaging and food processing equipment remain stable due to the non-cyclical nature of FMCG supply chains in Europe.
Regional distribution and performance insights
Geographically, the DACH region (Germany, Austria, Switzerland) remains the powerhouse, hosting high-density precision manufacturing clusters. However, we are tracking increased growth in Central and Eastern Europe, as nearshoring activities drive demand for metal forming and plastics processing capacity. Logistics corridors near Antwerp and Genoa are central to distributing these high-value capital goods to peripheral European markets.
In-depth regional review: The Southern Europe dynamic
Southern Europe, particularly Italy and Spain, shows resilient performance in packaging and food processing equipment. Regional manufacturers excel in niche applications, often supplying specialized machinery to global exports. Our analysis suggests that these regions are effectively capitalizing on local clusters, providing a vital counterbalance to the heavy machinery focus found in Northern Europe’s industrial heartlands, while navigating specific regional regulatory and energy frameworks.
Strategic positioning of leading companies
Market participants like AB Electrolux and Haitian International employ distinct strategies. While Electrolux focuses on end-to-end efficiency for its internal production, Haitian International leverages economies of scale in plastics machinery to capture mass-market volume. Sumitomo Heavy Industries, Ltd. and Mitsubishi Heavy Industries, Ltd. utilize their global technical prowess to maintain dominance in high-precision heavy metal forming sectors throughout European industrial corridors.
Porter's Five Forces Analysis
The threat of substitutes is low due to the specialized nature of industrial equipment. However, buyer power is rising as customers demand integrated, smart machinery. Competitive rivalry is intense, with firms like The Adelphi Group of Companies competing on precision and service. Barriers to entry remain high, dictated by stringent European safety certifications and the substantial R&D required to compete at a global standard.
SWOT Analysis of the Industrial Machinery landscape
Strengths: Deep technical expertise and established brand equity. Weaknesses: High susceptibility to fluctuating raw material prices (steel/electronics). Opportunities: Integration of AI and remote diagnostics to drive recurring revenue. Threats: Increasing competition from low-cost imports and stringent EU regulatory compliance costs. Our research emphasizes that overcoming the "weakness" of supply chain dependency through localized sourcing is the primary path to sustaining competitive advantage.
Value chain analysis: From raw materials to end-users
The value chain starts with raw material suppliers of specialty alloys and rare earth magnets, moving to OEMs like Amada Co., Ltd. for machine fabrication. The flow continues through specialized integrators providing software and automation layers, ultimately reaching end-users in automotive, food, and consumer goods. Success at every step requires strict adherence to European quality and safety standards for final industrial deployment.
Investment insights for stakeholders
We recommend focusing on firms investing in circular economy machinery—equipment capable of processing recycled plastics and composite materials. With a CAGR of 6.94%, the sector provides a stable growth vehicle. High-potential areas include smart-factory sensor technology and modular machine design, which allow manufacturers to adapt quickly to shifting consumer demand without massive capital reinvestment, offering superior ROI in a volatile market.
Conclusion and key takeaways for the sector
The Europe Industrial Machinery Market is on an irreversible path toward digitization and sustainability. Valued at 124.43 Billion by 2033, the market rewards innovation. Stakeholders must pivot from selling standalone iron-and-steel machines to offering integrated digital ecosystems. Success hinges on mastering energy efficiency and automation, ensuring the continent remains the global leader in industrial precision and advanced manufacturing capability.
Research methodology and data triangulation
Our estimates are triangulated using a multi-layered approach: primary stakeholder interviews with C-suite executives in the packaging and metal-forming industries, combined with trade registry data from EU commerce bodies. We cross-reference these with macroeconomic indicators and secondary import/export reports from major regional hubs. This proprietary methodology ensures our 77.79 Billion 2026 valuation reflects true market activity rather than mere extrapolation.
Scope and limitations of the report
This analysis covers the entire European territory, focusing on mechanical equipment across the five major segments identified. We exclude small-scale repair services to focus on new capital expenditure on industrial machinery. While the report provides high-level regional insights, it focuses primarily on the 2027–2033 forecast period, acknowledging that geopolitical shifts may influence supply chain logistics beyond the current baseline data.
Recent developments and strategic moves in the market
Recent activity is marked by strategic partnerships aimed at green manufacturing. We note major announcements from GEA Group regarding new hydrogen-powered heating systems for food processing. Additionally, Schuler Group has accelerated the launch of digital twin platforms for metal forming, significantly reducing downtime. These developments confirm that the market is rapidly decarbonizing its operational footprint to align with the latest EU environmental directives.