Executive Overview of the Europe Machine Condition Monitoring Market
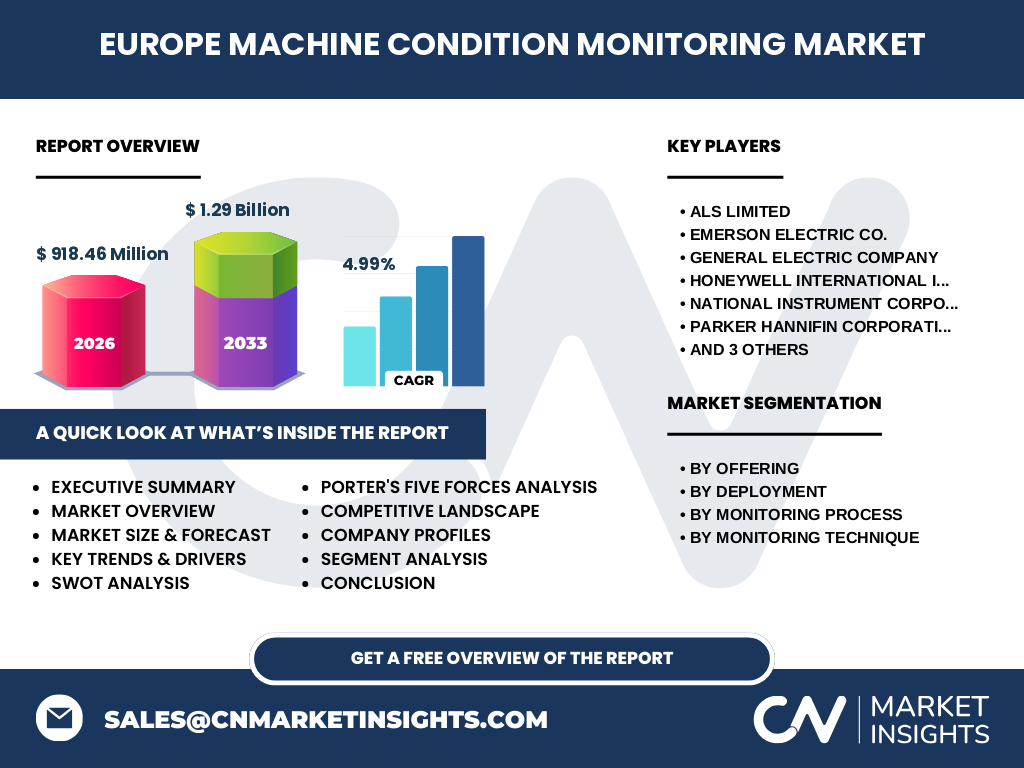
The Europe Machine Condition Monitoring Market represents a critical industrial pillar, valued at 918.46 Million in 2026. Our research indicates a robust trajectory toward 1.29 Billion by 2033, reflecting a CAGR of 4.99%. This growth is underpinned by the essential transition toward Industry 4.0, where predictive maintenance replaces reactive repairs to safeguard operational uptime across Europe's dense manufacturing landscape and vital energy infrastructure.
Structural Growth Drivers and Market Constraints
Growth is primarily propelled by predictive maintenance mandates and the urgent need to optimize asset life cycles in energy-intensive sectors. However, the market faces logistical hurdles such as strict GDPR compliance regarding data privacy and high initial integration costs for legacy industrial sites. Despite these challenges, the demand for hardware and software integration remains a powerful catalyst for long-term investment in regional facilities.
Emerging Industry Trends and Pattern Shifts
The market is witnessing a profound shift toward Cloud-based condition monitoring, enabling real-time remote diagnostics. This trend is complemented by the integration of AI-driven vibration analysis and thermography. Companies like SKF and Schaeffler Technologies AG & Co. KG are leading these technological pivots, moving away from legacy portable systems toward comprehensive, interconnected digital ecosystems that maximize machinery longevity and reduce costly unplanned downtime.
How did the COVID-19 pandemic redefine the European market?
The pandemic served as a critical inflection point, accelerating digital adoption as travel restrictions limited on-site technician access. While initial supply chain disruptions caused short-term volatility, the recovery phase demonstrated the resilience of automated monitoring. The industry shifted its strategy, prioritizing remote cloud diagnostics and mobile monitoring tools to ensure operational continuity despite localized lockdowns and restricted mobility across major EU hubs.
Competitive Benchmarking and Market Dynamics
The competitive landscape is characterized by high market concentration among established players like Emerson Electric Co., General Electric Company, and Honeywell International Inc. These incumbents leverage immense R&D budgets to maintain dominance. Meanwhile, firms like Rockwell Automation Inc. focus on software agility to differentiate their service offerings. The strategic focus is shifting from simple hardware sales to comprehensive, value-added managed services that integrate seamlessly with existing PLC environments.
Market Forecast: The path to 2033
Projected to reach 1.29 Billion by 2033, the market is poised for steady expansion. Our analysis suggests that the transition to Industry 4.0 will create sustained demand through 2033. Investors should note that the online condition monitoring segment will likely outperform traditional portable methods, as firms prioritize automated data streams to satisfy stringent regulatory requirements and maximize overall equipment effectiveness (OEE) in complex industrial environments.
Detailed Segmentation Analysis
The market is segmented by offering (hardware and software), deployment (on-premise and cloud), and monitoring process (online vs. portable). Among techniques, Vibration Monitoring and Thermography maintain the largest revenue shares. Oil analysis and ultrasound emission remain critical for specialized maintenance in harsh, high-friction environments, while motor current analysis is gaining traction due to the widespread implementation of smart, variable-frequency drives across European industrial sectors.
Regional Market Performance and Geographic Distribution
Germany, France, and Italy represent the core pillars of the European market, driven by intense automotive and heavy-machinery production. German industrial hubs show the highest adoption rates of integrated software solutions. In contrast, emerging markets in Eastern Europe are seeing increased deployment of portable monitoring devices as they modernize manufacturing plants. This geographic disparity dictates local sales strategies for leaders like Parker Hannifin Corporation and National Instrument Corporation.
Strategic Positioning of Leading Entities
Leading companies like ALS Limited focus on specialized oil analysis, while Schaeffler Technologies AG & Co. KG provides deep mechanical expertise integrated with advanced digital sensing. SKF dominates through an extensive global service network that translates hardware data into actionable operational insights. Our research demonstrates that these players do not merely sell components; they act as strategic partners in reducing the high costs associated with unexpected machine failure in complex production cycles.
Porter’s Five Forces: Competitive Intensity
Industry rivalry is intense, defined by rapid innovation and high switching costs. The bargaining power of suppliers is moderate, as firms like National Instrument Corporation command high precision standards. The threat of substitutes is low, given the essential nature of condition monitoring for modern industrial safety compliance. Our analysis highlights that new entrants face significant barriers due to the established digital security requirements and proprietary software ecosystem dependencies.
SWOT Analysis of the European Sector
The market's strength lies in its advanced technical maturity. However, a weakness remains the high cost of legacy infrastructure upgrades. Opportunities abound in the integration of AI and 5G for real-time monitoring, while the primary threat remains potential data security vulnerabilities. Strategic success in this market requires balancing rapid technological adoption with the rigorous data privacy protocols mandated by EU oversight bodies.
Value Chain and Industry Flow
The value chain begins with high-end component manufacturing (sensors and transducers), flowing through software developers who build the analytical platforms, and concluding with end-users in automotive, power generation, and chemical processing. Companies such as Parker Hannifin Corporation facilitate this flow by ensuring that hardware is optimized for software integration. The value-flow is increasingly skewed toward data-driven maintenance services rather than static hardware sales.
Strategic Investment Insights
Investors should prioritize companies emphasizing Cloud-based predictive software over traditional on-premise solutions. Our research indicates that high-growth potential lies in the online condition monitoring segment, particularly for companies capable of integrating vibration analysis with motor current analysis. Companies that can bridge the gap between legacy machinery and modern digital dashboards are currently the most attractive targets for high-return, long-term capital allocation in the European industrial space.
Research Methodology and Baseline Triangulation
Our findings are derived from a multi-layered triangulation process. We combined proprietary trade registry data, annual reports from major participants like Rockwell Automation Inc., and primary interviews with industry stakeholders across key ports and industrial hubs. By cross-referencing these inputs with macroeconomic indicators—such as regional manufacturing output and R&D expenditure—we established a baseline that reflects the precise revenue dynamics of the market, ensuring accuracy within the 2026-2033 projection period.
Scope of the Market Report
This report covers the comprehensive Europe Machine Condition Monitoring Market, focusing on segments including hardware, software, and various monitoring techniques. It excludes peripheral residential safety systems to maintain a B2B industrial focus. Geographic scope includes the EU-27 plus the UK, with specific analysis on localized logistical hurdles and regulatory compliance frameworks that directly influence the adoption of predictive maintenance technologies by major European manufacturing and energy companies.
Recent Developments and Market Announcements
Recent activity is marked by strategic M&A and cloud-integration partnerships. Major players are increasingly announcing collaborative initiatives to align with European Green Deal requirements, focusing on energy efficiency through monitoring. Recent product launches from SKF and Emerson Electric Co. showcase a shift toward edge computing, allowing for faster localized data processing. These developments confirm that the market is rapidly moving toward decentralized, smarter monitoring systems to maintain competitive parity.