Market Overview and Industry Significance of Colorectal Cancer Diagnostics
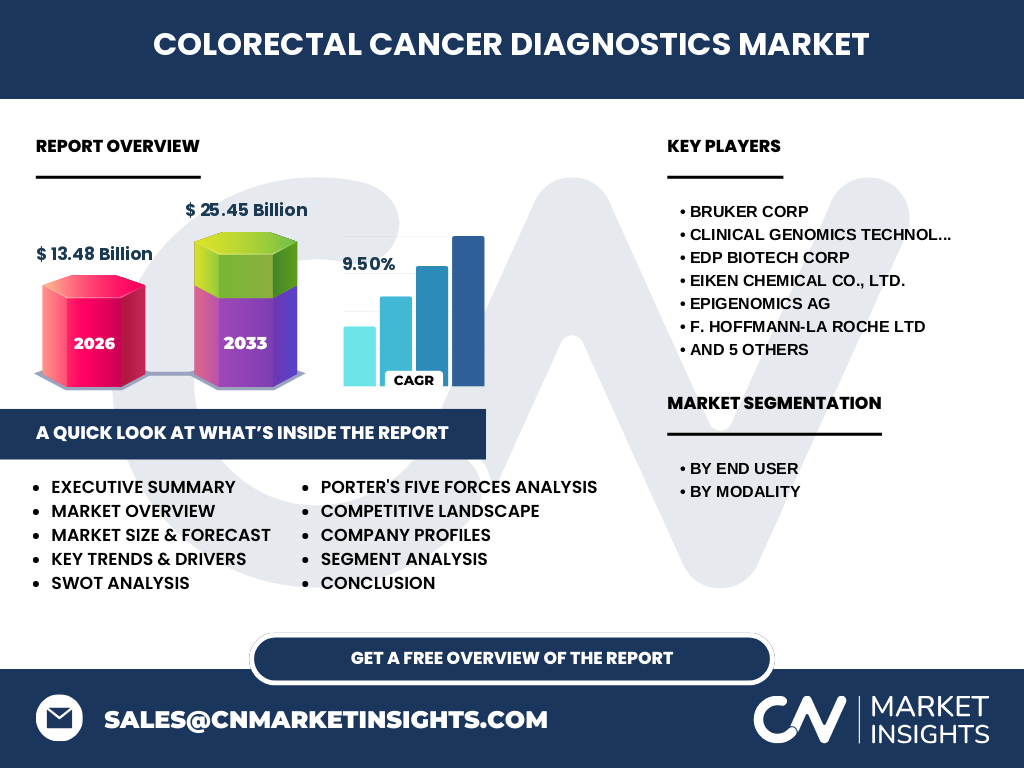
The Colorectal Cancer Diagnostics Market represents a critical pillar in global oncology, valued at 13.48 Billion in 2026. It encompasses advanced molecular screening and imaging modalities essential for early detection. As regulatory bodies like the FDA and EMA tighten screening guidelines, the market serves as the frontline defense in reducing mortality, positioning itself as a vital component of the broader diagnostics and preventative healthcare infrastructure.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by an aging global population and rising awareness of non-invasive screening. However, the market faces logistical hurdles, particularly in the supply chain of high-purity reagents and diagnostic imaging hardware. While Epigenomics AG and other innovators capitalize on early detection trends, reimbursement complexities and strict regional regulatory compliance remain significant constraints that moderate the rapid scaling of advanced molecular diagnostic adoption.
Emerging Trends and Strategic Patterns
The shift toward liquid biopsy and AI-integrated diagnostics defines the current innovation trajectory. We observe a trend where Illumina Inc and other genomics leaders prioritize high-throughput sequencing. This evolution moves the industry away from traditional invasive colonoscopies, significantly lowering patient barriers to entry and increasing diagnostic uptake in developed markets where personalized medicine is becoming the standard of care.
COVID-19 Impact and Recovery Trajectory
The pandemic caused a temporary stagnation in routine screening volumes, as hospitals redirected resources toward urgent care. However, the market demonstrated resilience through a rapid pivot toward at-home stool-based tests. This recovery phase has permanently altered patient behavior, favoring decentralized testing models that allow diagnostic laboratories to maintain continuity even during localized lockdowns or disruptions in clinical infrastructure.
Competitive Landscape and Strategic Dynamics
The landscape is dominated by a mix of specialized tech firms and diversified conglomerates. Companies like F. Hoffmann-La Roche Ltd and Siemens Healthineers AG leverage expansive distribution networks, while players like Clinical Genomics Technologies Pty Ltd focus on niche molecular assays. Market concentration remains high, with strategic M&A activity serving as the primary vehicle for larger entities to acquire proprietary diagnostic intellectual property.
Executive Summary of the Colorectal Cancer Diagnostics Market
Our analysis reveals a robust compound annual growth rate of 9.50% through 2033. Driven by a transition to precision oncology, the market is poised to reach 25.45 Billion by 2033. Success in this sector requires balancing rapid R&D with complex regulatory submissions and strengthening partnerships with hospital systems to secure long-term procurement contracts in highly competitive global territories.
Market Forecast: 2027-2033 Projections
Between 2027 and 2033, the market will undergo significant expansion as adoption of next-generation screening tools becomes universal. Starting from the 2026 baseline, we anticipate a steady upward trajectory, culminating in a valuation of 25.45 Billion. This growth is contingent upon sustained investment in the diagnostic pipeline and the integration of these diagnostics into standardized clinical protocols across key public health initiatives.
Segmentation Analysis: Modality and End-Users
Segmentation is bifurcated into Imaging Tests and Stool Based Tests. By end-user, hospitals remain the largest volume consumers due to clinical diagnostic requirements. Diagnostic laboratories represent the fastest-growing segment, driven by their ability to scale throughput for centralized molecular screening. Cancer research institutes continue to play a pivotal role in validating the efficacy of new diagnostic biomarkers and assay technologies.
Regional Market Distribution and Performance
North America and Europe currently lead the Colorectal Cancer Diagnostics Market due to established healthcare reimbursement models. However, the APAC region is identified as a high-growth corridor. Regional market performance is heavily dictated by local access to advanced screening hardware, such as the imaging systems provided by Bruker Corp, and the penetration of private diagnostic service providers into emerging urban centers.
In-depth Regional Review
In North America, demand is centralized within large hospital networks, whereas in emerging markets, decentralized diagnostic hubs are gaining traction. Quest Diagnostics Inc has effectively leveraged regional infrastructure to capture market share. Constraints in these regions often relate to high import duties on diagnostic reagents and the time-intensive process of obtaining regional regulatory approvals, which local players must navigate to compete with international firms.
Company Profiles and Strategic Positioning
Medtronic Plc positions itself as a leader in procedural imaging technologies, while Eiken Chemical Co., Ltd. excels in specialized stool-based assay kits. Each firm adopts a distinct strategy: either vertical integration to control the diagnostic value chain or hyper-focus on specific biomarker research, as seen with Novigenix SA. This variety ensures that the broader ecosystem remains competitive and responsive to evolving clinical requirements.
Porter's Five Forces Analysis
The industry faces moderate threat of new entrants due to high regulatory barriers and complex patent landscapes. Bargaining power of buyers (hospitals) is significant, forcing manufacturers to compete on price and technical superiority. Competitive rivalry is intense, as firms like EDP Biotech Corp continuously iterate on products to prevent commoditization, while the availability of alternative screening methods keeps the threat of substitutes relatively high.
SWOT Analysis of the Industry
Strengths lie in technological innovation and early intervention efficacy. Weaknesses include high costs of diagnostic tests in developing nations. Opportunities are abundant in AI-driven screening and partnerships with insurance providers to subsidize preventative tests. Threats involve potential shifts in health policies that could restrict diagnostic reimbursement, along with intense pricing pressure from low-cost, high-volume generic test kit providers entering the global market.
Value Chain Analysis
The value chain begins with R&D and raw material sourcing—specifically high-grade biological reagents and chemical precursors. These flow to manufacturers for kit assembly and software development. Logistics providers move sensitive diagnostic materials to diagnostic laboratories, which perform high-complexity testing. Finally, actionable data is delivered to clinicians, enabling personalized treatment. Value flow is highly dependent on cold-chain efficiency and secure, encrypted diagnostic data transmission.
Investment Insights and High-Potential Areas
Investors should focus on firms developing non-invasive, high-sensitivity diagnostic assays. High-potential areas include multi-cancer early detection (MCED) platforms and companies successfully automating the laboratory workflow to reduce human error. Strategic recommendations emphasize investing in players with strong proprietary pipelines that are not solely dependent on a single diagnostic modality, thereby mitigating risk against shifts in clinical best practices.
Key Takeaways and Conclusion
The Colorectal Cancer Diagnostics Market is a high-growth arena, anchored by a 9.50% CAGR. With the market expected to reach 25.45 Billion by 2033, the integration of molecular diagnostics and AI represents the most significant investment opportunity. The shift from reactive to proactive, patient-centric testing models will define the successful enterprises of the next decade, provided they can navigate complex international regulatory frameworks.
Research Methodology for Baseline Estimates
Our estimates are triangulated using a proprietary multi-source approach. We combine primary data from interviews with clinical laboratory directors and regulatory affairs experts with secondary data from trade registries and macroeconomic indices. This triangulation ensures our 13.48 Billion baseline accounts for regional price variances, inventory turnover at major diagnostic ports, and long-term procurement spending across top-tier hospital systems.
Scope of the Report and Coverage Parameters
This report covers the global Colorectal Cancer Diagnostics Market, including imaging and stool-based modality segments. The scope includes major industry participants, regional performance analysis, and 2027-2033 forecasts. Limitations include a focus on clinical-grade diagnostics, excluding consumer-grade wellness trackers. Data provided captures commercial revenue and projected market expansion, focusing on trends impacting the 25.45 Billion target valuation.
Recent Developments and Industry Moves
Recent activity highlights a surge in strategic partnerships between genomics firms and large-scale hospital networks. Notable announcements include new product launches in automated stool-screening and advancements in imaging software by incumbents. These developments underscore a trend toward integrated, end-to-end diagnostic solutions, ensuring that industry participants remain ahead of evolving cancer screening standards and regulatory mandates globally.