Executive summary and significance of the Geosteering Technology Market
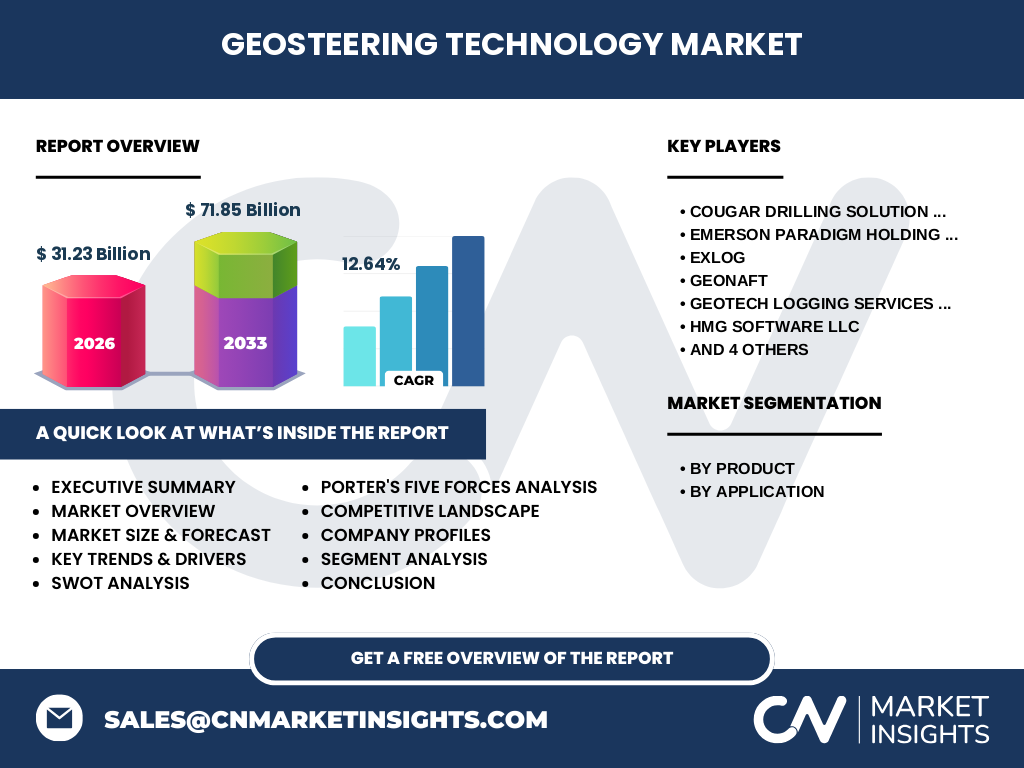
The Geosteering Technology Market represents a critical pillar in modern upstream operations, enabling precision placement of wellbores within hydrocarbon-rich zones. With a valuation of 31.23 Billion in 2026, the industry is transitioning from legacy techniques to advanced, data-driven automated systems. Our analysis reveals that real-time geological interpretation is now a non-negotiable asset for optimizing recovery rates, fundamentally altering the economics of global drilling and extraction initiatives.
Structural Growth Drivers and Market Forecast (2027-2033)
Propelled by a robust CAGR of 12.64%, the market is set to expand to 71.85 Billion by 2033. This trajectory is driven by the urgent need for increased recovery efficiency in complex shale reservoirs. As companies target deeper and more erratic pay zones, demand for high-fidelity Measurement-While-Drilling (MWD) and Rotary Steerable Systems (RSS) will remain the primary engine for sustained financial upside.
Competitive Benchmarking and Strategic Positioning
Market concentration is high, dominated by tier-one incumbents such as Halliburton Energy Services, Inc. and Schlumberger Limited. These firms leverage integrated service models to control the value chain. Conversely, specialized agile players like ROGII Inc. and Geonaft are disrupting the landscape by offering superior geological visualization software that integrates seamlessly with existing hardware, forcing legacy providers to rethink their digital transformation strategies for competitive survival.
Segmentation Analysis: Navigating Product and Application Categories
The market is segmented by product into Logging While Drilling (LWD), Measurement-While-Drilling (MWD), Rotary Steerable Systems (RSS), and Drive Systems. Applications are divided between Petroleum Development and Natural Gas Transportation infrastructure. Our research indicates that LWD and RSS segments command the highest margins, as operators prioritize technology that mitigates the high risks associated with horizontal drilling in unconventional deep-water and tight-gas fields.
Emerging Trends and Technological Shifts
The industry is witnessing a pivot toward automated geosteering workflows powered by edge computing. Machine learning integration is the most significant trend, allowing firms like Emerson Paradigm Holding LLC to deliver predictive insights directly to the drill bit. This reduction in latency is vital for minimizing non-productive time (NPT) and ensuring that drilling paths remain within the sweet spot of thin, challenging reservoirs.
COVID-19 Impact and Recovery Trajectory
The COVID-19 pandemic necessitated a harsh contraction, forcing an industry-wide focus on operational austerity. Recovery has been defined by a digital-first approach, as operators pivoted toward remote monitoring solutions to ensure personnel safety. This transition from labor-intensive site management to centralized, cloud-based monitoring has permanently lowered the break-even cost for many players, fostering a more resilient market environment since 2022.
Regional Market Performance and Geographic Distribution
North America retains a dominant market share, driven by aggressive shale play exploitation in the Permian Basin. However, the Middle East is emerging as a high-growth theater, where geosteering technology is essential for navigating mature, complex carbonate reservoirs. European markets remain focused on stringent safety regulations and North Sea deep-water environmental compliance, which creates a high barrier to entry for smaller technology providers.
In-depth Regional Review of Regulatory Environments
Operational landscapes in regions like the North Sea are dictated by strict Offshore Petroleum Regulator for Environment and Decommissioning (OPRED) standards. These localized hurdles require advanced, certifiable hardware from companies like Cougar Drilling Solution Inc. Meanwhile, regional growth in North America is fostered by a more permissive regulatory framework, allowing rapid adoption of proprietary data-loop technologies that maximize the output of unconventional natural gas assets.
SWOT Analysis of the Geosteering Technology Market
Strengths: Proprietary algorithms and high technological entry barriers. Weaknesses: High capital intensity and reliance on commodity price volatility. Opportunities: Expansion into geothermal drilling and automated mineral extraction. Threats: Escalating ESG mandates that prioritize decarbonization, potentially shifting capital away from traditional fossil fuel extraction. Adapting technology to support carbon capture and storage (CCS) is the critical threat-mitigation strategy for long-term viability.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with high-grade sensor manufacturing, moves through software integration platforms like those provided by HMG Software LLC, and culminates with field application by major drilling contractors. The flow is increasingly being disrupted by direct-to-operator software licenses, which allow energy companies to bypass third-party service providers, thereby retaining more of the value generated by high-efficiency drilling operations.
Porter's Five Forces Analysis
The threat of substitutes is low, given the specialized nature of subsurface telemetry. However, buyer power is increasing, as operators demand integrated, open-architecture software that prevents vendor lock-in. Intense rivalry between firms like Exlog and Geotech Logging Services LLC ensures that pricing remains competitive. Furthermore, the threat of new entrants is mitigated by the massive R&D requirements for reliable, high-temperature downhole sensors.
Investment Insights and Strategic Recommendations
Strategic investment should favor companies demonstrating software-hardware interoperability. The most high-potential areas are in autonomous drilling control systems that significantly reduce man-hours at the rig site. Our analysis suggests that institutional investors should target firms providing plug-and-play subsurface intelligence, as these companies are best positioned to capture the shifting budget allocations of energy majors looking to maximize returns on existing infrastructure.
Recent Developments and Industry News
The market is characterized by a wave of strategic partnerships aimed at integrating AI-driven interpretation software with traditional rotary steerable systems. Recent announcements from Terracosm Software, LLC highlight a broader industry move toward interoperable digital twins. These developments are critical, as they allow for real-time decision-making that was previously impossible, setting a new benchmark for operational efficiency in the global energy services sector.
Research Methodology and Baseline Estimates
Baseline estimates are triangulated using a multi-dimensional approach. We combine proprietary trade registry data, primary interviews with lead geosteering engineers, and secondary macroeconomic indicators. Our analysts validate the 31.23 Billion 2026 market figure through reconciliation of public financial filings of listed firms and bottom-up estimation of private technology providers' revenue streams to ensure high-confidence projections through 2033.
Conclusion and Final Key Takeaways
The Geosteering Technology Market is entering a period of accelerated evolution. With a projected value of 71.85 Billion by 2033, the shift toward automation and intelligent, data-driven drilling is irreversible. Stakeholders who prioritize technological agility and system interoperability will define the future of extraction economics. Success will depend on the ability to bridge the gap between legacy hardware expertise and next-generation software analytics.