Strategic Definition and Scope of the Decorative Paints Market
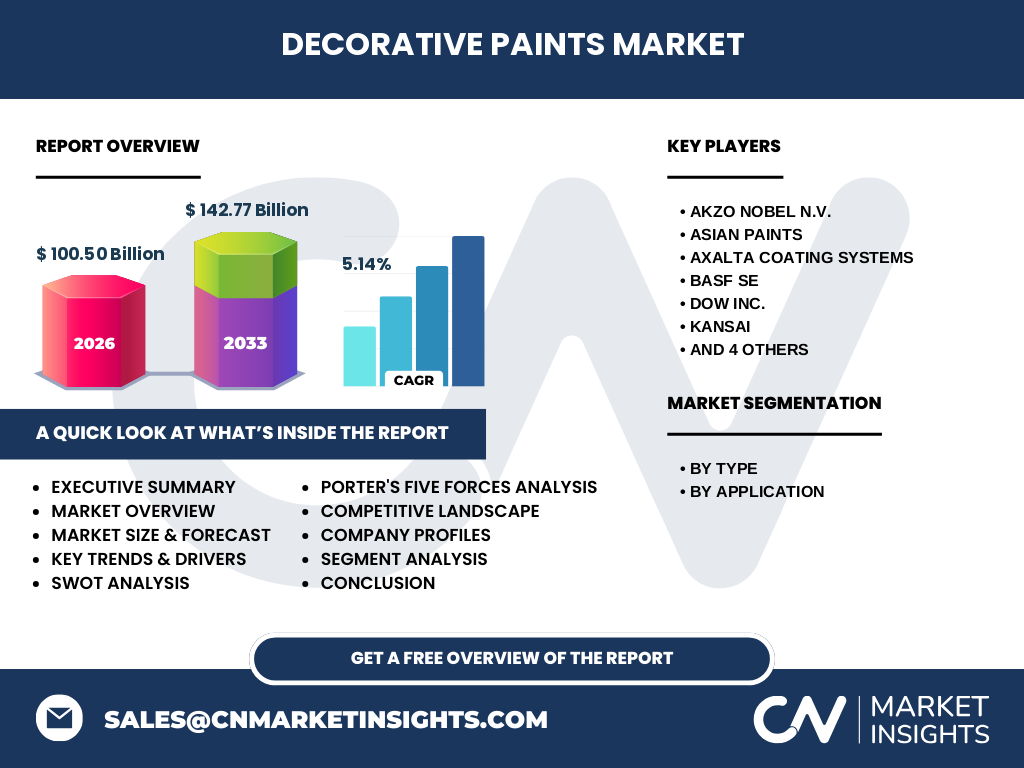
The Decorative Paints Market encompasses coatings utilized for aesthetic and protective finishes on architectural surfaces. With a 2026 market size of 100.50 Billion, our analysis includes both interior and exterior applications. The sector is fundamentally driven by property maintenance cycles and new construction demands, necessitating high-performance chemical formulations that comply with stringent volatile organic compound (VOC) regulations established by bodies like the EPA.
What are the structural growth drivers and market restraints?
Growth is primarily fueled by urbanization and a surge in residential renovation activity. However, the market faces significant logistical headwinds, including fluctuating raw material costs—specifically titanium dioxide and petroleum-based resins. The shift toward sustainable, eco-friendly formulations acts as both a driver for innovation and a barrier for legacy manufacturers unable to adapt their solvent-based product portfolios.
The Shift Toward Sustainable and Bio-based Decorative Paints
Industry trends reveal a pivot toward water-based technologies as consumers and builders prioritize indoor air quality. Companies like PPG Industries and Akzo Nobel N.V. are aggressively investing in bio-based binder research. This shift is not merely cosmetic; it is a strategic response to evolving global regulatory standards that penalize high-solvent emissions in dense urban environments.
Analyzing the COVID-19 Impact and Recovery Trajectory
The pandemic caused initial supply chain paralysis, but triggered a resilient recovery driven by the 'home improvement' boom. As homeowners redirected capital toward residential upgrades, demand for decorative coatings spiked. Our analysis indicates that companies with robust omnichannel distribution networks weathered the crisis significantly better than those reliant on traditional retail, facilitating a steady return to pre-pandemic growth patterns.
Competitive Benchmarking and Market Concentration
The landscape is characterized by high concentration among global giants. The Sherwin-Williams Company and Asian Paints demonstrate distinct strategic advantages through vertical integration. While Axalta Coating Systems focuses on specialized performance, the broader market remains dominated by firms leveraging massive economies of scale in procurement and global distribution centers at major ports like Rotterdam and Singapore.
Executive Summary of the Decorative Paints Market
Our research identifies a high-growth trajectory for the industry, with the market expected to reach 142.77 Billion by 2033. This reflects a robust CAGR of 5.14%. The synthesis of our findings suggests that success in the coming decade depends on navigating the transition from traditional solvent-based systems to low-VOC water-based solutions, supported by strategic technological R&D.
Market Forecast: Growth Projections 2027 to 2033
Projected growth from 2027 to 2033 estimates an expansion of the total market to 142.77 Billion. This forecast is predicated on continued industrialization in emerging economies and the necessity for high-durability architectural coatings in developed nations. The 5.14% CAGR reflects a consistent appetite for premium aesthetics coupled with functional protection in both residential and non-residential sectors.
Segmentation Analysis: Breaking Down the Market
The market is segmented by Type (Water-based vs. Solvent-based) and Application (Residential vs. Non-Residential). Water-based systems currently lead in market share due to regulatory tailwinds. Residential segments are seeing heightened demand for customizable finishes, while non-residential applications are prioritizing high-performance, fire-retardant, and weather-resistant coatings to minimize long-term maintenance costs for commercial infrastructure.
Regional Market Performance and Geographic Distribution
Performance varies significantly by geography. Asia-Pacific remains the dominant region, driven by rapid urbanization and infrastructure investment. Conversely, North America and Europe emphasize premiumization and environmental compliance. The data suggests that companies like Nippon Paint and Kansai hold significant localized advantages, effectively utilizing regional supply chains to hedge against global freight cost volatility.
In-depth Regional Review: Challenges and Opportunities
In developing markets, price sensitivity remains a critical constraint, favoring mass-market solvent-based products. In contrast, the European market faces stringent REACH regulations, forcing a rapid transition to sustainable alternatives. Analysts note that manufacturers must tailor their supply chain strategies to reflect these regional regulatory constraints to maximize profitability while maintaining compliance.
Company Profiles and Strategic Positioning
Leading players occupy distinct niches. Dow Inc. provides critical raw material innovation, while RPM International Inc. focuses on specialty coatings. BASF SE leverages its chemical expertise to lead in binder development. Collectively, these firms are positioning themselves to capture the 142.77 Billion value potential by emphasizing digital transformation in retail and advanced, high-performance product lineups.
Porter's Five Forces Analysis
The threat of new entrants remains moderate due to high capital requirements for R&D and distribution. Buyer power is fragmented in the residential sector but high in non-residential procurement. Rivalry is intense among top-tier firms like PPG Industries Inc. and Akzo Nobel N.V., forcing a constant state of innovation to defend market share against both global incumbents and localized, agile competitors.
SWOT Analysis: Strategic Outlook
Strengths: Strong brand equity and established global supply chains. Weaknesses: Sensitivity to raw material cost spikes. Opportunities: Expanding into green, bio-based architectural coatings. Threats: Increasingly stringent environmental regulations (VOC limits) and potential supply chain disruptions at major global ports. Our analysis indicates that companies proactively diversifying their raw material sources are best positioned to mitigate these identified threats.
Value Chain Analysis of Decorative Paints
The value chain originates with petrochemical and mineral raw materials, processed into intermediate binders and pigments by firms like Dow Inc., and finished by major manufacturers. The flow reaches end-users through integrated retail networks or direct commercial contracts. The margin capture is increasingly shifting toward companies that can guarantee both product consistency and compliance, rather than simple volume-based distribution.
Investment Insights and Strategic Recommendations
Investors should prioritize companies demonstrating a robust shift toward water-based R&D. High-potential areas include smart-coating technologies—paints that provide insulation or air-purifying properties. Given the projected market value of 142.77 Billion, firms integrating AI-driven supply chain management to counter volatility in raw material markets offer the most attractive risk-adjusted growth profiles for stakeholders.
Conclusion and Key Takeaways
The Decorative Paints Market is undergoing a critical transition period. Reaching 142.77 Billion by 2033 requires manufacturers to solve for both environmental sustainability and cost efficiency. The most successful participants will be those that effectively balance large-scale production capabilities with targeted innovation in low-VOC products, ensuring long-term relevance in an increasingly regulated and demanding global construction environment.
Research Methodology: How Baseline Estimates are Triangulated
Our estimates are derived from a triangulated approach: bottom-up analysis of trade registry data, top-down validation against macroeconomic indicators, and in-depth interviews with key stakeholders across the supply chain. We verify findings against proprietary databases of port logistics and regional infrastructure investment reports to ensure a high degree of confidence in our 5.14% CAGR projection.
Scope of the Report and Coverage Parameters
This report covers the global Decorative Paints Market, focusing on interior and exterior coatings for residential and non-residential applications. Analysis spans the period from 2026 to 2033. Our scope excludes industrial-grade, heavy-duty protective coatings, ensuring a laser focus on architectural segments while accounting for global regulatory and economic variables influencing the sector.
Recent Developments and Market Moves
Recent activity highlights a surge in mergers and acquisitions aimed at bolstering regional distribution and specialized chemical capacity. Leading firms like Nippon Paint have announced significant green-transition investments, while others are launching digital color-matching partnerships. These moves indicate a market-wide effort to capture value by improving the end-user experience and aligning operations with global sustainability goals.