What is the scope and industry significance of the Europe Infertility Treatment Devices and Equipment Market?
The Europe Infertility Treatment Devices and Equipment Market comprises critical clinical hardware including ovum aspiration pumps, micromanipulator systems, and incubators. It serves as the backbone for Assisted Reproductive Technology (ART) clinics. As demographics shift, this market provides the technological infrastructure necessary to address rising infertility rates, directly influencing reproductive outcomes for millions across the European Union and the United Kingdom.
Structural Growth Drivers, Restraints, and Opportunities
Growth is propelled by delayed parenthood and increasing public health coverage for fertility cycles. However, the market faces logistical hurdles due to strict MDR (Medical Device Regulation) compliance requirements. Opportunities exist in scaling sperm analyzer systems and automated cryopreservation solutions, enabling clinics to handle higher patient volumes while maintaining strict ISO-certified quality standards across laboratory workflows.
Emerging trends and growth patterns in the European landscape
A pivot toward automated embryology is the most significant trend. We observe clinics integrating AI-driven sperm analyzer systems to improve selection accuracy. There is a distinct move toward minimalist incubator designs that mimic physiological environments more closely. These trends prioritize patient-centric outcomes and efficiency, positioning firms that innovate in digital lab integration to capture higher market share through 2033.
How did the COVID-19 pandemic impact market dynamics and recovery?
The pandemic forced a temporary suspension of elective reproductive procedures, causing a sharp revenue dip. Post-2021, the market experienced a robust rebound trajectory driven by a backlog of elective fertility surgeries. Our analysis shows that clinics prioritized hygiene-focused device procurement, leading to long-term investment in closed-system technologies that minimize contamination risks during the critical fertilization process.
Competitive Benchmarking and Strategic Dynamics
The market is characterized by high consolidation, with key players like Cooper Surgical and Cook Medical holding substantial territory. Competitive dynamics are shaped by technical superiority in micromanipulation. Smaller innovators like Hamilton Thorne differentiate via specialized software for sperm analysis. Strategic moves center on cross-border distribution networks, leveraging established supply chains to maintain competitive pricing amid rising raw material costs for medical-grade polymers.
Executive Summary of Europe Infertility Treatment Devices and Equipment Market
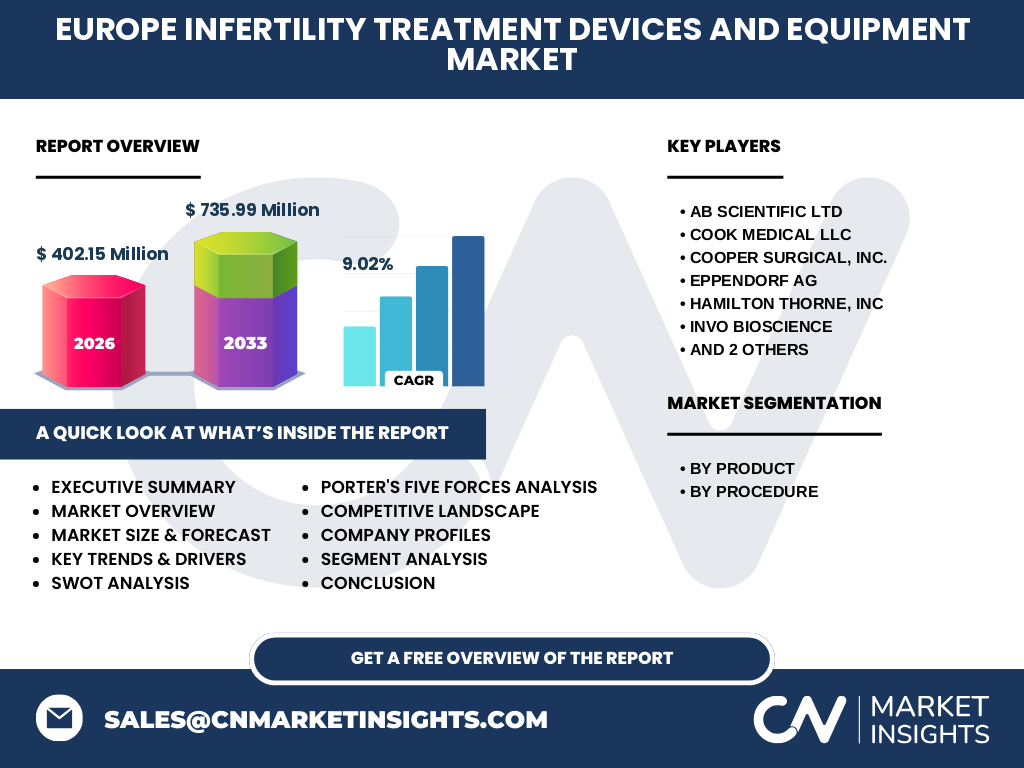
Valued at 402.15 Million in 2026, the market is poised for rapid expansion. We project the value to reach 735.99 Million by 2033, reflecting a solid CAGR of 9.02%. The synthesis of this report suggests that technological advancements in lab hardware are the primary catalyst for this acceleration, overcoming regional regulatory bottlenecks.
Market Forecast 2027 to 2033
Our projections indicate that the market will undergo a sustained 9.02% CAGR, reaching a valuation of 735.99 Million by 2033. This trajectory is supported by increased clinical penetration of sperm separation devices. We anticipate the most significant volume growth between 2029 and 2031, as health policy reforms across Western Europe improve patient access to advanced ART procedures.
Segmentation Analysis: Products and Procedures
The market is segmented by product categories—including ovum aspiration pumps and incubators—and procedural applications—ART, artificial insemination, and fertility surgery. Assisted Reproductive Technology (ART) commands the largest segment, acting as the primary driver for high-end equipment procurement. Each segment plays a specialized role in the clinical value chain, from diagnostic screening through to the final stages of implantation.
Regional market analysis and geographic distribution
Europe’s market performance is highly fragmented. Western Europe dominates due to advanced healthcare infrastructure and favorable government reimbursement policies. Conversely, the Central and Eastern European regions are demonstrating high growth potential as private clinical investment flows into modernizing lab facilities. Regional success depends heavily on adhering to the European Medicines Agency (EMA) standards and local procurement pathways.
In-depth regional review of key markets
Germany and the Nordics remain the innovation hubs, prioritizing high-precision micromanipulator systems. Spain and Italy show high demand for sperm analyzer systems due to a high volume of medical tourism. Regional performance remains linked to local regulatory efficiency; clinics in ports-adjacent hubs benefit from faster logistics for imported consumables compared to landlocked regions, affecting overall operational costs.
Strategic positioning of leading companies
Industry leaders like Eppendorf AG focus on high-durability laboratory equipment, while INVO Bioscience is disrupting the market with cost-effective, simplified ART systems. Rocket Medical plc. leverages its expertise in procedural hardware to ensure seamless clinical integration. These players maintain dominance by fostering strong ties with key opinion leaders (KOLs) in reproductive medicine and securing patents for next-generation, high-throughput analytical tools.
Porter's Five Forces analysis
The threat of new entrants is moderate due to strict regulatory hurdles, while the bargaining power of suppliers remains high for specialized sensors. Rivalry among established firms like AB Scientific is intense, driving innovation. Buyers—predominantly private fertility clinics—exert pressure through price sensitivity. Overall, the industry exhibits high barriers to exit due to deep clinical integration and long-term service contracts.
SWOT Analysis: Strategic Outlook
Strengths: Advanced technical infrastructure. Weaknesses: High reliance on specialized raw materials. Opportunities: Scaling in emerging Eastern European markets through 2033. Threats: Changing European Union medical device regulations that may impact product certification timelines. Companies must leverage their R&D strength to mitigate these threats, focusing on compliance-first manufacturing to ensure market continuity.
Value chain analysis from raw materials to end-users
The value chain initiates with specialized raw material procurement for medical-grade hardware, followed by precision engineering. Players like Microptic add value through software integration. The distribution phase, involving key logistics hubs, moves equipment to specialized IVF clinics. The final value creation occurs at the point of care, where clinicians use these tools to optimize patient reproductive outcomes.
Investment insights and high-potential areas
We identify AI-integrated embryology platforms and low-cost ART procedure kits as high-potential investment areas. Investors should target companies showing strong MDR-compliance capabilities, as regulatory stability is a core asset. The market size expansion to 735.99 Million suggests a favorable environment for M&A activity, particularly for firms looking to consolidate sperm analysis and aspiration technologies into a single integrated suite.
Conclusion and key takeaways
The Europe Infertility Treatment Devices and Equipment Market is in a state of robust expansion, underpinned by a 9.02% CAGR. Success hinges on technological innovation, strict adherence to regional regulatory frameworks, and agility in clinical distribution. Firms that align their product roadmap with current trends in automation and digitalization will undoubtedly emerge as leaders in the 2027–2033 market cycle.
Research methodology and data triangulation
Our methodology utilizes triangulation between proprietary trade registry data, primary interviews with European fertility clinic directors, and secondary macroeconomic indicators. We cross-reference production volume reports with clinical procedure audits to estimate the installed base of micromanipulator systems. This rigorous process ensures that the reported figures represent an accurate, data-driven forecast of market potential.
Scope of the report: coverage parameters and limitations
This research covers the European Union and the United Kingdom, focusing on devices for ART, artificial insemination, and surgery. We exclude non-device pharmacological treatments. The analysis focuses on B2B market dynamics; however, the impact of regional health insurance policy fluctuations on procurement is considered a potential variable that could influence the 2027–2033 forecast baseline.
Recent developments, launches, and strategic moves
Recent strategic moves emphasize AI-based diagnostic partnerships between device manufacturers and specialized software labs. Market participants are increasingly announcing co-branded hardware to enhance clinical efficiency. These developments, alongside localized product launches for sperm separation, indicate a industry-wide pivot toward digital transformation aimed at improving cycle success rates while lowering per-cycle costs for major clinic networks.