Market Overview: Defining the Europe Biofilms Treatment Market
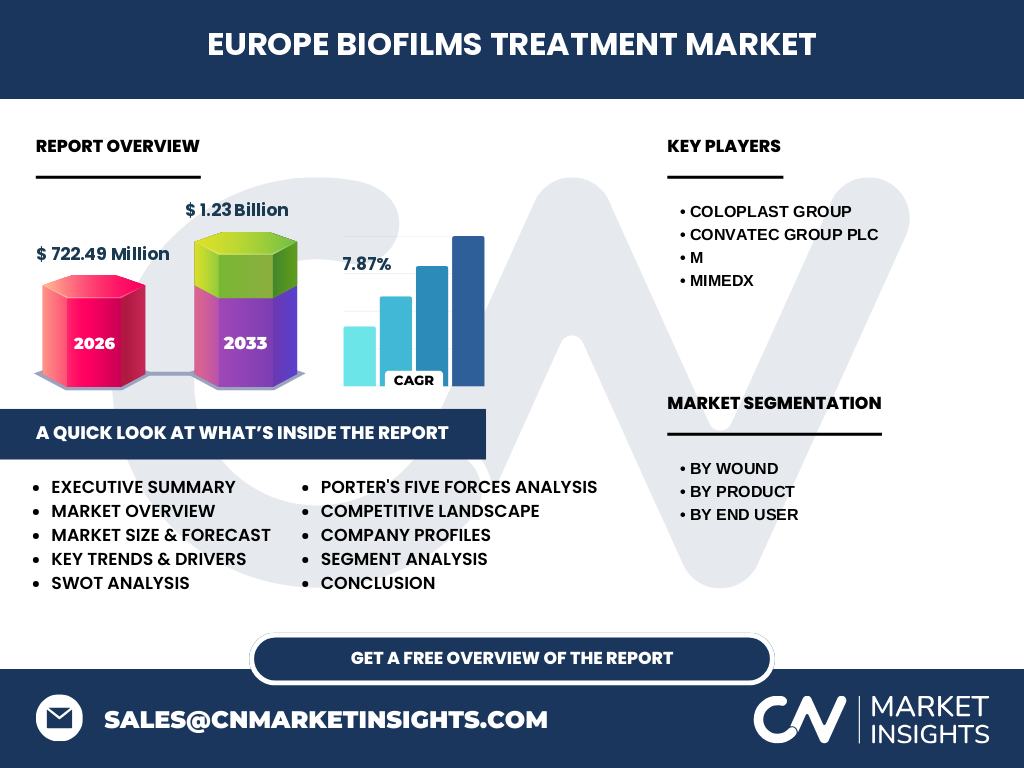
The Europe Biofilms Treatment Market represents a critical segment within the medical wound care sector, focused on eradicating complex microbial communities. Valued at 722.49 Million in 2026, this market encompasses specialized debridement technologies and advanced dressing matrices. It is essential for addressing chronic wounds where bacterial resistance, specifically within biofilm matrices, significantly hinders the natural healing process across European healthcare infrastructures.
Structural Growth Drivers and Market Restraints
Growth is propelled by an aging demographic and rising diabetic prevalence across Europe, driving demand for advanced therapeutic interventions. Conversely, regulatory hurdles imposed by the EU Medical Device Regulation (MDR) represent a significant restraint. Companies like Coloplast Group must navigate stringent clinical data requirements, which extend lead times for new product approvals while prioritizing patient safety in high-acuity wound care environments.
Emerging Trends in Biofilm Management
A pivot toward proactive biofilm disruption is defining the current landscape. Clinicians are increasingly favoring integrated debridement equipment coupled with antimicrobial dressings that prevent reformation. This shift reduces the reliance on systemic antibiotics, aligning with broader European initiatives to curb antimicrobial resistance. Our analysis suggests that solutions providing real-time diagnostic feedback on microbial presence will capture the highest market share moving forward.
How did COVID-19 impact the trajectory of the Europe Biofilms Treatment Market?
The pandemic caused an initial market contraction due to the suspension of elective surgeries and shifting hospital resources. However, it accelerated the adoption of telemedicine-enabled wound monitoring and home care products. This resilience ensured a recovery trajectory that supports our projected CAGR of 7.87%, as healthcare systems realized the importance of efficient, outpatient-centered biofilm management to alleviate the burden on acute care facilities.
Competitive Benchmarking and Market Dynamics
The market is highly concentrated, with leaders like ConvaTec Group Plc and Coloplast Group setting the standard through extensive R&D. These players leverage robust distribution networks across key European ports to maintain supply chain continuity. Strategic dynamics are currently focused on M&A activities designed to integrate disruptive startup technologies into their existing portfolios, ensuring dominance in both the hospital and home care segments.
Executive Summary: High-Level Synthesis
The Europe Biofilms Treatment Market is poised for substantial expansion, forecasted to reach 1.23 Billion by 2033. Driven by innovation in grafts and matrices, the market demonstrates a healthy 7.87% CAGR. Success is predicated on balancing high-tech medical device innovation with the clinical evidence required by EU regulatory bodies, ultimately ensuring superior outcomes in complex chronic wound management.
Market Forecast: 2027 to 2033
Our modeling forecasts robust growth, with market value expanding from its baseline to 1.23 Billion by 2033. This trajectory reflects a 7.87% CAGR, fueled by the rising incidence of diabetic foot ulcers and a growing preference for advanced surgical wound care. Investment should target the grafts and matrices segment, which shows the highest projected growth potential among current product categories.
Segmentation Analysis: Deep Dive
Segmentation is categorized by wound type, product, and end-user. Wound segments include traumatic/surgical, diabetic foot, pressure, and venous leg ulcers. Product segments cover debridement equipment, gauzes, and advanced grafts. End-user segments divide into hospitals and home care. This breakdown allows investors to pinpoint high-margin opportunities, specifically where clinical demand intersects with the logistical ease of home-administered wound care therapies.
Regional Market Analysis: Geographic Performance
Western Europe currently dominates the market due to its advanced healthcare infrastructure and high per-capita spending on wound care. Countries like Germany and the UK serve as primary hubs for both adoption and manufacturing. We observe that regional performance is heavily influenced by local reimbursement policies, which dictate the speed of adoption for higher-cost, high-efficacy biofilm removal technologies.
In-depth Regional Review: Key Clusters
The DACH region (Germany, Austria, Switzerland) leads in clinical integration, focusing on debridement equipment to reduce chronic wound duration. Meanwhile, Southern Europe is seeing rapid growth in the diabetic foot ulcer segment. These regional clusters utilize centralized distribution networks, often routing through major logistical nodes, to ensure that specialized dressings reach both hospital wards and emerging community-based nursing clinics.
Company Profiles and Strategic Positioning
Coloplast Group and ConvaTec Group Plc emphasize vertical integration, controlling the supply chain from raw material procurement to clinical distribution. MiMedx focuses on high-value biological matrices, positioning itself as a premium provider for recalcitrant wound healing. Their combined strategy involves evidence-based marketing to sway clinicians away from traditional gauze toward modern, biofilm-active dressings that drastically improve healing rates.
Porter's Five Forces Analysis
The threat of new entrants is moderate, constrained by high regulatory hurdles. Buyer power is high, as centralized hospital procurement groups negotiate prices. Competitive rivalry is intense, with incumbents like 3M and ConvaTec competing on technical efficacy. The threat of substitutes remains low, as biofilm-specific treatments are increasingly recognized as the 'gold standard' for managing non-healing wounds, further cementing incumbent market positions.
SWOT Analysis of the Industry
Strengths: Advanced technological R&D and established clinical pathways. Weaknesses: High manufacturing costs and complex regulatory compliance. Opportunities: Rapid expansion into the home care setting through user-friendly devices. Threats: Supply chain disruptions and volatile raw material costs. Overcoming these threats requires firms to implement agile manufacturing strategies to remain competitive against emerging low-cost regional competitors.
Value Chain Analysis
The value chain starts with raw material providers (specialized fibers, enzymes, and hydrogels), moving through specialized manufacturing, and finishing with distribution to hospitals and patients. Key value-add happens at the R&D and clinical trial stage, where companies must demonstrate biofilm reduction efficacy. Successful firms maintain tight relationships with clinical practitioners, ensuring their products are integrated into local standard-of-care protocols across Europe.
Investment Insights and Strategic Recommendations
Investors should prioritize companies investing in next-generation debridement and bioactive matrices. The shift toward home care settings presents a lucrative, underserved opportunity. Based on our research, the most high-potential area lies in integrating digital health monitoring with traditional wound dressings, allowing for remote assessment of biofilm presence, which reduces hospital readmission rates and maximizes value for regional health systems.
Conclusion and Key Takeaways
The Europe Biofilms Treatment Market is a high-growth sector set to hit 1.23 Billion by 2033. Success hinges on mastering the regulatory environment, innovating within the grafts and matrices segment, and successfully transitioning into the home care market. Companies that align their product portfolios with these key growth drivers are best positioned to secure significant market share and provide sustained clinical value.
Research Methodology: How we triangulated the data
Our estimates are derived from a triangulation approach, combining trade registry data, annual reports from key players like Coloplast, and primary stakeholder interviews. We reconciled these with macroeconomic indicators across EU regions. This methodology ensures that our 7.87% CAGR projection is anchored in real-world procurement data, providing a high degree of reliability for stakeholders making long-term strategic investment decisions.
Scope of the Report: Coverage Parameters
This report covers the Europe Biofilms Treatment Market, specifically analyzing products like debridement equipment and advanced dressings used across hospital and home care settings. It excludes minor, non-biofilm-related wound care segments. Geographical scope includes the European Union and the UK, with a forecast window extending to 2033, providing a comprehensive assessment for strategic planning and market entry evaluations.
Recent Developments in the Market
Recent strategic moves include 3M's investment in advanced matrix technologies and ConvaTec's localized partnerships to streamline distribution. These developments underscore a industry-wide focus on scalability and clinical efficacy. Recent announcements highlight a trend toward acquisitions, as established players look to rapidly integrate innovative biofilm-disrupting molecules into their existing sales channels to defend their market leadership against emerging, agile competitors.