Market overview and industry significance of the South and Central America Kidney Stones Retrieval Devices Market
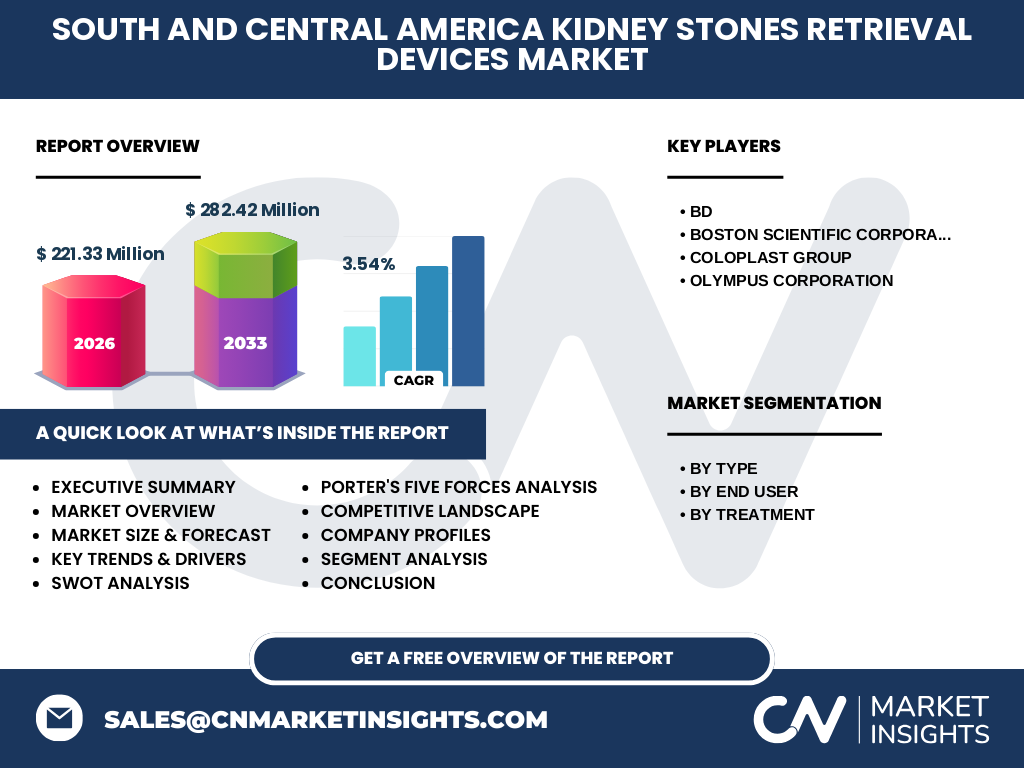
The South and Central America Kidney Stones Retrieval Devices Market is valued at 221.33 Million in 2026. It encompasses critical medical technologies including lithotripters and ureterorenoscopes used to address high urolithiasis prevalence. Given the regional burden of chronic kidney disease, these devices are essential clinical tools for improving patient outcomes through minimally invasive urological procedures across major regional healthcare systems.
Structural growth drivers and regional market constraints
Growth is primarily driven by rising incidences of metabolic disorders and expanded access to surgical urology in urban centers. Conversely, logistical hurdles involving complex customs clearance at ports like Santos or Buenos Aires act as significant restraints. Our analysis suggests that supply chain volatility for specialized polymers and high-grade stainless steel remains a bottleneck for manufacturers entering the South and Central American landscape.
Emerging trends and technology adoption patterns
The market is witnessing a distinct shift toward digital ureterorenoscopy, enabling superior visualization for complex stone extractions. We observe that hospitals are increasingly prioritizing disposable device integration to eliminate sterilization risks. This trend favors global incumbents capable of maintaining robust regional distribution channels while providing the high-frequency technical training required by local urologists to operate advanced retrieval platforms.
COVID-19 impact analysis and the recovery trajectory
The pandemic caused an initial severe contraction in elective urological surgeries due to prioritized respiratory care. However, the recovery trajectory is marked by a significant backlog of non-emergency stone removal procedures. Our data indicates that the market is now stabilizing, supported by a strong rebound in outpatient volume as healthcare providers optimize theater scheduling to clear deferred clinical cases.
Competitive landscape and strategic dynamics
The competitive environment is characterized by high market concentration, with industry leaders like Boston Scientific Corporation, Olympus Corporation, BD, and Coloplast Group dominating through innovation. Strategic competition centers on technological superiority in laser lithotripsy and stent biocompatibility. These firms maintain dominance by leveraging deep-rooted relationships with regional hospital procurement networks and investing in localized clinical education programs to ensure brand loyalty.
Executive summary of the market's trajectory
The South and Central America Kidney Stones Retrieval Devices Market is poised for consistent expansion, with a projected valuation of 282.42 Million by 2033. This represents a steady CAGR of 3.54%. Driven by technological advancements in minimally invasive surgery, the market is shifting toward more efficient, patient-centric removal solutions that reduce post-operative recovery times and total hospital stay costs for public health systems.
Market forecast from 2027 to 2033
Based on our proprietary modeling, the market will grow from 2027 to 2033 to reach 282.42 Million. This CAGR of 3.54% reflects the increasing adoption of specialized ureteral stents and advanced lithotripters. While economic fluctuations in major economies like Brazil and Mexico present potential risks, the fundamental clinical demand for stone management ensures a positive long-term growth outlook for all core device segments.
Segmentation analysis by type, end user, and treatment
The market is segmented by product type (lithotripters, stone removal devices, stents, ureterorenoscopes), end user (hospitals, specialty clinics, ASCs), and treatment method. Intracorporeal ureteroscopy currently holds a dominant share due to its precision. Hospitals and clinics remain the primary procurement channels, though we anticipate faster growth in ambulatory surgery centers as regional infrastructure modernizes to support shorter-stay, cost-effective interventional procedures.
Regional market analysis and geographic distribution
Regional performance is highly skewed toward Brazil, Mexico, and Colombia, where centralized healthcare spending is most concentrated. These regions benefit from better access to advanced lithotripsy units. Smaller markets in Central America rely heavily on imported, refurbished equipment, creating a tiered market structure. Our analysis shows that manufacturers focusing on regional distribution hubs in these high-growth nations achieve superior margins compared to those attempting broad, fragmented coverage.
In-depth review of key regional markets
Brazil remains the dominant powerhouse due to its extensive public and private hospital network. Mexico follows closely, showing strong ASCs growth for lithotripsy services. Conversely, regional volatility necessitates that companies maintain flexible supply chains to handle specific regulatory hurdles mandated by agencies like ANVISA. The ability to navigate these distinct, complex regulatory environments is a primary success factor for international device manufacturers operating in this region.
Company profiles and strategic positioning
Boston Scientific Corporation and Olympus Corporation lead through high-end, proprietary imaging technology. BD maintains a strong foothold in the stent segment, focusing on high-volume, cost-effective solutions. Coloplast Group leverages its specialized urology portfolio to capture the niche specialty clinic market. These players are increasingly differentiating themselves through value-added services, including remote clinical support and long-term device maintenance contracts that lock in recurring hospital procurement revenue.
Porter's Five Forces assessment
The bargaining power of suppliers is moderate, constrained by high-quality material requirements. However, competitive rivalry is intense among top-tier global incumbents. The threat of new entrants is mitigated by high regulatory entry barriers and the necessity of strong clinical distribution networks. Buyer power remains high, as consolidated public healthcare procurement units demand aggressive pricing, forcing companies to prove long-term clinical value to secure long-term government contracts.
SWOT analysis of the sector
Strengths: Established clinical demand for urolithiasis treatment. Weaknesses: High dependence on expensive imported technology. Opportunities: Rapid expansion of minimally invasive procedures in outpatient settings. Threats: Economic volatility and shifting currency values impacting import affordability. Firms that mitigate these risks through local partnerships or diversified pricing models are better positioned to capture long-term value despite the region's inherent economic unpredictability.
Value chain analysis from raw materials to end-users
The value chain originates from specialized polymer and metal manufacturers in global markets, flowing through international OEMs to regional distributors. These distributors manage logistical complexities before delivering finished devices to hospitals. The end-user, typically a urologist, is the primary influencer in procurement, often prioritizing device performance and reliability over raw acquisition costs, which necessitates strong clinical presence and high-touch technical support throughout the regional sales cycle.
Investment insights and strategic recommendations
We identify Ambulatory Surgery Centers as high-potential areas for investment, given the regional trend toward decentralized care. Firms should prioritize training-led sales strategies to build brand equity among local practitioners. Strategic moves should focus on partnering with regional distributors who possess deep knowledge of import regulatory compliance, as this remains the most significant barrier to scaling operations successfully within the South and Central American market environment.
Conclusion and key takeaways
The South and Central America Kidney Stones Retrieval Devices Market is a resilient sector projected to reach 282.42 Million by 2033. Success depends on navigating regional regulatory nuances and capitalizing on the shift toward outpatient surgery. Stakeholders should focus on high-performance ureterorenoscopy products and maintain robust distribution chains to overcome the structural hurdles inherent in this geographically diverse and economically complex healthcare landscape.
Research methodology and data triangulation
Our baseline estimates are built by triangulating trade registry data with proprietary primary interviews with urology department heads across major cities. We synthesize this with macroeconomic indicators, including healthcare expenditure trends and demographic shifts. By cross-referencing company filings and public procurement data, we ensure that our 3.54% CAGR projection and regional segment analysis remain accurate and reflective of the actual commercial environment in this market.
Scope of the report and coverage parameters
This report provides an authoritative analysis of the market from 2027 to 2033, covering specific segments including lithotripters, stone removal devices, stents, and ureterorenoscopes. The scope includes geographic coverage of South and Central American nations, with particular focus on Brazil, Mexico, and Argentina. Limitations include the exclusion of non-retrieval urological devices and focus primarily on clinical-grade hardware used in professional healthcare settings for stone removal.
Recent developments in the market
Recent developments underscore a trend toward product consolidation and localized partnerships. Major players have announced collaborations with regional health networks to accelerate the adoption of next-generation lithotripsy. Furthermore, recent product launches emphasize superior, infection-resistant stent materials, which are crucial for improving patient recovery in clinical settings. Such strategic moves indicate a transition toward higher-value, technology-driven solutions as the market matures and moves beyond basic device commoditization.