What is the scope and industry significance of the Europe Pre-lit Disposable Vaginal Speculum Market?
The Europe Pre-lit Disposable Vaginal Speculum Market encompasses single-use diagnostic tools integrated with internal light sources. These instruments are pivotal for optimizing clinical efficiency in gynecology. By eliminating the need for external fiber-optic light cables, these devices significantly reduce cross-contamination risks, adhering to strict EU Medical Device Regulation (MDR) standards that prioritize patient safety and sanitation in high-throughput clinical environments.
Structural Growth Drivers and Market Constraints
The market is propelled by a 3.31% CAGR, driven by heightened demand for infection control. Key drivers include the shift toward value-based care and the necessity for streamlined exam workflows. However, the market faces logistical hurdles, specifically supply chain bottlenecks at major ports like Rotterdam, and strict regulatory compliance costs associated with the transition from the legacy MDD to the current MDR framework.
What emerging trends define the Europe Pre-lit Disposable Vaginal Speculum Market?
The primary trend is the de-skilling of diagnostic setups, where clinicians prioritize pre-lit, all-in-one solutions to minimize setup time. Our analysis highlights a move toward ergonomic designs that improve patient comfort. Furthermore, sustainable manufacturing practices are gaining traction, forcing innovators to address the environmental footprint of high-grade medical plastics used in the assembly of these disposable instruments.
How did the COVID-19 pandemic influence market trajectory?
During the pandemic, the market experienced a temporary stagnation due to the suspension of elective gynecological exams. However, the post-pandemic recovery was robust, fueled by a persistent backlog of diagnostic procedures. This period underscored the criticality of disposable, sterile, and ready-to-use instruments, accelerating the adoption of pre-lit technology over reusable, cable-dependent fiber-optic systems that require labor-intensive sterilization protocols.
Competitive Benchmarking in the European Landscape
The competitive landscape is characterized by high market concentration among specialized entities such as OBP Medical Corporation, ClearSpec LLC, and MedGyn Products, Inc. Strategic dynamics involve aggressive intellectual property protection and partnerships with major medical distributors. Larger players like Hill Rom Holding Inc leverage integrated sales channels, while smaller firms innovate via niche designs focused on specific anatomical compatibility and light output optimization.
Executive Summary of the Europe Pre-lit Disposable Vaginal Speculum Market
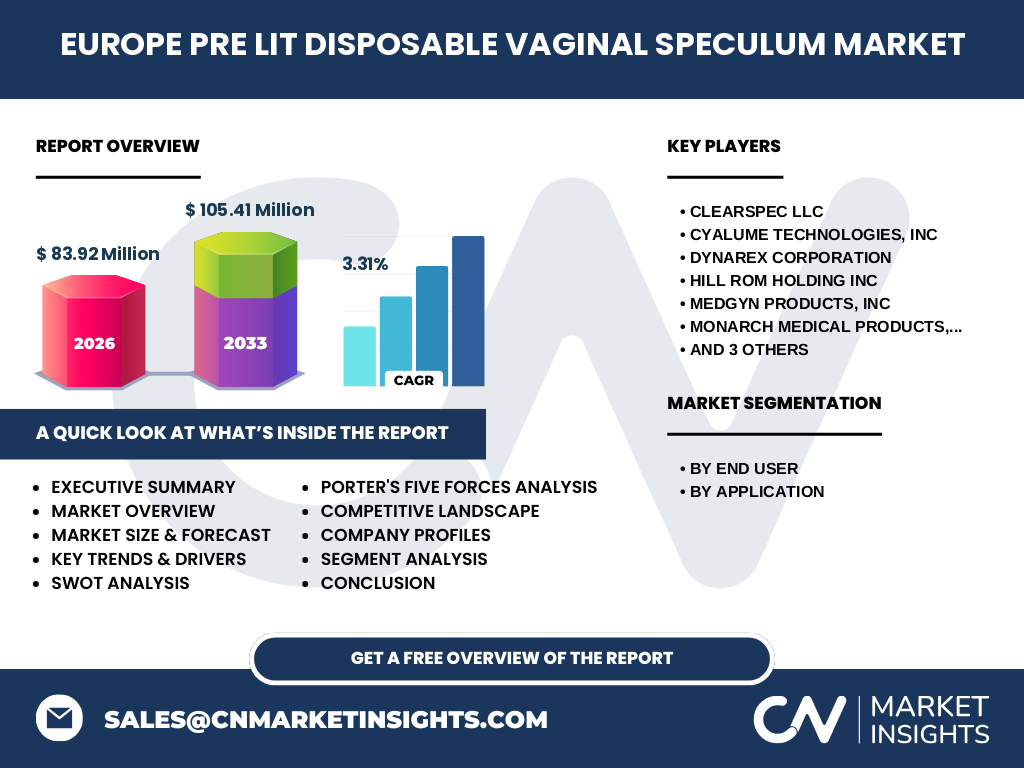
Valued at 83.92 Million in 2026, the market is poised for steady expansion to 105.41 Million by 2033. This research confirms that the shift toward disposable technologies is structural rather than cyclical. Companies that successfully navigate the EU MDR landscape and offer high-lumen, single-use solutions are best positioned to capture a larger share of the fragmented European clinical market.
What is the projected market growth forecast for 2027 to 2033?
Based on our modeling, the market will witness a consistent growth trajectory with a 3.31% CAGR throughout the forecast period. We project the market valuation to scale from current levels to reach 105.41 Million by 2033. This growth is underpinned by rising public health expenditures and an increasing emphasis on patient-centric, hygienic diagnostic environments across both Western and Eastern European healthcare systems.
Breakdown of Market Segmentation Analysis
Our analysis segments the market by: End User (Hospitals, Ambulatory Care Centers, and Diagnostic Centers) and Application (Surgery and Diagnosis). Hospitals remain the largest volume consumers due to high procedure counts. Meanwhile, Ambulatory Care Centers are the fastest-growing segment, as they increasingly demand the efficiency and portability that pre-lit, single-use specula provide in fast-paced outpatient settings.
Regional Market Distribution and Performance
The European market displays uneven growth, with Germany, France, and the UK acting as primary revenue anchors. These regions benefit from advanced reimbursement models for disposable diagnostic equipment. Conversely, Southern and Eastern Europe represent emerging frontiers where growth is contingent upon the modernization of diagnostic facility infrastructure and the alignment of local procurement budgets with EU medical safety standards.
In-depth Regional Review: Key Geographic Insights
Western Europe dominates due to high adoption rates of advanced medical technologies. Our data indicates that hospitals in the DACH region prioritize high-quality, FDA/MDR-compliant equipment, favoring providers like Dynarex Corporation. The UK market, characterized by centralized procurement, is increasingly seeking cost-effective bulk solutions, providing significant entry opportunities for Premier, Inc. (S2S Global) to leverage its expansive supply chain infrastructure.
Strategic Positioning of Leading Companies
Companies such as OBP Medical and MedGyn Products are pure-play innovators, focusing on high-lumen, integrated light solutions. Trinity Sterile, Inc. differentiates itself through customized procedural kits, adding value through convenience. Strategic positioning remains centered on MDR certification status; those with early compliance hold a distinct competitive advantage over smaller firms still navigating the complex re-certification processes required for entry into the EU.
Porter's Five Forces Analysis of the Market
The threat of substitutes is low given the clear clinical preference for sterile, disposable specula. Bargaining power of buyers (large hospitals) remains high, exerting price pressure. Conversely, the threat of new entrants is moderated by high regulatory barriers. Competitive rivalry is intense, with firms constantly innovating to improve light durability and ergonomic profiles to secure favorable hospital supply contracts.
SWOT Analysis: Strategic Outlook
Strengths: Established clinical need for sterile solutions. Weaknesses: High manufacturing and regulatory compliance costs. Opportunities: Expansion into Eastern European diagnostic centers. Threats: Supply chain volatility and potential raw material price hikes for medical-grade polymers. The strategic imperative for all players is to diversify supplier networks to mitigate risks within the European logistics corridor.
Value Chain Analysis from Raw Materials to End-users
The value chain starts with the procurement of medical-grade polymers and integrated LED components. Value is added during the injection molding and light-source integration phases. Manufacturers then distribute products through specialized medical device wholesalers before reaching end-users in hospitals. Efficiency in this chain is highly dependent on managing inventory at hubs, ensuring that sterile-packaged products maintain integrity throughout the distribution phase.
Investment Insights and Strategic Recommendations
We recommend investors focus on firms with strong regulatory-affairs departments capable of navigating the EU MDR. High-potential areas include the development of biodegradable diagnostic tools, which could capture significant market share as European hospitals face increasing sustainability mandates. Companies with existing footprints in the Ambulatory Care segment are particularly attractive, given the shifting preference toward decentralized medical diagnostics.
Key Takeaways and Conclusion
The Europe Pre-lit Disposable Vaginal Speculum Market is a high-growth sector set to reach 105.41 Million by 2033. The industry's shift toward single-use, high-safety diagnostic tools is irreversible. Success will be determined by regulatory agility, superior light-integration technology, and the ability to navigate complex European procurement landscapes while maintaining supply chain resilience.
Detailed Research Methodology
Our estimates are triangulated by synthesizing trade registry data with primary stakeholder interviews from procurement managers and clinical directors. We integrate macroeconomic indicators like healthcare expenditure trends with proprietary shipment modeling to adjust for the MDR compliance lag. This multi-layered approach ensures high accuracy in our 2027–2033 projections, capturing both market volume and qualitative trends.
Scope of the Report and Coverage Parameters
This report covers the European market, specifically focusing on pre-lit disposable specula utilized in hospitals, ambulatory, and diagnostic settings. The scope excludes traditional reusable fiber-optic systems. Limitations include potential volatility in import duties for non-EU manufactured components and the ongoing evolution of European national healthcare policies that may impact local procurement budgets during the forecast period.
Recent Developments and Market Movements
Recent activity highlights a surge in strategic partnerships between Cyalume Technologies, Inc and European distributors to enhance distribution speed. Furthermore, Monarch Medical Products, Inc. has announced investments in LED efficiency optimization, directly addressing the clinical demand for brighter, longer-lasting, and reliable internal light sources. These moves signal a broader industry trend toward performance-based differentiation in a crowded diagnostic device market.