Market Overview: Defining the In-Game Advertising Market ecosystem
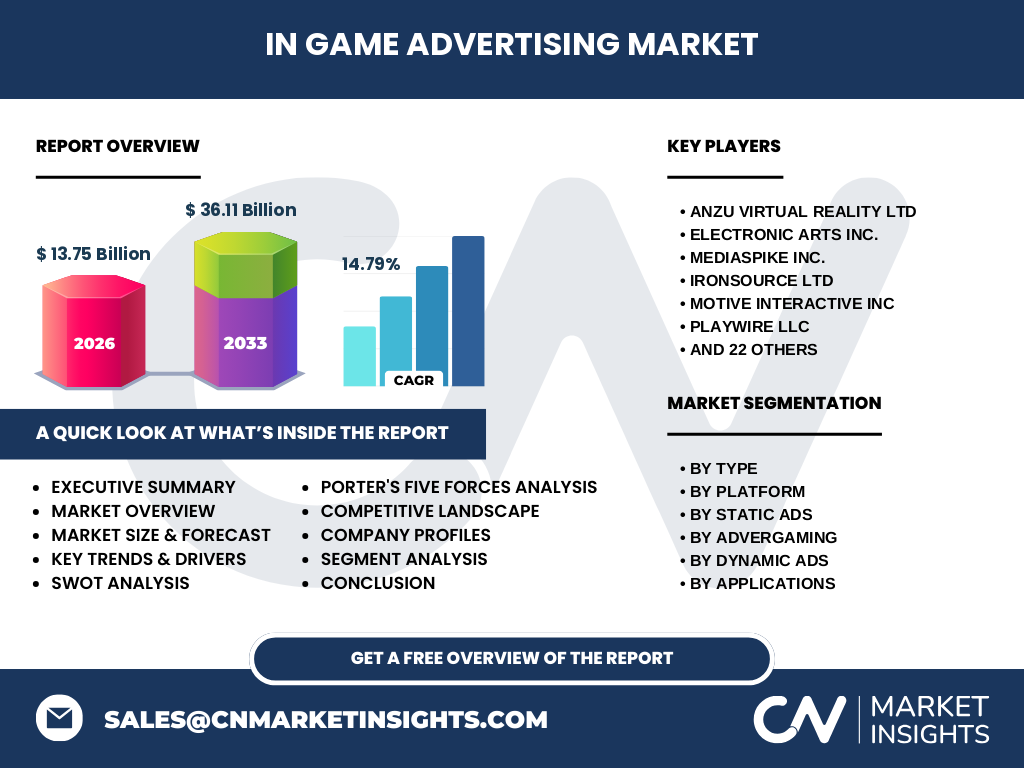
The In-Game Advertising Market functions as a high-velocity digital advertising channel, embedding brand messaging within interactive entertainment. With a 2026 market size of $13.75 Billion, the industry bridges the gap between traditional media and immersive virtual experiences. It encompasses static ad placements, dynamic programmatic inventory, and bespoke advergaming, fundamentally transforming how brands capture highly engaged gamer demographics across mobile, computing, and console environments.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by the transition toward programmatic real-time bidding and the ubiquity of high-performance mobile hardware. While opportunities abound in personalized brand integration, significant challenges persist regarding privacy regulations like GDPR and cross-platform technical standardization. Our research indicates that companies adept at balancing non-intrusive user experiences with scalable monetization are poised to capture the lion's share of industry expansion.
Emerging Patterns in In-Game Advertising Market Trends
The shift toward blended in-game advertising—where ads mirror natural objects like billboards or jerseys—is accelerating. Developers are moving away from disruptive interstitial formats toward natively integrated, value-exchange models. This trend benefits innovators like Anzu Virtual Reality LTD and Adverty AB, who specialize in maintaining gameplay immersion while providing measurable ROI for advertisers looking to reach unreachable audiences.
COVID-19 Impact and Recovery Trajectory
The pandemic catalyzed a permanent shift in consumer digital behavior, effectively pulling forward years of engagement growth. During 2020-2022, gaming saw unprecedented traffic surges, which forced brands to pivot budgets toward in-game inventory. The post-pandemic recovery is now defined by stabilized, long-term retention rates, allowing the In-Game Advertising Market to scale sustainably toward its projected $36.11 Billion valuation by 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, featuring a mix of specialized ad-tech firms and publishing giants. Key players like Bidstack LTD and ironSource LTD lead in programmatic efficiency, while Electronic Arts Inc. and Activision Blizzard Media LTD leverage massive proprietary game ecosystems. Competition is centered on data-driven attribution and the ability to integrate native ad inventory into high-fidelity, AAA production environments.
Executive Summary of the In-Game Advertising Market
The In-Game Advertising Market is undergoing a paradigm shift, transitioning from a niche experimental sector to a core component of the global digital media mix. With a projected CAGR of 14.79% through 2033, the integration of dynamic video and interactive ads is driving unprecedented demand. Success in this landscape necessitates sophisticated tech-first partnerships between brands, game developers, and advanced supply-side platforms.
Projected Market Valuation and Growth Forecast (2027-2033)
The market is set to achieve a massive valuation of $36.11 Billion by 2033, reflecting a consistent CAGR of 14.79%. This growth is underpinned by increased investment in 5G-enabled gaming and the maturation of automated ad-buying technologies. Investors should note that the dynamic ads segment is expected to outperform, as it offers the scalability and real-time measurement that global agencies demand.
Segmentation Analysis: Breaking Down the Industry
We segment the market by Type (Static, Dynamic, Advergaming), Platform (Mobile, Computing, Console), and Application (Online, Standalone). Mobile remains the dominant platform due to its global reach and low barrier to entry, while dynamic real-time bidding is rapidly eroding the share of legacy static billboard placements. Each segment plays a specific role in balancing brand awareness versus performance-driven conversion objectives.
Geographic Performance: Regional Market Analysis
Regional performance is dictated by gaming infrastructure density and local advertising regulations. North America and Europe lead in terms of programmatic ad spend maturity, while Asia-Pacific showcases the highest volume of mobile-first gaming engagement. Our data suggests that developers in emerging markets are increasingly adopting cross-border monetization strategies to capture high-value global brand budgets, significantly boosting regional growth figures.
In-depth Regional Review: Key Market Hotspots
North America remains the strategic hub for ad-tech innovation, driven by major hubs in Silicon Valley. Conversely, the Asia-Pacific region, spearheaded by companies like HotPlay Co. LTD, is optimizing for hyper-localized, ad-supported mobile experiences. European markets show a focus on data privacy compliance, ensuring that as the In-Game Advertising Market scales, user trust and platform transparency remain central to regional growth strategies.
Strategic Positioning of Leading Companies
Leaders like Azerion Group N.V. and Playwire LLC act as essential market aggregators, connecting thousands of publishers with global brands. Meanwhile, tech-focused entrants like AdInMo LTD and Giftgaming LTD prioritize immersive integration, ensuring ads enhance rather than disrupt the user experience. These companies are effectively positioning themselves as gatekeepers of virtual attention in an increasingly fragmented digital advertising space.
Porter's Five Forces Analysis
The threat of new entrants remains moderate, gated by complex integration tech hurdles. Bargaining power of advertisers is high, driving the demand for transparent attribution metrics. Rivalry among competitors is intense, with firms constantly innovating to offer better viewability standards. Threat of substitutes is low, as the immersive nature of in-game media is uniquely resilient compared to traditional 2D display advertising channels.
SWOT Analysis of the In-Game Advertising Market
Strengths: Unmatched audience engagement and high visibility. Weaknesses: Fragmentation across platforms and inconsistent measurement standards. Opportunities: Integration of generative AI for ad personalization and the rise of Metaverse-native brand experiences. Threats: Evolving global privacy regulations and potential user backlash against intrusive, non-contextual ad insertion. Our analysis shows companies must prioritize context-aware placements to mitigate these threats.
Value Chain Analysis: From Development to End-User
The In-Game Advertising Market value chain flows from game engine developers to ad-tech platforms, then to media agencies, and finally to the end-user. Value is created at the intersection of technical integration and data processing. Companies like LoopMe Ltd. and MobileFuse LLC optimize this flow by ensuring that ad assets are delivered efficiently across complex digital infrastructures without sacrificing game performance.
Strategic Investment Insights and High-Potential Areas
Investment should target programmatic infrastructure and AI-powered contextual targeting tools. The Advergaming segment, particularly custom brand development, represents a high-margin area for agencies looking to deepen client relationships. Based on our research, the most lucrative opportunities lie in cross-platform attribution technologies that allow advertisers to track the entire customer journey from in-game impression to final purchase.
Conclusion and Key Takeaways
The In-Game Advertising Market is a high-growth sector set to reach $36.11 Billion by 2033. Success depends on the seamless blend of technology and creativity. Brands that prioritize native ad integrations and programmatic efficiency will dominate. The industry is moving toward a more sophisticated ecosystem where data-backed measurement tools become the standard for every dollar invested in virtual brand environments.
Methodology for Baseline Data Triangulation
Our estimates are triangulated using a rigorous three-pillar approach: primary stakeholder interviews with industry executives, trade registry analysis across key jurisdictions, and secondary macroeconomic indicators. This methodology ensures that our $13.75 Billion baseline figure and 14.79% CAGR are reflective of actual transaction data and market sentiment, minimizing bias and providing a highly reliable predictive model for the 2027-2033 period.
Scope of the Report and Coverage Parameters
This In-Game Advertising Market report covers global trends, focusing on the Mobile, Computing, and Console platforms. We analyze the Static, Dynamic, and Advergaming segments across all major regions. Limitations include the exclusion of non-digital gaming media and specific internal inventory data of closed-system developers, focusing instead on publicly tradable market entities and verifiable third-party ad-tech integration metrics.
Recent Developments: Partnerships and Product Launches
The market is buzzing with strategic consolidation. Recent activity involves major partnerships between WPP Plc. and tech firms like GameInfluencer to scale in-game influencer campaigns. Furthermore, developers are increasingly launching API-first advertising toolkits, as seen in the latest initiatives from Google Inc. and Kargo Global LTD, aiming to simplify inventory management for publishers and ensure high-impact ad delivery.