Market overview and industry significance of the Ferrochrome Market
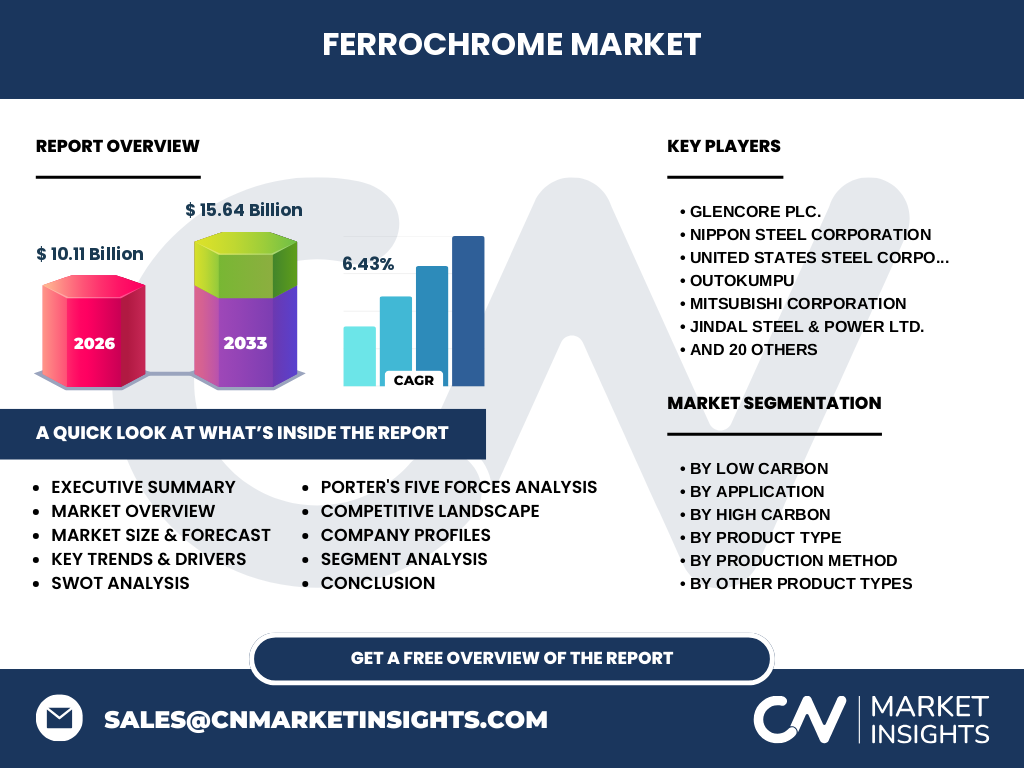
The Ferrochrome Market serves as the backbone of the global metallurgical sector, defined primarily by its role as an essential additive in stainless steel production. With a 2026 valuation of 10.11 Billion, it acts as a critical intermediary in supply chains, bridging raw chromium ore extraction and high-end industrial alloying processes required for corrosion resistance in construction, automotive, and infrastructure.
Structural growth drivers, restraints, and competitive opportunities
Primary growth is fueled by urbanization and the sustained demand for high-durability alloys. However, logistical bottlenecks at ports like Richards Bay and stringent environmental regulations on electric furnace emissions act as significant restraints. Opportunities lie in the transition to low-carbon production methods, where innovators like Glencore PLC and Eurasian Resources Group are optimizing furnace efficiency to meet decarbonization mandates.
Emerging trends and shifting growth patterns
The market is witnessing a distinct pivot toward High Purity Ferrochrome and Micro Carbon Ferrochrome to satisfy sophisticated metallurgy needs. We observe a trend of backward integration, where major stainless steel producers are acquiring captive mining assets to hedge against volatile chromite ore prices, fundamentally altering the traditional buyer-supplier power balance globally.
How did the COVID-19 pandemic redefine the recovery trajectory?
The pandemic caused a temporary contraction in 2020 due to mine shutdowns and logistical gridlock. However, the subsequent V-shaped recovery was driven by government infrastructure spending. Our analysis shows that companies like Tata Steel Mining successfully leveraged localized inventory management, allowing for a robust rebound that positioned the industry for the projected growth toward 15.64 Billion by 2033.
Competitive landscape and strategic dynamics
The market is highly concentrated, characterized by a mix of massive integrated conglomerates and specialized niche players. China Baowu Steel and Nippon Steel Corporation exert significant downstream influence, while upstream power is held by mining-heavy entities like TNC KAZCHROME JSC. Strategic dynamics are defined by vertical integration to capture margins across the entire stainless steel value chain.
Executive summary: Synthesis of market findings
The Ferrochrome Market is poised for steady expansion, growing at a CAGR of 6.43% through 2033. Our research confirms that while supply-side consolidation is intensifying, the demand side remains sensitive to macroeconomic indicators. Key winners will be those firms capable of balancing high-volume High Carbon Ferrochrome supply with emerging demand for low-carbon, high-purity variants.
Projected growth trajectory from 2027 to 2033
Between 2027 and 2033, the market will scale from current levels to reach a valuation of 15.64 Billion. This trajectory reflects a sustained compound annual growth rate of 6.43%. This growth is contingent on technological advancements in plasma furnace methods, which facilitate higher efficiency and lower energy intensity during the smelting process compared to traditional blast furnace alternatives.
Segmentation analysis by product and application
Segments are broadly divided by carbon content and methodology. Stainless Steel remains the dominant application, consuming the vast majority of High Carbon Ferrochrome output. Meanwhile, specialized segments like Powder Metallurgy and Micro Carbon Ferrochrome are experiencing faster proportional growth as high-tech manufacturing sectors in aerospace and specialized casting demand cleaner, more refined alloying inputs.
Geographic distribution and regional performance
Regional performance is anchored by the Asia-Pacific region, which leads in both production and consumption. Major industrial clusters in China and India command the largest market share. In contrast, Africa remains the essential extraction hub, with players like Tharisa PLC and Samancor Chrome supplying the raw material pipeline that feeds the downstream smelting operations located in high-demand manufacturing zones.
In-depth review of regional market dynamics
China continues to dominate global smelting capacity, whereas South Africa holds the largest chromium reserves. This geographic mismatch creates a critical maritime trade dependency. Our analysis indicates that geopolitical shifts and trade policies from bodies like the WTO are prompting regional producers in India, such as Balasore Alloys, to expand capacity to capture market share from traditional, more centralized hubs.
Company profiles and strategic positioning
Key industry leaders occupy distinct niches: Glencore PLC utilizes its global distribution network to dominate commodity flows, while Outokumpu focuses on downstream value-add within the stainless steel sector. Companies like Singhania International and Visa Steel maintain strategic resilience through localized operational excellence, providing essential supply chain agility that larger, more capital-intensive groups often struggle to replicate in volatile market conditions.
Porter's Five Forces assessment
The threat of substitutes is low due to the unique chemical properties of chromium in steel. However, supplier power is concentrated in a few resource-rich nations, while buyer power is significant among the large-scale, consolidated stainless steel producers. Intense competitive rivalry among established firms keeps margins tight, necessitating continuous innovation in Electric Furnace and Plasma Furnace processing efficiencies.
SWOT analysis of the global sector
Strengths include an established global supply chain and high demand integration. Weaknesses involve heavy reliance on energy-intensive production. Opportunities abound in green hydrogen-based smelting, which could revolutionize carbon footprints. Threats include volatile electricity tariffs and shifting international trade barriers, which require firms to maintain flexible operational architectures to mitigate sudden input cost spikes or regulatory-driven production shutdowns.
Value chain analysis from raw materials to end-users
The value chain originates at the chrome mine, moving through beneficiation and smelting processes using blast or electric furnaces. Once refined into High Carbon or Low Carbon Ferrochrome, it is transported via rail and port to steel mills. Finally, it is integrated into finished stainless steel products for automotive, construction, and consumer goods, capturing value at each transition stage.
Investment insights and strategic recommendations
Strategic investment should target high-purity production lines, as these command premium margins compared to commodity-grade products. Based on our analysis, firms that vertically integrate mining with clean-energy smelting technology will be best positioned to weather future regulatory scrutiny. We recommend monitoring capacity expansion in Southeast Asia as a high-potential area for long-term competitive advantage.
Conclusion and critical takeaways
The Ferrochrome Market is a high-stakes, essential sector that will reach 15.64 Billion by 2033. Success relies on navigating the transition to cleaner production, securing stable access to chromite resources, and optimizing the product mix toward specialty carbon grades. The industry is currently shifting from a pure volume-based game to one defined by efficiency, purity, and environmental compliance.
Methodology for baseline estimate triangulation
Our estimates are triangulated using a three-tier data approach. We synthesize trade registry data from major ports, conduct primary stakeholder interviews with operational executives in the ferroalloy space, and align these findings with macroeconomic indicators from global trade bodies. This multi-dimensional methodology ensures that our 6.43% CAGR forecast reflects both historical throughput and projected industrial capacity expansions.
Scope of the report and coverage parameters
This report covers the global Ferrochrome Market, encompassing product types like High Carbon, Low Carbon, and High Purity variants. The analysis includes regional breakdowns of Africa, Asia-Pacific, and the Americas. Limitations of our scope focus on primary metallurgical and smelting output, excluding downstream scrap recycling markets to ensure data precision and focus on virgin material flow.
Recent developments, announcements, and strategic shifts
Recent developments include major capacity expansion announcements from Tharisa PLC and decarbonization pilot projects from China Baowu Steel. Furthermore, we note strategic partnerships aiming to stabilize the supply of electricity to furnaces in southern Africa, which is a critical development for ensuring uninterrupted supply of standard High Carbon Ferrochrome to the global stainless steel industry.