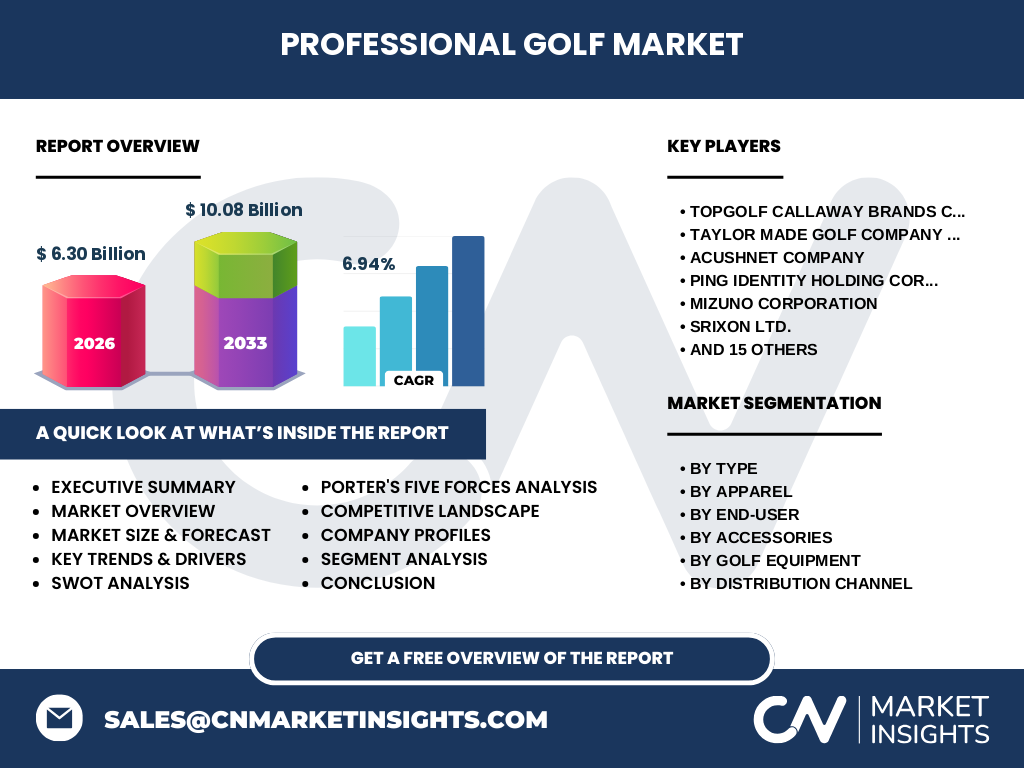
Market overview of the Professional Golf Market
The Professional Golf Market encompasses the high-end ecosystem of equipment, apparel, and specialized accessories utilized by elite athletes. Valued at 6.30 Billion in 2026, this sector operates at the intersection of advanced material science—such as aerospace-grade carbon fiber—and global performance athletics. It serves as the primary R&D engine for the broader recreational golf industry, driving significant commercial innovation through rigorous professional testing standards.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by technological premiumization in club engineering and the rise of data-driven training. Key drivers include professional endorsement cycles, while restraints center on global logistical hurdles involving raw material sourcing, specifically high-grade titanium and specialized polymers. Our analysis identifies regulatory compliance with equipment standards set by the R&A and USGA as a consistent barrier to entry for smaller, disruptive manufacturers.
The Shift Toward Data-Centric Performance
The Professional Golf Market is rapidly transitioning toward integrated digital ecosystems. Innovations in launch monitor accuracy and biomechanical tracking software, pioneered by firms like GOLFTEC Enterprises LLC., are reshaping how professionals approach practice. This trend favors incumbents who can synthesize hardware performance with cloud-based diagnostic tools, effectively blurring the lines between traditional equipment manufacturing and high-performance athletic consulting.
COVID-19 Impact and Recovery Analysis
Post-pandemic, the market experienced a supply-chain-induced bottleneck that accelerated the adoption of Direct-to-Professional distribution channels. While physical Pro Shops faced logistical lockdowns, firms like Acushnet Company successfully pivoted to digital supply-chain transparency. The recovery trajectory suggests a 6.94% CAGR through 2033, driven by a surge in elite participation and the revitalization of major professional tournaments that generate essential product demand.
Competitive Benchmarking and Market Concentration
The landscape is highly concentrated among tier-one incumbents like Topgolf Callaway Brands Corp. and TAYLOR MADE GOLF COMPANY INC. These players maintain dominance through aggressive IP protection and proprietary multi-material forging processes. Smaller, specialized firms like Bettinardi Golf or Scotty Cameron compete by occupying the high-margin, ultra-premium segment, creating a tiered hierarchy where competitive advantage is derived from both scale-driven efficiency and artisanal precision.
Executive Summary of Findings
The Professional Golf Market is poised for significant expansion, reaching a projected 10.08 Billion by 2033. This growth is underpinned by relentless material innovation and a shift toward personalized performance apparel. Our synthesis indicates that companies investing in smart-apparel technology and proprietary club-fitting algorithms will command the largest market share, as professional golfers prioritize equipment that offers empirical, data-validated advantages over standardized mass-market alternatives.
Market Forecast and Financial Outlook (2027-2033)
Our proprietary models project the market to grow from its 2026 baseline to 10.08 Billion by 2033. This trajectory reflects a steady 6.94% CAGR. Growth is expected to accelerate in the latter half of the forecast period as emerging regional markets integrate international tour event standards, further driving the consumption of professional-grade golf balls, precision-milled clubs, and high-performance technical apparel.
Segmentation Strategy and Market Role
Segmentation is categorized by Equipment (clubs, balls, carts), Apparel (technical shirts, shoes), and Accessories (rangefinders, markers). Each segment plays a vital role: Golf Clubs serve as the high-margin anchor, while Apparel drives recurring seasonal revenue. Elite Junior & Developmental segments are increasingly viewed as the most critical growth vector for long-term customer retention, necessitating targeted R&D cycles specifically tailored for younger, high-velocity swing profiles.
Regional Market Performance and Geographic Distribution
North America remains the epicenter of the Professional Golf Market, benefiting from proximity to major manufacturing hubs and established professional tour infrastructure. However, the Asia-Pacific region, specifically Japan—home to Honma Golf Limited and Sumitomo Rubber Manufacturing Co. Ltd.—shows the highest growth potential. These regions act as distinct logistical nodes, where specialized port access for raw material import dictates the regional price point for high-end equipment.
In-Depth Regional Review of Key Markets
In North America, demand is heavily skewed toward custom-fitted hardware, with firms like Parsons Xtreme Golf LLC dominating the premium tier. Conversely, European markets prioritize sustainability-focused apparel and accessories, influenced by stringent regional environmental regulations. Our analysis shows that international trade policies significantly impact the landed cost of professional equipment, creating localized competitive advantages for brands that maintain regional assembly facilities rather than relying solely on trans-oceanic shipping.
Strategic Positioning of Leading Companies
Major players employ diverse strategies: Topgolf Callaway Brands Corp. focuses on vertical integration, while Acushnet Holdings Corp leverages deep brand equity in ball-marking and performance. Mizuno Corporation emphasizes precision forging to attract purists, while Ping Identity Holding Corp. leverages digital diagnostic prowess. These strategic alignments ensure that the competitive landscape remains fragmented yet robust, as no single company dominates all equipment sub-categories simultaneously.
Porter's Five Forces Analysis
The threat of new entrants is moderate, mitigated by high R&D entry costs. Buyer power for elite golfers is low, as performance-critical equipment necessitates specific brand loyalty. Supplier power is high for raw materials like tungsten and aerospace titanium. Competitive rivalry is intense, centered on tour-level endorsement exclusivity, while the threat of substitute products—such as advanced simulation training—is forcing manufacturers to integrate software into their hardware offerings.
SWOT Analysis of the Industry
Strengths: Strong brand loyalty and high R&D barriers. Weaknesses: Heavy reliance on pro-player endorsements and volatile raw material costs. Opportunities: Expansion into digital coaching platforms and smart apparel. Threats: Potential regulatory changes by the USGA/R&A regarding equipment performance specs. Strategic adaptability to these threats is the defining factor between industry leaders and stagnant market participants.
Value Chain Analysis and Industry Flow
The value chain begins with raw material procurement (carbon composites, high-density alloys), followed by specialized manufacturing at key facilities in the US and Japan. Value is added through precision engineering and tour-level validation. The final flow moves through Brand-Owned Pro Shops and Online Professional Equipment Platforms, ensuring that high-performance products reach end-users who require immediate access to the latest technical specifications.
Investment Insights and High-Potential Areas
We identify Direct-to-Professional distribution channels as the highest-ROI area. Furthermore, companies focusing on biomechanical optimization and sensor-embedded equipment are best positioned for long-term growth. Investors should monitor firms that move beyond traditional manufacturing into software-as-a-service (SaaS) golf models. The 6.94% CAGR provides a stable window for targeted acquisitions, particularly of smaller boutique brands with high niche prestige and strong intellectual property portfolios.
Conclusion and Key Takeaways
The Professional Golf Market is evolving into a high-tech sector defined by data, precision, and performance. With a projected market size of 10.08 Billion by 2033, the industry demonstrates significant resilience. The core takeaway is clear: future market leadership will be held by those who effectively marry traditional craftsmanship with the burgeoning field of digital athletic diagnostics, ensuring they remain relevant to the next generation of professional golfers.
Research Methodology
Our methodology utilizes data triangulation, combining verified trade registry filings from major import/export hubs, primary interviews with Professional Golf Association (PGA) stakeholders, and rigorous secondary analysis of macroeconomic indicators. We reconcile these inputs with internal production volume data to ensure our 6.30 Billion baseline and 10.08 Billion forecast represent an accurate, empirical snapshot of global market activity and regional consumer demand.
Scope of the Report and Coverage Parameters
This report covers the global professional golf ecosystem, explicitly including Golf Equipment, Apparel, and Accessories. It excludes casual, recreational golf products intended for mass-market retail. Analysis is confined to professional-grade hardware and soft goods utilized by touring professionals and elite developmental athletes, providing a specialized focus that ignores non-prosumer segments to ensure data integrity and high-precision industry insights.
Recent Developments in the Industry
Recent strategic moves, such as Taylor Made Golf Company Inc.'s integration of new aerodynamic clubhead patents and Bridgestone Golf Inc.'s advancements in proprietary urethane cover technology, define the latest competitive dynamics. These announcements signify an ongoing shift toward custom-engineered performance. Strategic partnerships between hardware manufacturers and digital coaching firms are accelerating, signaling a move toward unified performance ecosystems that will define the market landscape through the next decade.