How do you define the scope and significance of the Omnichannel Retail Software Market?
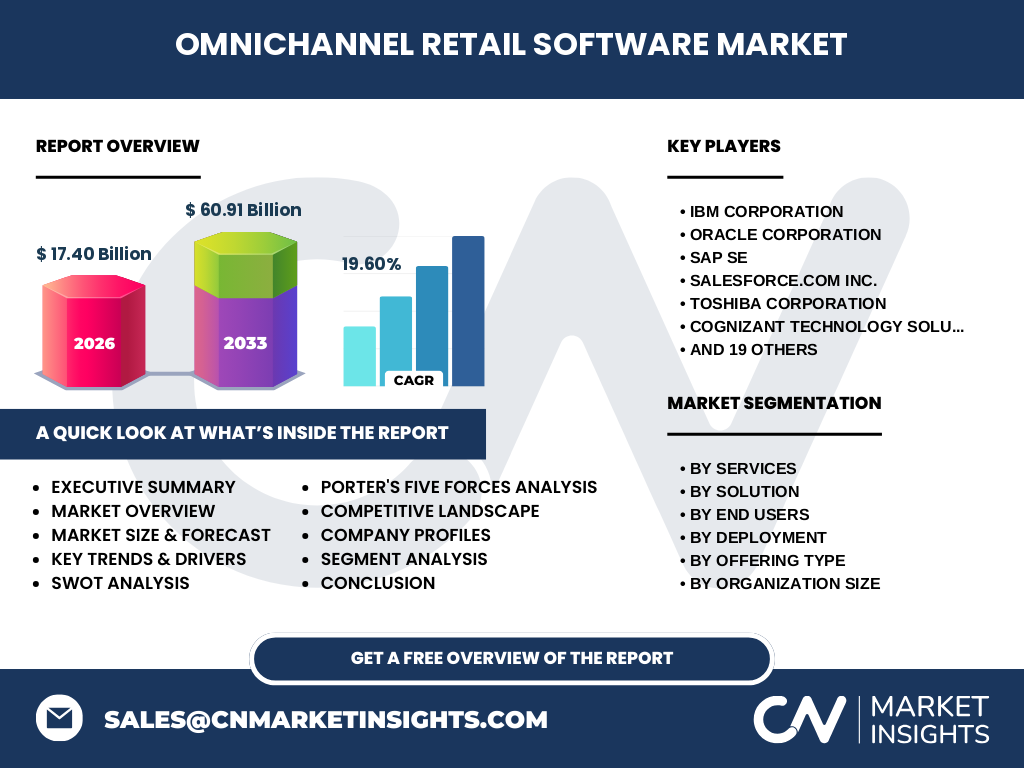
The Omnichannel Retail Software Market encompasses integrated technological ecosystems that unify digital and physical touchpoints. Valued at 17.40 Billion in 2026, this market is critical for retailers navigating complex supply chain nodes and fluctuating consumer demand. By harmonizing inventory management and customer data, these solutions enable frictionless commerce across disparate sales channels, essential for modern retail viability.
What are the structural growth drivers and primary challenges shaping this market?
Growth is primarily driven by the transition toward Cloud-native architectures and the necessity for unified commerce. However, retailers face significant hurdles, including integration complexity with legacy hardware and strict adherence to global data privacy mandates like GDPR and CCPA. Our analysis suggests that providers offering modular, API-first solutions are best positioned to capitalize on these evolving industry demands.
Key emerging trends and growth patterns in the sector
The market is witnessing a profound shift toward headless commerce and AI-driven personalization. Retailers are increasingly prioritizing real-time inventory visibility, which is crucial for managing goods across diverse logistics hubs. As brands integrate Personalization and Recommendation Engines, the synergy between data analytics and customer journey mapping becomes a fundamental differentiator for competitive success in the digital-first era.
How did COVID-19 influence the trajectory of omnichannel software adoption?
The pandemic served as a major catalyst, forcing a rapid, forced digital transformation. It exposed severe weaknesses in fragmented legacy systems, shifting investment focus toward E-commerce Platforms and Order Management Systems (OMS). Post-pandemic, we see a permanent shift where software resilience is no longer optional, driving the robust 19.60% CAGR that defines the current recovery and growth phase.
Competitive benchmarking and strategic market dynamics
The competitive landscape is highly concentrated, featuring giants like IBM, Oracle, SAP, and Salesforce. These incumbents face agile competition from Shopify Plus, VTEX, and Commercetools. Strategic dynamics now center on the M&A activity meant to plug gaps in Supply Chain Management (SCM) capabilities, ensuring these platforms can support the vast scale of modern large-scale enterprise operations.
Executive summary of findings for the Omnichannel Retail Software Market
Our research confirms that the Omnichannel Retail Software Market is on an explosive growth trajectory, projected to reach 60.91 Billion by 2033. The confluence of consumer demand for convenience and the need for operational efficiency is pushing enterprises to abandon silos. Success now requires a multi-layered software strategy involving Integration Services, Cloud Hosting, and sophisticated Data Analytics to drive meaningful revenue growth.
What is the projected market growth from 2027 to 2033?
Based on current adoption metrics, the market is set for sustained expansion, climbing from 17.40 Billion in 2026 to 60.91 Billion by 2033. This represents a significant 19.60% CAGR. This growth is underpinned by the continuous scaling of Mobile Commerce Solutions and the rapid migration of Small and Medium Enterprises from on-premises to cloud-based retail management infrastructure.
Segmentation analysis of service and solution categories
Market segmentation is vital for identifying value. We categorize offerings into Solution-based (POS, OMS, CRM) and Service-based (Consulting, Managed Services). For instance, Inventory Management Systems are central to logistical efficiency, while Consulting Services ensure that global retailers correctly align software implementation with localized regulatory and regional supply chain requirements, ensuring long-term technological ROI.
Geographic distribution and performance across regional markets
Regional performance is dictated by digital infrastructure maturity. North America leads in innovation, while the Asia-Pacific region displays the fastest adoption rates due to mobile-first retail habits. Our data highlights that Logistical hurdles in emerging markets are driving demand for Supply Chain Management (SCM) solutions, creating distinct regional growth patterns for vendors operating across global trade routes.
Detailed examination of key regional market dynamics
In Europe, strict compliance with regional data governance acts as a key barrier to entry, favoring providers like SAP and Adobe Commerce. Conversely, North America emphasizes Personalization and Recommendation Engines, with major players like Salesforce heavily invested in cloud integration. Understanding these regional constraints is critical for any entity aiming to penetrate the fragmented, yet high-potential, global Omnichannel Retail Software Market.
Strategic positioning of leading software providers
Leading players like Oracle and IBM utilize massive ecosystem scale to provide end-to-end management, while innovators like Brightpearl and Aptos Retail target specific niches like inventory-heavy retail. Infosys and Cognizant act as pivotal integration partners, bridging the gap between legacy retail hardware and modern software stacks, proving essential for large-scale enterprise deployment success.
Porter's Five Forces assessment of the competitive climate
The threat of new entrants is moderate, mitigated by high switching costs and the complexity of Integration Services. Competitive rivalry is intense, particularly among major vendors offering Payment Gateway Solutions. Buyer power is increasing, as retailers demand greater flexibility and open-API architectures, putting pressure on established players to accelerate their innovation cycles or risk market share erosion.
SWOT analysis of the current market landscape
Strengths: Advanced AI capabilities and cloud flexibility. Weaknesses: Heavy reliance on complex integration services. Opportunities: Rapid expansion into the Fast Moving Consumer Goods sector. Threats: Evolving cybersecurity threats and stringent global data regulations. Strategic navigation of these factors is essential for vendors seeking long-term growth and stable market presence within the competitive Omnichannel Retail Software Market.
Industry structure and value flow analysis
The value chain begins with Cloud Hosting providers, flows through core Software Solutions (OMS, CRM), and culminates in end-user value via optimized Personalization Engines. Managed Services providers ensure the flow remains uninterrupted, essential for companies dealing with perishable goods in the Fast Moving Consumer Goods sector, where every millisecond of latency can lead to significant logistical and financial loss.
Investment insights and high-potential areas
Investors should focus on firms specializing in Data Analytics Services and Order Management Systems, as these segments underpin the highest degree of operational efficiency. Our research highlights that mid-market enterprise focus—specifically firms helping small and medium enterprises scale—represents a massive, untapped opportunity for providers looking to capture growth beyond the saturated Large Enterprise segment.
Conclusion and key takeaways
The Omnichannel Retail Software Market is fundamentally redefining retail. Reaching 60.91 Billion by 2033, the sector's success is tied to the ability of software to bridge digital and physical worlds. Strategic winners will be those who master cloud integration and data-driven personalization, ensuring retailers can adapt to volatile market conditions with agility and technical precision.
How do we triangulate baseline estimates for our market research?
We utilize a triangulation methodology. We synthesize trade registry data with primary interviews from CTOs and Retail Strategists. These findings are checked against secondary macroeconomic indicators and regional regulatory shifts. By reconciling top-down industry growth projections with bottom-up company-specific performance reports, we ensure a high degree of accuracy and confidence in our 19.60% CAGR forecast.
What is the scope and parameter coverage of this research report?
This report covers the global Omnichannel Retail Software Market, including solutions, services, deployment types, and end-user verticals. It spans 2026 as the baseline, with forecasts extending through 2033. It analyzes companies ranging from Lightspeed Retail to Diebold Nixdorf, providing a comprehensive assessment while noting inherent limitations regarding regional volatility and unforeseen global trade disruptions.
Recent developments, partnerships, and product launches
The market is currently fueled by high-profile strategic partnerships aimed at embedding AI into retail workflows. Recent launches focus on Mobile Commerce Solutions and Automated Supply Chain Management (SCM). The recent entry of BigCommerce and VTEX into key markets signals a shift toward composable commerce, forcing incumbents to accelerate their internal product roadmaps and platform modularity.