Market Overview: Defining the Site Remediation Consulting Services Market
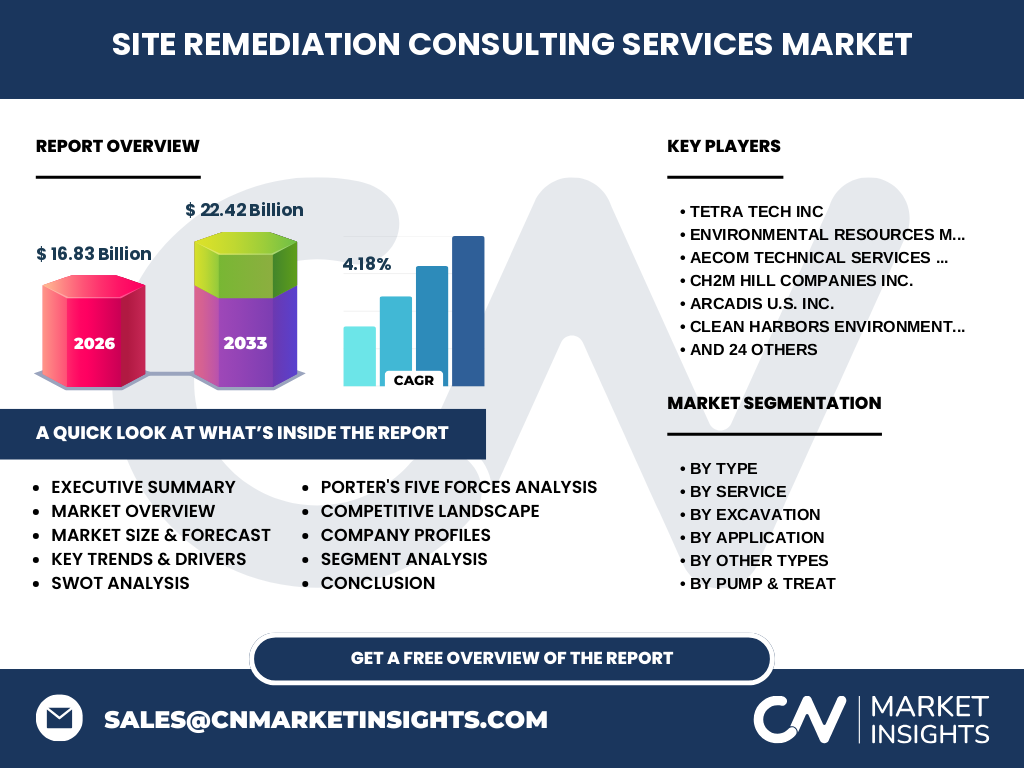
The Site Remediation Consulting Services Market encompasses the specialized technical, engineering, and regulatory advisory services required to restore contaminated land and water. Currently valued at 16.83 Billion in 2026, this sector is critical for managing environmental liabilities for industrial, oil and gas, and mining stakeholders, ensuring compliance with strict regulatory frameworks managed by agencies like the EPA and EU environmental bureaus.
Structural Growth Drivers and Restraints
Growth is primarily propelled by increasing industrial urbanization and stringent global mandates for brownfield redevelopment. Conversely, the market faces significant hurdles, including high capital expenditure requirements for in situ vitrification and complex logistical delays in site access. Opportunities reside in the adoption of sustainable bioremediation techniques, which align with corporate ESG goals, helping firms lower long-term remediation costs while satisfying regulators.
Emerging Trends in Site Remediation Consulting
We are witnessing a pivotal shift toward precision remediation technologies. Specifically, the integration of microbial bioremediation and electrokinetic remediation is gaining momentum over traditional excavation. These methods reduce the logistical burden of transporting hazardous soil, aligning with global net-zero logistics initiatives. Companies like Arcadis and Tetra Tech are increasingly pivoting toward these low-impact, on-site treatment methodologies to maintain a competitive edge.
The Pandemic Influence: COVID-19 Impact and Recovery
The pandemic caused temporary supply chain disruptions and deferred infrastructure projects, leading to a contraction in early 2020. However, the recovery trajectory has been robust, driven by post-COVID stimulus packages focusing on infrastructure renewal. Our analysis indicates that the market successfully pivoted to digital site monitoring, fostering a more resilient operational model that prioritized water remediation services and essential waste disposal site maintenance throughout the subsequent recovery phase.
Competitive Benchmarking and Strategic Dynamics
The market remains highly fragmented yet dominated by major multi-disciplinary firms. Tetra Tech Inc., AECOM, and CH2M Hill command significant market share through broad global footprints. Strategic dynamics are defined by frequent M&A activity, as large players acquire specialized chemical treatment boutique firms to integrate advanced technologies into their portfolios, thereby offering comprehensive end-to-end consulting that mid-tier competitors struggle to replicate.
Executive Summary: Synthesis of Market Outlook
The Site Remediation Consulting Services Market is poised for steady expansion, with a projected value of 22.42 Billion by 2033. Achieving a CAGR of 4.18%, the sector is supported by a growing inventory of contaminated legacy sites in mature manufacturing economies. Success hinges on a firm's ability to navigate complex chemical treatment regulations while leveraging cost-effective onsite treatment technologies to minimize client expenditures.
Market Forecast: The Path to 2033
Projected to grow from 16.83 Billion in 2026 to 22.42 Billion by 2033, the market trajectory is set at a CAGR of 4.18%. This growth is underpinned by the increasing complexity of petrochemical site cleanup requirements and the mandatory decommissioning of older infrastructure. We anticipate the thermal treatment segment will see accelerated demand as industrial standards move toward total destruction of persistent organic pollutants.
Segmentation Analysis: Core Components
The market is segmented by remediation type, including Bioremediation, Pump and Treat, and Excavation. Each segment serves specific hazard profiles; for instance, groundwater extraction systems within the pump and treat category are essential for addressing legacy plumes in manufacturing hubs. Understanding these segments is crucial for analysts evaluating how Clean Harbors or Golder Associates allocate technical assets to specific environmental challenges.
Geographic Distribution and Performance
Regional performance is heavily tied to the density of heavy industry and regulatory maturity. North America continues to lead due to legacy industrial sites, while the Asia-Pacific region shows high growth potential driven by rapid industrialization and increased environmental oversight. Our research indicates that water remediation services are experiencing the highest growth in regions with aging water infrastructure and scarce fresh water resources, such as the Middle East.
In-Depth Regional Review
In North America, the market is characterized by brownfield redevelopment in legacy rust-belt corridors, utilizing stabilization and solidification techniques. Conversely, the European market is heavily influenced by strict EU directives favoring phytoremediation and sustainable site reuse. These distinct regional landscapes force global consulting firms like WSP Global to adapt their service delivery models to fit the localized legislative demands of their respective client bases.
Strategic Positioning of Key Players
Leading players like Jacobs Engineering, Stantec, and SNC-Lavalin differentiate themselves through integrated, turnkey consulting solutions. Their strategic positioning involves high-level technical expertise in plasma arc technology and permeable reactive barriers, which allows them to secure large-scale government contracts. By maintaining strong local relationships with regional regulatory bodies, these firms effectively mitigate the technical risks associated with complex site decommissioning projects.
Porter's Five Forces: Competitive Assessment
The threat of new entrants remains moderate, tempered by the high technical barrier to entry regarding environmental certifications. Supplier power is low, as chemical treatment materials are commodities, while buyer power is high, particularly for large-scale manufacturing clients who demand competitive pricing for soil remediation services. Competitive rivalry is intense, driving consolidation and the pursuit of niche technical dominance in thermal desorption capabilities.
SWOT Analysis: Strategic Outlook
The market's strength lies in its essential, non-discretionary nature. Its weakness is the reliance on volatile capital investment from the oil and gas sector. Opportunities abound in developing nations adopting new environmental standards, whereas the threat includes unpredictable regulatory shifts that may render current remediation strategies obsolete, forcing constant innovation in in situ technical service delivery.
Value Chain Analysis: From Source to Solution
The value chain starts with site assessment and hazardous waste characterization. This flows into the selection of remediation methodologies, such as Excavation and Disposal or Onsite Treatment. The final link involves monitoring and regulatory closure, providing long-term value to end-users like developers and chemical manufacturers. Companies like ERM excel by capturing value across the entire chain, from initial investigation through to final certification.
Investment Insights: Strategic Recommendations
We recommend focusing investments on high-growth niches like monitored natural attenuation (MNA) and advanced thermal desorption. The data suggests that firms specializing in complex, petrochemical-heavy brownfield projects yield higher margins than generalist contractors. Investors should prioritize consulting firms with a robust pipeline in the renewable energy and mining sectors, as these industries face escalating environmental reporting requirements and a mandatory cleanup mandate.
Conclusion and Key Takeaways
The Site Remediation Consulting Services Market is a stable yet evolving industry with a forecast value of 22.42 Billion by 2033. The critical takeaway is that the market is shifting from simple disposal to complex, technical treatment solutions. Future success depends on maintaining regulatory expertise and investing in proprietary bioventing and chemical-enhanced soil washing capabilities, which offer superior long-term site restoration metrics.
Research Methodology: Triangulating Market Data
Our estimates are triangulated using a multi-faceted methodology. We integrate official trade registry data, annual reports from top-tier firms like HDR Inc and Black & Veatch, and primary insights from stakeholder interviews with environmental engineering directors. This is validated against macroeconomic indicators for the construction and manufacturing sectors to ensure our market size projections reflect current, real-world fiscal flows and industry spending patterns.
Scope of the Report: Parameters and Limitations
This report covers the global Site Remediation Consulting Services Market, detailing service types including remediation, soil, and water services. The scope includes in-situ and ex-situ technical applications across major industries. Limitations include inherent variability in local environmental compliance costs, which can influence local market size. The forecast focuses on the 2027 to 2033 period, providing a strategic view of long-term sector trends.
Recent Developments in the Industry
Recent activity highlights a trend of strategic partnerships focused on ESG reporting and carbon sequestration integration. Major players like Terracon and TRC Companies have recently announced moves to expand their digital site mapping capabilities. These developments indicate that the industry is accelerating its transition toward tech-enabled remediation, moving away from labor-intensive traditional models toward data-centric, precision-driven environmental stewardship.