Market Overview: Defining the scope of the Calcium Aluminosilicate Market
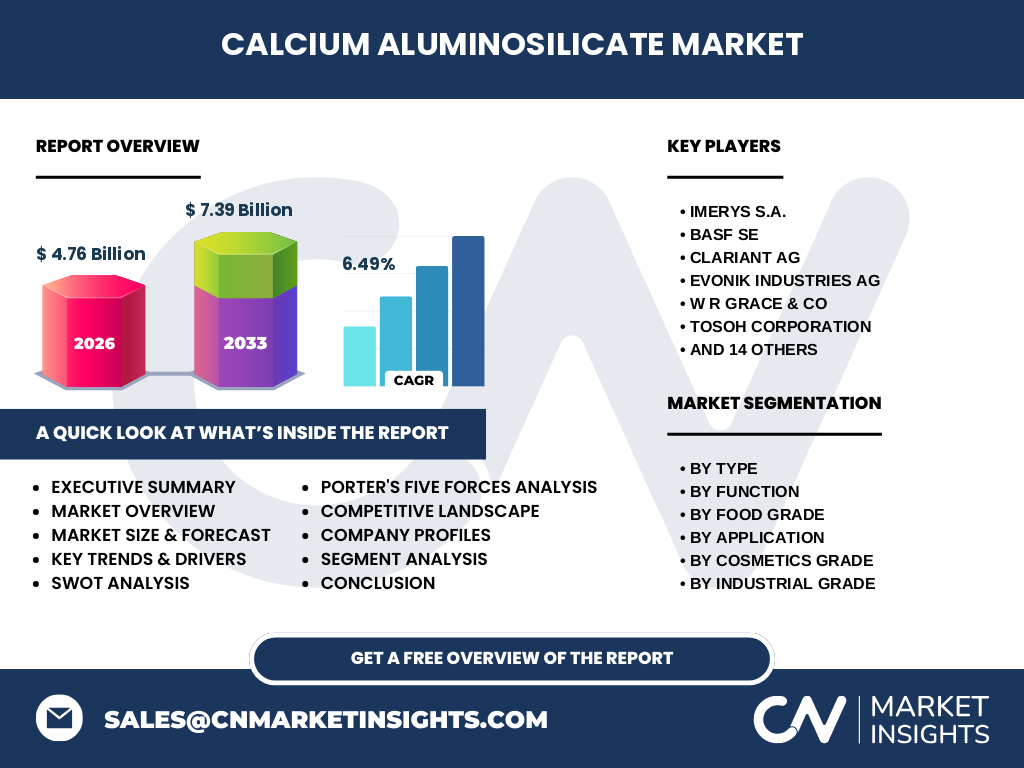
The Calcium Aluminosilicate Market represents a critical sector in specialty chemicals, defined by its versatile use as a performance additive. With a valuation of $4.76 Billion in 2026, the scope spans from essential pharmaceutical excipients to industrial-grade stabilizers. Its significance lies in its unique ion-exchange properties and anti-caking capabilities, which are essential for maintaining material stability across the cosmetics, food, and construction manufacturing industries.
Structural Growth Drivers and Market Constraints
Growth is propelled by rising demand for functional additives in infrastructure and personal care, offset by logistical hurdles in raw material sourcing. The transition toward high-purity minerals acts as a major opportunity for innovators like Imerys S.A. and BASF SE. However, firms face strict compliance mandates from global bodies like the FDA and EFSA, necessitating rigorous quality control to navigate the complex regulatory landscape of the global Calcium Aluminosilicate Market.
Emerging Trends and Strategic Growth Patterns
The shift toward sustainable, bio-based additives is the defining trend in the Calcium Aluminosilicate Market. Manufacturers are prioritizing resource efficiency, aligning with circular economy principles. We observe increased R&D into nanostructured silicates for specialized pharmaceutical drug delivery. This trend favors companies like Clariant AG and Evonik Industries AG, which possess the technical infrastructure to pivot toward high-value, performance-critical applications that demand precise particle morphology and consistent chemical purity.
Assessing the Impact of COVID-19 and the Recovery Trajectory
The pandemic caused temporary supply chain disruptions in the Calcium Aluminosilicate Market, particularly at major transit hubs and logistical nodes. Recovery has been robust, driven by a surge in pharmaceutical manufacturing for tablets and capsules. The industry demonstrated resilience by optimizing inventory cycles and pivoting toward regionalized supply chains, successfully stabilizing growth patterns and returning to an expansionary trajectory that supports our 6.49% CAGR estimate through 2033.
Competitive Benchmarking and Strategic Dynamics
The Calcium Aluminosilicate Market exhibits high concentration, with dominant players like W R Grace & Co, Zeochem AG, and Saint-Gobain S.A. leveraging proprietary mineral processing technology. Competitive dynamics are driven by vertical integration, where companies like SCR Sibelco NV control upstream raw material extraction. Strategic benchmarking reveals a focus on specialty grade differentiation, particularly in the cosmetics and nutraceutical segments, to maintain pricing power against low-cost, industrial-grade commodity competitors.
Executive Summary: Synthesis of Findings
Our research indicates that the Calcium Aluminosilicate Market is poised for substantial growth, reaching $7.39 Billion by 2033 from its 2026 base of $4.76 Billion. This 6.49% CAGR is fueled by the expansion of the pharmaceutical and industrial sectors. Success for stakeholders hinges on technological specialization in anti-caking and adsorption applications. The synthesis of this report suggests that firms investing in high-grade production will lead the market expansion.
Market Forecast: Projections for 2027–2033
We project the Calcium Aluminosilicate Market to achieve a valuation of $7.39 Billion by 2033. This growth is sustained by a 6.49% CAGR throughout the forecast period. We anticipate that pharmaceutical-grade segments will outperform others due to advanced formulation requirements. Investment in manufacturing innovation will be the primary lever for capturing this anticipated market value as global demand for high-performance stabilizers continues to climb steadily.
Segmentation Analysis: Categorizing Industry Value
The market is segmented by Type (Cosmetics, Pharmaceutical, Industrial, Food) and Function (Adsorption, Ion Exchange, Anti-Caking, Stabilization). This structure allows players like Huber Engineered Materials to target specific performance requirements. For instance, the Pharmaceutical Grade segment specifically covers injectable drugs and ointments, necessitating higher purity standards than the Industrial Grade segment, which focuses on cement and coatings. This categorization reflects the diverse technical roles this chemical plays across global supply chains.
Geographic Distribution and Regional Market Performance
The regional landscape of the Calcium Aluminosilicate Market shows significant penetration in Asia-Pacific and North America. Asia-Pacific leads in industrial and manufacturing grade volumes due to localized construction and infrastructure booms. Conversely, the North American and European markets show higher demand for cosmetic and pharmaceutical grade calcium aluminosilicate. This geographic bifurcation allows companies like Tolsa Group and Ashapura Group to customize product offerings to regional regulatory and industrial standards.
In-depth Regional Review: Key Regional Markets
Europe remains a hub for high-end nutraceutical and pharmaceutical innovation, governed by strict REACH regulations. Meanwhile, the Indian and Chinese markets see rapid expansion in the Cement and Ceramics sectors, utilizing vast mineral deposits. Our regional review highlights that companies like Gujarat Mineral Development Corporation benefit from localized access to raw materials, positioning them as essential players in the high-volume industrial segments within these emerging, high-growth, and resource-rich regional markets.
Strategic Positioning of Leading Companies
Leading companies like UBE Corporation, Kao Corporation, and Minerals Technologies Inc. maintain competitive moats through proprietary synthesis methods. Their positioning involves a mix of global distribution reach and specialized application knowledge. For instance, J M Huber Corporation focuses heavily on the Food Grade segment, utilizing its extensive portfolio to ensure stability in complex additive environments, while others prioritize the technical coating sectors to maintain consistent, high-margin, long-term contractual revenue.
Porter's Five Forces Analysis
The Calcium Aluminosilicate Market faces moderate threat of substitutes, yet high barriers to entry exist due to capital-intensive mineral processing. Supplier power is significant where companies control exclusive quarrying rights. Rivalry is intense among top-tier firms like LKAB Minerals and Quarzwerke Group. Buyer power is tempered by the specialized nature of these additives, where product efficacy and safety compliance often override price-sensitive purchasing decisions in the pharmaceutical and food sectors.
SWOT Analysis: Strategic Evaluation
Strengths include strong versatility and essential status in manufacturing; Weaknesses involve high sensitivity to energy costs for processing. Opportunities lie in the Green Chemistry space, as manufacturers seek non-toxic, sustainable alternatives. Threats include unpredictable regulatory shifts and supply chain bottlenecks at global ports. Firms leveraging advanced analytics and efficient logistics can turn these threats into structural advantages within the highly competitive Calcium Aluminosilicate Market landscape.
Value Chain Analysis: From Raw Materials to End-Users
The value chain begins with extraction of mineral ores, followed by high-temperature processing and chemical purification. Distribution is managed via Direct Sales for large-scale pharmaceutical manufacturers or through specialized Distributors for smaller industrial players. This flow ensures that companies like Showa Denko K K can provide a reliable stream of high-purity inputs to end-users, ensuring that the functional integrity of the final product remains consistent across the entire chain.
Investment Insights and High-Potential Areas
Investors should prioritize high-purity pharmaceutical grade providers, as these command higher margins and exhibit greater demand resilience. The cosmetics and hair care segments also show significant growth potential for targeted, high-performance aluminosilicates. We recommend focusing on firms that have secured sustainable sourcing agreements, as supply chain stability is a key differentiator in the current market, ensuring long-term profitability and alignment with emerging environmental, social, and governance (ESG) mandates.
Conclusion and Key Takeaways
The Calcium Aluminosilicate Market represents a robust investment and growth area, reaching $7.39 Billion by 2033. Success is driven by the shift toward specialized application grades and regionalized distribution. Stakeholders must emphasize regulatory compliance and high-purity standards. As the industry evolves, the integration of innovative manufacturing processes will remain the key determinant for maintaining competitive leadership in this dynamic and evolving specialty chemical sector.
Research Methodology: How we triangulate data
Our methodology employs triangulation by cross-referencing trade registry data from major global shipping ports with primary stakeholder interviews from C-suite executives at leading firms like Clariant AG and Evonik Industries AG. We integrate this with secondary macroeconomic indicators to produce the 6.49% CAGR estimate. This rigorous, evidence-based approach ensures that our 2027–2033 forecast remains grounded in verifiable market reality and historical trends for the calcium aluminosilicate sector.
Scope of the Report and Coverage Parameters
This report covers the global Calcium Aluminosilicate Market, focusing on four primary grades: Cosmetics, Pharmaceutical, Industrial, and Food. The scope excludes unrefined, low-value construction minerals while focusing on processed, value-added chemical agents. Geographical coverage encompasses all major regional hubs, including North America, Europe, and Asia-Pacific. The analysis is bounded by the 2026-2033 forecast window, providing an expert view into long-term sector trends, strategic developments, and competitive positioning of global players.
Recent Developments: Strategic Moves and Partnerships
Recent developments in the Calcium Aluminosilicate Market indicate a flurry of strategic M&A activities and capacity expansions. Notable announcements include investments by Tosoh Corporation into new purification technologies and partnerships between regional distributors and UBE Corporation to streamline supply lines. These moves highlight the industry’s push toward product differentiation and operational efficiency, aiming to bolster presence in high-growth markets for pharmaceutical and food-grade additives while maintaining technical superiority in global industrial applications.