Market overview of the Oil And Gas Wells Drilling Services Market
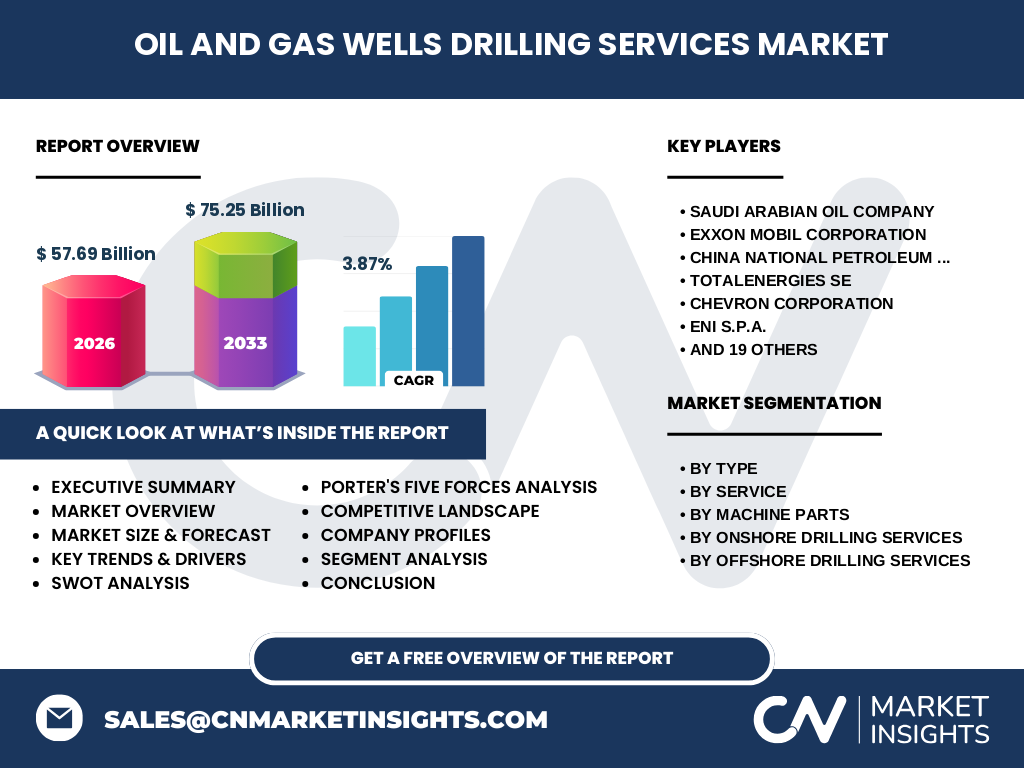
The Oil And Gas Wells Drilling Services Market encompasses the technical and mechanical extraction of hydrocarbons. Valued at 57.69 Billion in 2026, this sector is vital for energy security. It involves complex onshore and offshore operations, utilizing specialized hardware like bits and rigs to access geological reservoirs. Our analysis confirms this market serves as the primary gateway for global energy supply chains and infrastructure stability.
Structural Growth Drivers and Market Constraints
Growth is fueled by rising energy demand, particularly in emerging economies. However, the market faces logistical hurdles and volatile commodity pricing. Opportunities exist in horizontal and directional drilling, which optimize recovery rates. Conversely, strict environmental regulations by agencies like the EPA or EU equivalents create operational pressure. These constraints mandate higher efficiency, favoring firms that master advanced workover and plugging services.
Emerging trends and technological patterns
The shift toward digitalization and automation is redefining the Oil And Gas Wells Drilling Services Market. Companies are increasingly adopting artificial intelligence to improve directional drilling precision. Furthermore, the industry is seeing a pivot toward remote monitoring of mobile offshore drilling units (MODUs), reducing human risk while maximizing productivity. These patterns indicate a clear transition toward efficiency-centric extraction models rather than sheer volume expansion.
COVID-19 impact and the recovery trajectory
The pandemic triggered a sharp contraction in global drilling activity due to suppressed demand. Recovery has been non-linear, with firms like Schlumberger and Halliburton restructuring operations to favor lean efficiency. Our data shows that while 2020 represented a nadir, current capital expenditure cycles have stabilized, leading to a projected market growth trajectory that seeks to bridge the gap toward the 75.25 Billion forecast by 2033.
Competitive Benchmarking and Market Concentration
The landscape is dominated by heavyweights like Saudi Aramco, Exxon Mobil, and China National Petroleum Corporation. Strategic dynamics favor high market concentration in ultra-deep water segments where capital barriers are immense. Meanwhile, service providers such as Baker Hughes and Weatherford International leverage proprietary technology to maintain technical moats, ensuring their relevance despite intense price competition from regional players.
Executive Summary of the Oil And Gas Wells Drilling Services Market
The Oil And Gas Wells Drilling Services Market is poised for steady growth with a CAGR of 3.87%. Reaching 75.25 Billion by 2033, the industry is transitioning from conventional extraction to highly technical horizontal drilling. Success in this landscape requires navigating regulatory headwinds and investing in sustainable, high-precision machine parts like advanced bits and pipes, essential for deep-water and onshore operational excellence.
Market forecast 2027 to 2033
Projected to hit 75.25 Billion by 2033, the market outlook remains bullish. Despite economic cyclicality, demand for drilling services is supported by consistent output requirements from national oil companies. Our modeling suggests a stable CAGR of 3.87%, driven by increased utilization of floating drilling units and the maturation of hydraulic fracturing services, which remain cornerstones for North American and Middle Eastern production sites.
Segmentation analysis of drilling services and machinery
Segments are bifurcated by Onshore and Offshore environments. Onshore drilling focuses on hydraulic fracturing and workover, while offshore operations scale from shallow to ultra-deep water. Critical machinery segments include Rigs, Pipes, Bits, and Reamers. Each category serves a specific geological need, with directional drilling services emerging as a vital sub-segment for maximizing reservoir contact in complex fields, thereby dictating procurement strategies for top-tier exploration firms.
Regional market analysis and geographic distribution
The Middle East remains the undisputed leader in onshore drilling, supported by Saudi Aramco. North America dominates in hydraulic fracturing, while Brazil, driven by Petrobras, leads in deep water and ultra-deep water innovations. European markets, led by TotalEnergies and Eni, focus on sustainability and complex offshore logistics in the North Sea, illustrating a diverse geographic distribution where regional regulatory frameworks significantly shape investment and operational priorities.
In-depth review of key regional drilling hubs
Regional performance is tied to major port infrastructure and geological accessibility. In the US Permian Basin, infrastructure supports rapid scaling of horizontal drilling. Conversely, in the North Sea, Saipem and other specialists operate under intense environmental scrutiny. Our analysis indicates that regions focusing on MODUs and floating drilling units show higher capital resilience, effectively hedging against local market constraints by exporting technical expertise to high-potential basins across the globe.
Company profiles and strategic positioning
Industry leaders demonstrate distinct strategic focus. Transocean and Valaris PLC specialize in deep water assets, while Helmerich & Payne focuses on onshore rig efficiency. China Oilfield Services Limited expands via massive integrated service portfolios. Each player occupies a unique niche—whether through vertical integration of machine parts or service-based delivery—positioning themselves to capture value as the sector moves toward the 75.25 Billion mark by 2033.
Porter's Five Forces analysis for the sector
The Oil And Gas Wells Drilling Services Market exhibits high entry barriers due to massive capital requirements for rigs and drilling units. Supplier power is moderate, as specialized bit and pipe manufacturers control quality. Buyer power is high, as major oil firms negotiate aggressive contracts. Competitive rivalry is intense among global service giants, while the threat of substitution remains tied to long-term energy transition policies.
SWOT analysis of the global drilling services industry
Strengths include technological dominance in horizontal drilling. Weaknesses relate to high exposure to cyclical price volatility. Opportunities lie in digitizing workover and plugging services for life-extension of wells. Threats involve stringent regulatory pressure and the global push toward decarbonization. By leveraging deep water technical expertise, companies can mitigate these threats, turning operational complexity into a competitive advantage that guards against market instability.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material suppliers (steel for pipes and specialized alloys for bits). It progresses to equipment manufacturers like National Oilwell Varco, then to service providers (e.g., Halliburton) who perform the drilling, and finally to end-users—the National Oil Companies and supermajors. This flow is underpinned by logistical precision, moving hardware from manufacturing hubs to extraction sites where efficiency determines the final profit margin.
Investment insights and high-potential areas
We recommend focusing on technology-enabled service providers. High-potential areas include deep water infrastructure and horizontal drilling automation. Companies like Nabors Industries, which integrate digitization into their rigs, offer superior ROI. Investors should favor players with robust balance sheets capable of navigating 75.25 Billion market demands, specifically those servicing the ultra-deep water and hydraulic fracturing segments where high-tech intervention is required for commercial viability.
Conclusion and key takeaways for stakeholders
The Oil And Gas Wells Drilling Services Market is fundamentally evolving. The CAGR of 3.87% reflects a maturing industry embracing digital transformation. Stakeholders should prioritize efficiency-focused service providers and those capable of managing the regulatory complexities of offshore and deep water projects. Sustained investment in specialized machine parts and directional drilling remains the most reliable strategy to capitalize on the industry's trajectory toward 75.25 Billion by 2033.
Research methodology and data triangulation
Our methodology utilizes triangulation: cross-referencing trade registry data with primary stakeholder interviews from field engineers and supply chain directors. We synthesize secondary macroeconomic indicators—including energy price indices and capital expenditure reports—to ensure accuracy. This multi-layered approach allows us to deliver a proprietary baseline for the 2026-2033 period, ensuring our market size estimates remain robust, verifiable, and highly relevant for strategic decision-making in the oil and gas sector.
Scope of the report and coverage parameters
This report covers the global Oil And Gas Wells Drilling Services Market, detailing segments such as onshore, offshore, bits, pipes, and rigs. Geographic coverage includes North America, the Middle East, Europe, and Asia-Pacific. Limitations include excluding upstream exploration seismic activities, focusing strictly on drilling services and mechanical infrastructure. Our scope ensures that B2B buyers receive actionable intelligence regarding the 75.25 Billion opportunity landscape through 2033.
Recent developments and strategic market moves
Recent activity highlights a surge in partnerships between service giants like Baker Hughes and digital firms to optimize directional drilling. Major players like Noble Corporation and Diamond Offshore have engaged in fleet modernization, prioritizing mobile offshore drilling units (MODUs) with reduced carbon footprints. These developments signal a wider industry commitment to technological integration, directly influencing the projected growth toward the 75.25 Billion market size forecasted for 2033.