Market Overview: Defining the Handball Ecosystem
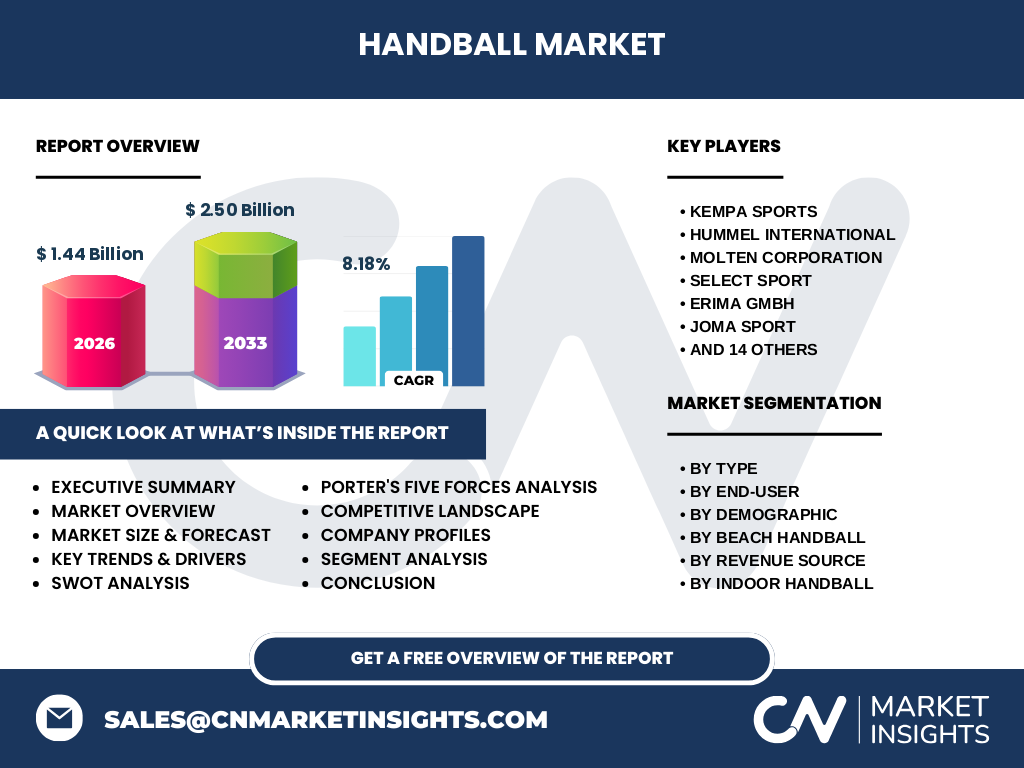
The Handball Market represents a sophisticated global niche valued at 1.44 Billion in 2026. This industry encompasses the manufacturing of technical sports equipment, apparel, and the commercialization of professional leagues. It spans from grassroots Indoor Handball clubs to professional Beach Handball circuits, governed by regional bodies like the IHF and EHF, which maintain standards for synthetic ball pressure and specialized safety gear.
Structural Growth Drivers, Restraints, and Opportunities
The primary growth driver is a 8.18% CAGR fueled by increased investment in grassroots infrastructure. Challenges include localized logistical hurdles involving raw material costs for synthetic ball production. However, massive opportunities exist in digital fan engagement. Companies like Kempa Sports and Select Sport are leveraging these dynamics by optimizing distribution chains to transition from traditional specialty stores to high-margin online direct-to-consumer models.
The Shift Toward Digitalization and Specialized Equipment Trends
We are observing a pivot toward performance-enhancing equipment. Modern players prioritize grip shoes and advanced knee pads designed for high-impact indoor court surfaces. Meanwhile, the emerging popularity of Beach Handball is driving innovation in high-durability saltwater balls and sand-resistant nets, signaling a shift in consumer spending toward segment-specific, climate-adapted gear that ensures product longevity under extreme environmental conditions.
COVID-19 Impact and Recovery Trajectory
The pandemic caused significant disruption in the Handball Market, particularly via the suspension of league play. However, our recovery trajectory analysis shows a robust rebound. With the resumption of professional events, demand for merchandise sales and media rights has surged, as clubs and associations re-establish revenue streams through digital content and spectator return, effectively stabilizing the sector for the 2027 to 2033 forecast period.
Competitive Benchmarking and Market Concentration
The market is characterized by a mix of specialized legacy players like Hummel International and Molten Corporation, and multi-sport giants including Adidas AG and Nike Inc.. Strategic dynamics hinge on brand loyalty within professional associations. Companies are increasingly segmenting their portfolios, with Mizuno Corporation focusing on biomechanical footwear, while Joma Sport captures the mid-market through aggressive team-wear sponsorship deals across European clubs.
Executive Summary: Synthesis of Key Findings
Our research indicates the Handball Market is entering a high-growth phase, projected to hit 2.50 Billion by 2033. This trajectory is supported by a 8.18% CAGR, driven by increased professionalization and digital-first fan experiences. Success in this market requires a dual focus: technical superiority in equipment—specifically synthetic balls and court gear—and deep integration with regional governing bodies to capture sponsorship and media revenue.
Market Forecast 2027-2033
The outlook for the Handball Market is bullish, with valuation climbing from 1.44 Billion in 2026 to a forecast of 2.50 Billion by 2033. This 8.18% CAGR reflects the ongoing expansion of the youth and junior handball segments and a sustained increase in media rights valuations. Investors should look for growth in emerging markets where governing bodies are actively subsidizing new court facilities.
Segmentation Analysis: Covering the Market Spectrum
Segmentation is essential for precision marketing. The market breaks down by: Type (Indoor/Beach), End-User (Clubs, Schools, Professionals), and Demographic (Children to Adults). Specifically, the Indoor Handball segment—comprising synthetic balls, goals, and grip shoes—dominates by volume, while Beach Handball represents a high-growth niche segment, particularly in Southern Europe and South America, requiring distinct logistical supply chains for saltwater-resistant materials.
Geographic Distribution and Performance Metrics
Geographically, Europe remains the dominant powerhouse, accounting for the highest market share due to established league structures and institutional investment. However, we have identified rapid growth in the Asia-Pacific region. Regional performance is highly correlated with the presence of specialty stores and local handball associations. Manufacturers must navigate unique regional import regulations and tax codes to maintain competitive pricing against domestic equipment providers in these high-growth territories.
In-depth Regional Review: A Technical Perspective
The European market maintains a mature, high-value ecosystem with deeply integrated sponsorships. Conversely, the North American and Asian regions are in an expansion phase. Our data suggests that localizing distribution channels is key here; whereas European markets favor established team-wear partnerships, emerging markets are seeing high engagement through online store expansion for entry-level equipment, reflecting a demand for accessible, high-quality gear for schools and junior programs.
Strategic Positioning of Leading Industry Participants
Leading firms like Salming Sports AB and Stanno leverage niche specialization to compete with giants like Puma SE and Asics Corporation. While global conglomerates focus on mass distribution, specialized players capitalize on the technical performance needs of elite clubs, securing lucrative partnerships through high-end grip shoe and knee pad technology that differentiates their product offering in a crowded, competitive retail landscape.
Porter's Five Forces: Competitive Forces Assessment
The Handball Market faces moderate threat of substitutes but high buyer power from large clubs. Barriers to entry are high due to the necessity of IHF certification for competitive gear. Rivalry is intense among top-tier brands like Bison Inc. and Mikasa Corporation, who battle for supply contracts. Suppliers have leverage when providing patented materials, though the shift toward diverse, localized sourcing is mitigating these costs.
SWOT Analysis: Strategic Market View
Strengths include strong brand heritage and high user loyalty in core regions. Weaknesses involve high sensitivity to raw material price volatility for synthetic products. Opportunities lie in the digital monetization of sponsorships and the expansion of the beach segment. Threats comprise strict regulatory hurdles and the potential for market saturation in traditional European hubs, necessitating a move toward emerging geographies to sustain the projected 8.18% CAGR.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with the procurement of high-grade polymers for ball and shoe manufacturing. Logistics move these through major hubs to distributors. The final phase involves the end-user, where professional clubs and associations generate value through ticket sales and sponsorships. Strategic control over the distribution channel, whether through specialty retail or digital storefronts, determines the final margin captured by manufacturers like Jako AG or Macron S.p.A.
Investment Insights and Strategic Recommendations
We recommend focusing capital on high-growth demographic segments, specifically the Youth and Junior markets, which serve as the pipeline for future professional revenue. Strategic partnerships with emerging league organizers offer the best ROI for sponsorship investments. Additionally, digital platform integration—enabling direct sales of merchandise and subscription-based training content—represents the most significant unlocked value in the current market landscape through 2033.
Key Takeaways and Final Conclusion
The Handball Market is poised for significant expansion, reaching 2.50 Billion by 2033. Success hinges on a balanced approach: capitalizing on the popularity of indoor sports while aggressively pursuing the niche, high-growth Beach Handball segment. Brands that align with professional clubs and optimize their supply chains to accommodate both physical retail and global digital distribution will capture the lion's share of this 8.18% CAGR market growth.
Research Methodology and Baseline Triangulation
Our methodology utilizes a triangulation approach, blending primary stakeholder interviews with trade registry data and macro-economic indicators. We cross-reference shipping records from major global ports with retail-level POS data from specialty stores. This multi-layered analysis ensures that our estimates for 2026 and our projections through 2033 are grounded in validated, real-world trade flows and consumer consumption patterns within the professional handball ecosystem.
Scope of the Report and Coverage Parameters
This report covers the global Handball Market, including all segments from professional leagues to amateur schools. It addresses revenue sources like sponsorships, ticket sales, and equipment sales. Limitations include the exclusion of hyper-local informal, unorganized matches, focusing instead on official association-governed activity. The scope is designed to provide actionable intelligence for stakeholders ranging from equipment manufacturers to league investors looking at the 2027-2033 growth window.
Recent Developments and Market Announcements
Recent activity in the Handball Market features intense strategic maneuvering. Major players like Givova and Errea have secured multi-year kit manufacturing deals, signaling a shift toward long-term association stability. Simultaneously, product launches focusing on eco-friendly synthetic materials reflect broader sustainability trends. These partnerships and innovations are critical indicators of the sector's intent to professionalize further and attract premium sponsorship interest as the market grows toward 2.50 Billion.