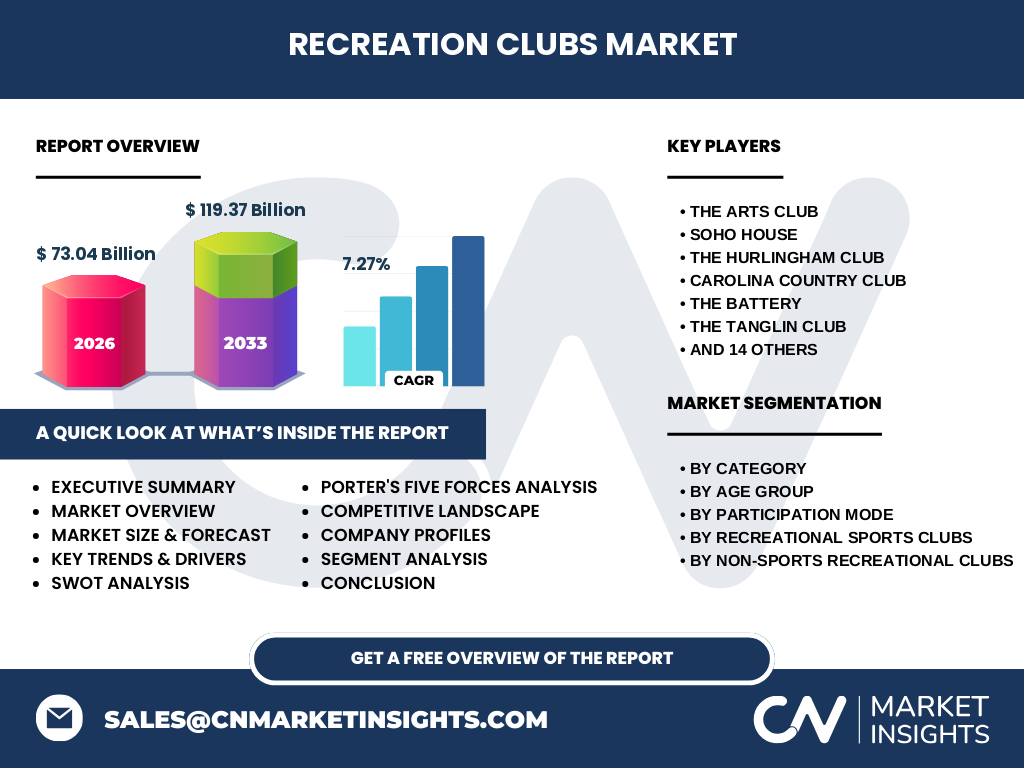
Market overview of the Recreation Clubs Market
The Recreation Clubs Market encompasses a global ecosystem of social, athletic, and cultural hubs. Valued at 73.04 Billion in 2026, this sector facilitates community engagement through organized environments. From elite private institutions like The Hurlingham Club to specialized hobbyist organizations, the scope spans both high-barrier membership facilities and community-driven recreational spaces, serving as a critical pillar for leisure-time infrastructure and social connectivity.
Key drivers and barriers in the Recreation Clubs Market
Our analysis indicates that lifestyle-driven demand for community-based wellness is the primary growth driver. However, the market faces significant regulatory hurdles related to land-use permitting and strict membership zoning. High operational costs for facility maintenance, coupled with shifting disposable income levels, act as key market restraints. Opportunity lies in digital integration, allowing legacy clubs to modernize their legacy infrastructure while maintaining premium, exclusive status.
Emerging trends and growth patterns shaping the industry
A pivot toward hybrid hospitality is redefining how clubs operate. Modern members now demand integrated services, blending fitness, remote work, and social networking. The success of The AllBright in professional networking demonstrates this shift. Furthermore, clubs are prioritizing sustainable facility management, complying with international environmental standards to reduce their carbon footprint, which is becoming a decisive factor for younger demographics in selecting their memberships.
COVID-19 impact analysis and recovery trajectory
The pandemic caused significant short-term volatility due to forced closures and social distancing mandates. Yet, the recovery trajectory has been marked by a surge in demand for outdoor-centric recreational sports clubs like golf and tennis. Leading entities that invested in sanitation technology and air filtration systems rebounded faster, effectively mitigating health safety concerns that initially paralyzed the sector’s high-touch, interpersonal business model.
Competitive landscape and strategic dynamics
The market is characterized by high concentration at the luxury end, dominated by exclusive operators like Soho House and Yellowstone Club. These firms utilize strategic brand exclusivity to command premium fees. Conversely, local institutions like Troydale Recreational Club Ltd focus on community-centric models. The competitive dynamic is shifting from simple amenities to lifestyle curation, where the prestige of the membership list itself defines the brand value.
Executive summary of the Recreation Clubs Market
This report highlights a robust expansion for the Recreation Clubs Market, projecting growth from 73.04 Billion in 2026 to 119.37 Billion by 2033 at a CAGR of 7.27%. Key findings underscore a transition from traditional recreational models toward digitally-enabled, multi-functional spaces. Organizations that prioritize member retention through curated programming are best positioned to capture the shifting preferences of affluent Millennial and Generation Z consumer cohorts.
Market forecast from 2027 to 2033
Projected growth is robust, with the sector expected to reach 119.37 Billion by 2033. This sustained trajectory reflects a 7.27% CAGR, driven by increased urbanization and the growing importance of third-space environments. Our research indicates that institutional capital investment in large-scale recreational real estate will accelerate during the latter half of the forecast period, particularly as clubs modernize their infrastructure to meet evolving member expectations regarding technology and sustainability.
Segmentation analysis of recreational and non-recreational clubs
The market is bifurcated into Recreational Sports Clubs (e.g., swimming, fitness, golf) and Non-Sports Recreational Clubs (e.g., cultural, social, hobby). Sports-based segments drive volume, while cultural clubs command high customer lifetime value. Segmenting by demographic, from Baby Boomers to Generation Z, reveals that while Boomers favor traditional golf and social clubs, Millennials and Gen Z are fueling growth in fitness and hybrid-utility recreational club categories.
Regional market analysis and geographic performance
Geographically, North America and Europe remain the dominant revenue generators due to high disposable income and established club culture. However, Asia-Pacific is experiencing the highest growth velocity, bolstered by rapid urbanization in financial hubs. Localized market constraints, such as real estate availability and stringent zoning laws, dictate the density of facilities in these regions, forcing firms to adopt varied architectural approaches to remain competitive.
In-depth regional review of key markets
In the UK market, private institutions like The Hurlingham Club serve as benchmarks for luxury, while in the United States, clubs such as the New York Yacht Club maintain rigorous institutional standards. Emerging markets in South-East Asia are showing a surge in niche hobby clubs, reflecting a shift toward personalized leisure. Regulatory bodies in these regions are increasingly focusing on building safety, impacting the expansion pace of new recreational developments.
Strategic positioning of leading companies
Major players employ distinct strategies: Soho House leverages a global network model, while the Yacht Club de Monaco focuses on extreme exclusivity. The Battery and CORE Club target the high-net-worth professional segment by blending business connectivity with luxury leisure. This strategic focus on niche demographic targeting allows these companies to maintain price resilience even during broader economic shifts, reinforcing their standing in the global market.
Porter's Five Forces analysis for the sector
Supplier power remains moderate, as real estate and staff are primary inputs. Competitive rivalry is high among top-tier brands competing for a limited pool of affluent members. The threat of substitutes—such as digital health apps or public recreational facilities—is rising. However, the prestige and social networking barriers inherent in private clubs provide a significant moat against new entrants, preserving high margins for established operators.
SWOT analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths: Established brand equity and high member loyalty. Weaknesses: High fixed maintenance costs and operational overheads. Opportunities: Integration of AI-driven concierge services and expansion into emerging markets. Threats: Global economic instability affecting discretionary spending and increased environmental regulation. The industry must navigate these structural challenges by leveraging proprietary membership data to optimize service offerings and streamline facility management, effectively neutralizing potential threats to long-term profitability.
Value chain analysis in the recreation industry
The value chain begins with raw land procurement and construction, moving through architectural design, and culminating in member-facing hospitality services. Logistical hurdles involve managing high-quality food, beverage, and athletic equipment supply chains. Successful operators optimize this flow by centralizing procurement systems, ensuring that the high service standards expected by members are consistent, thereby protecting the brand value from the ground up to the final user experience.
Investment insights and high-potential areas
Investors should prioritize mixed-use recreation assets that combine traditional sports facilities with co-working spaces. High-potential areas include the digitization of member management and investments in sustainable club architecture. Given the 7.27% CAGR, the Recreation Clubs Market offers significant long-term alpha for firms willing to navigate the complexities of property development and regulatory compliance in high-density urban centers.
Conclusion and key takeaways
The Recreation Clubs Market is poised for substantial growth through 2033, driven by a convergence of wellness trends and social connectivity. Success will favor entities that can bridge the gap between legacy exclusivity and modern, tech-integrated experiences. Stakeholders must remain vigilant regarding regulatory environments and shifting demographic preferences, ensuring that their portfolios remain agile enough to adapt to future macroeconomic fluctuations while maintaining their premium market positioning.
Research methodology for the report
Baseline estimates for this report were triangulated using three primary streams: trade registry data from international chambers of commerce, direct primary stakeholder interviews with club managers, and secondary analysis of global macroeconomic indicators. We calibrated these inputs against local regulatory filings to ensure accuracy across disparate geographic markets, providing a rigorous and proprietary foundation for our market sizing and growth projections through 2033.
Scope of the report: Parameters and limitations
This analysis covers the global Recreation Clubs Market, including both sports and non-sports categories. The scope is bounded by private and semi-private member-based clubs. Limitations include potential data variability in emerging regional markets where private club membership data is less transparent. The research assumes constant policy environments regarding land-use zoning, focusing primarily on established market segments and historical performance trends provided for the forecast period.
Recent developments and strategic moves in the market
Recent activity highlights a trend toward cross-market partnerships, with clubs like Soho House expanding their footprint via international collaborative hubs. Furthermore, the launch of new luxury sports facilities in major ports signifies a strategic move to capture the high-net-worth traveler demographic. These developments, alongside increased investment in digital member portals, indicate a industry-wide pivot toward tech-enabled service models to maintain competitive relevance in a post-pandemic economy.