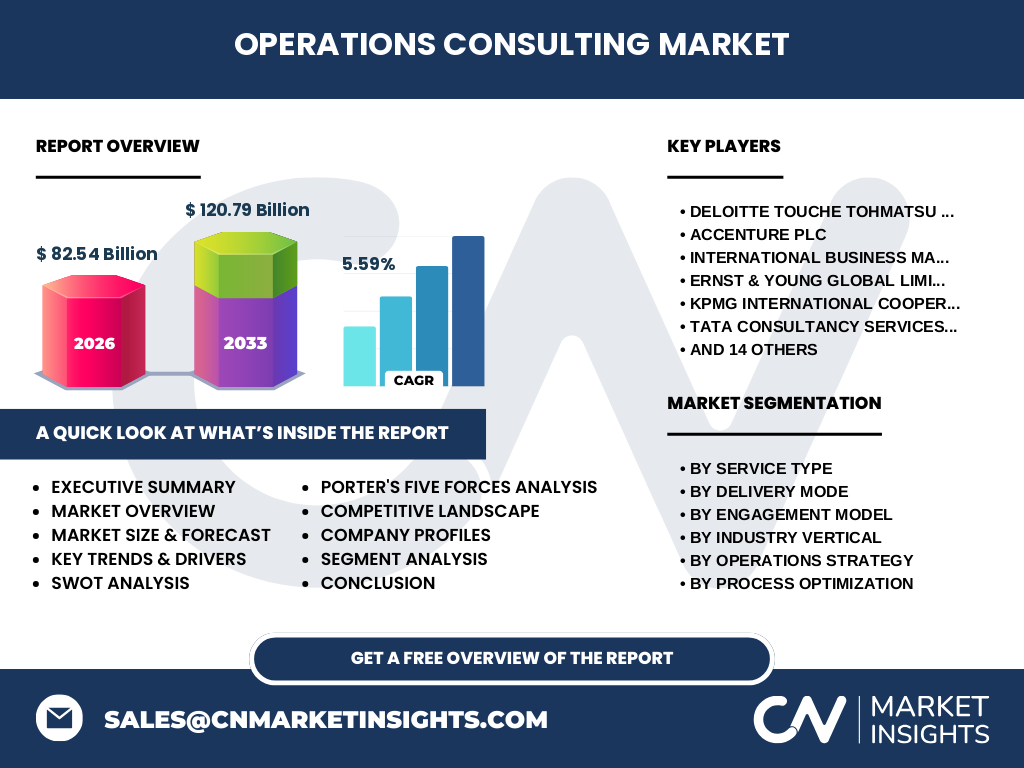
Market overview and industry significance of the Operations Consulting Market
The Operations Consulting Market represents a pivotal strategic pillar for global enterprises, reaching a valuation of 82.54 Billion in 2026. It encompasses high-level advisory services focused on Process Optimization and Supply Chain Management. By aligning internal mechanics with external market demands, these consultants ensure firms navigate volatile environments while maintaining competitive, efficient, and scalable operational models across diverse industry verticals.
Structural growth drivers and market restraints
Growth is primarily fueled by Digital Transformation and the urgent need for Automation And AI Integration. Conversely, the market faces restraints due to high implementation costs and complex regulatory hurdles—particularly concerning GDPR compliance and cross-border data sovereignty. However, the recurring requirement for Cost Reduction And Efficiency Consulting provides a persistent opportunity, ensuring sustained demand even amidst global economic cycles and capital expenditure constraints.
The shift toward integrated technology and process consulting
Our research identifies a decisive shift toward Technology-Enabled Consulting, where Business Process Reengineering is no longer isolated from Data Analytics And Operational Intelligence. Firms are prioritizing ERP Implementation and Workflow Automation to bridge the gap between strategy and execution. This evolution demands consultants who possess both deep operational acumen and technical engineering expertise, a shift clearly benefiting incumbents like Accenture and IBM.
COVID-19 impact analysis and recovery trajectory
The pandemic acted as a forced catalyst for the Operations Consulting Market, exposing systemic fragility in global logistics. Post-pandemic, the trajectory has shifted toward Resilient Supply Chain Design and Hybrid Consulting delivery models. While initial disruption hit project-based work, the recovery has been robust, as companies prioritize Capacity Strategy Planning and Risk Mitigation to prevent future supply chain fractures, stabilizing the industry for long-term growth through 2033.
Competitive benchmarking and strategic dynamics
The market landscape is highly concentrated, with leaders like McKinsey & Company, Bain & Company, and Deloitte leveraging massive intellectual capital. Tata Consultancy Services and Infosys compete aggressively in the IT Enablement segment. Competitive strategy now hinges on integrating Six Sigma methodologies with proprietary AI tools, effectively turning Performance Benchmarking into a continuous, real-time data service rather than a static annual event.
Executive summary of the current market state
The Operations Consulting Market is poised for substantial expansion, forecasted to grow from 82.54 Billion in 2026 to 120.79 Billion by 2033. With a CAGR of 5.59%, the sector is driven by intense pressures on Cost Structure Design and the necessity of Continuous Improvement. Our analysis confirms that firms investing in Digital Enablement will capture the largest share of this anticipated $38.25 billion incremental gain.
Market forecast 2027 to 2033
Projected data indicates a steady trajectory toward 120.79 Billion by 2033, reflecting a healthy CAGR of 5.59%. This growth is underpinned by increased capital allocation toward Global Operations Strategy and the modernization of Legacy Systems. We anticipate the Energy and Utilities sector to be a primary growth engine, as these firms face extreme regulatory pressure to optimize Grid Efficiency and transition toward sustainable Procurement Strategies.
Segmentation analysis by service type and delivery mode
Market segmentation is defined by Service Type (e.g., Process Optimization, Quality and Performance Improvement) and Delivery Mode (On-Site, Remote, Hybrid). Project-Based Consulting remains the bedrock of revenue, though Retainer-Based Consulting is gaining traction. This segmentation allows providers like Capgemini and Cognizant to tailor solutions from Workflow Optimization to End-to-End Process Redesign, capturing value across different client maturity levels.
Regional market analysis and geographic performance
Regional dominance is currently held by North America and Europe, driven by high concentrations of Fortune 500 headquarters and mature manufacturing bases. However, the Asia-Pacific region is accelerating, led by rapid industrialization in Vietnam and India. Localized market constraints, such as logistical bottlenecks at major ports like Singapore or Rotterdam, dictate the specific consulting interventions required, such as Logistics Optimization and Supplier Relationship Management.
In-depth review of key regional dynamics
In North America, the focus rests on Zero-Based Budgeting and Productivity Enhancement to counter inflation. Conversely, the Middle East is witnessing massive demand for Operating Model Design as sovereign wealth funds diversify their energy-reliant economies. European markets are characterized by stringent ESG-related process audits, requiring consultants to specialize in KPI Development and Tracking that meet strict European Union environmental mandates.
Company profiles and strategic positioning
Leading entities like AlixPartners and Kearney are sharpening their focus on distressed operations and Turnaround Consulting. Meanwhile, Genpact and EXL Service utilize their strong operational data heritage to dominate in Automation-Led Efficiency. These firms strategically position themselves as transformation partners, moving beyond simple advisory to become embedded, long-term collaborators in their clients' Workflow Automation Design and Cycle Time Reduction initiatives.
Porter's Five Forces assessment
The Operations Consulting Market exhibits high Competitive Rivalry, as top-tier firms clash for global contracts. Threat of New Entrants remains low due to the requirement for deep industry reputation. However, Bargaining Power of Buyers is rising; clients now demand Value-Based Pricing and specific proof of ROI. Suppliers (niche tech providers) exert moderate pressure, while the Threat of Substitutes—such as internal AI tools—is actively changing how consultants provide value.
SWOT analysis of the Operations Consulting sector
Strengths include robust, high-margin expertise; Weaknesses relate to the inherent scalability issues of human-capital-intensive models. Opportunities lie in emerging markets and Sustainability Consulting, where new regulations require complex Supply Chain Transparency. Threats comprise potential economic recessionary pressure that could trigger widespread project deferrals and the rise of AI-driven DIY consulting platforms that could commoditize standard Cost Reduction services.
Value chain analysis: from raw materials to end-users
The value chain originates with Industry Researchers and Data Analysts providing the intelligence that fuels consulting strategies. Value flows through the design of Procurement Strategies, impacting raw material sourcing, through to the End-to-End Process Redesign within manufacturing facilities. The ultimate end-users—ranging from Retail E-commerce giants to Energy providers—realize value through increased operational throughput, reduced waste, and optimized Resource Allocation.
Strategic investment insights and high-potential areas
Investors should focus on firms heavily invested in Digital Transformation capabilities. High-potential areas include Supply Chain Resilience and Sustainable Operations. Our analysis indicates that consultancies capable of integrating AI-driven Operational Intelligence into traditional Business Process Reengineering will command premium multiples. We recommend targeting players with strong footprints in Healthcare and Life Sciences, a sector facing intense pressure for both Cost Reduction and Quality Management Systems optimization.
Conclusion and key takeaways
The Operations Consulting Market is a vital engine of corporate evolution, forecasted to reach 120.79 Billion by 2033. The success of future operations will be defined by the synthesis of Automation, human-centric change management, and Operational Agility. Companies that successfully pivot toward Tech-Enabled Consulting while maintaining deep industry-specific expertise will dominate the landscape in the coming decade.
Research methodology: how baseline estimates are triangulated
Our estimates are derived through triangulation: first, we ingest Trade Registry Data and annual reports; second, we conduct Primary Stakeholder Interviews with senior partners at leading firms like Roland Berger; third, we correlate these with macroeconomic indicators (e.g., global manufacturing output). This robust methodology ensures that our CAGR of 5.59% is grounded in realistic, verifiable market activity and sector-specific demand signals.
Scope of the report and coverage parameters
This report covers the global Operations Consulting Market, focusing on services provided by firms such as EY, KPMG, and Oliver Wyman. It excludes internal consultancy departments within client companies. The scope spans Project-Based and Retainer-Based engagements across five key verticals: Manufacturing, Healthcare, IT/Telecommunications, Retail/E-commerce, and Energy/Utilities, capturing data from 2026 through the 2033 forecast period.
Recent developments, partnerships, and strategic moves
Recent market activity is defined by Strategic M&A, with major players acquiring niche AI startups to bolster their Data Analytics portfolios. Recent partnerships between consulting leaders and cloud giants like AWS and Microsoft Azure are accelerating the transition to Cloud-Based ERP Implementation. These developments signify a shift where Consulting Firms act as the primary architects of the Modern Digital Enterprise.