What is the industry significance and market scope of the Early Production Facility Market?
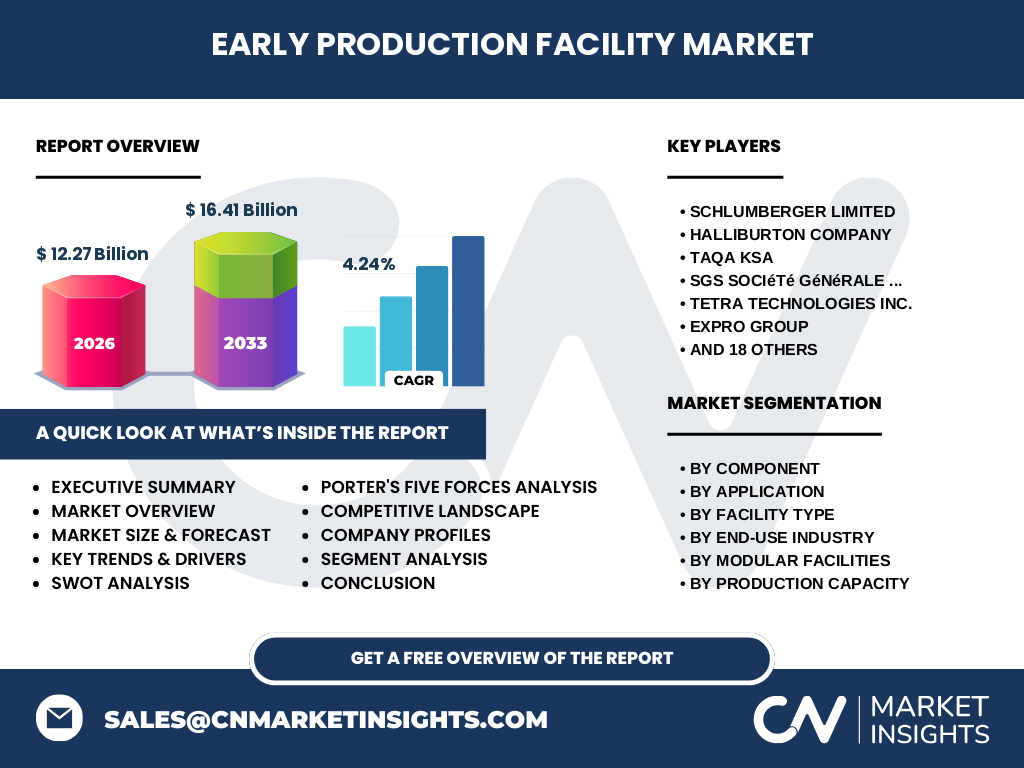
The Early Production Facility (EPF) Market represents a critical segment of upstream oil and gas infrastructure, valued at 12.27 Billion in 2026. These facilities serve as accelerators for cash flow, enabling operators to monetize assets before permanent infrastructure is installed. By providing modular processing capabilities, EPFs effectively bridge the gap between initial exploration success and full-field development, significantly reducing Time-to-First-Oil metrics for global E&P companies.
Structural Growth Drivers and Restraints in the Early Production Facility Market
Primary growth is driven by the urgent need for early capital recovery in high-risk offshore and onshore blocks. However, the market faces regulatory hurdles regarding flare systems and environmental compliance, particularly under IEA carbon reduction mandates. The expansion is further constrained by logistics issues in remote regions, requiring specialized skid-mounted and containerized units that can withstand extreme environmental variables and localized compliance standards.
Emerging Trends in Early Production Facility Market technology
A pivot toward standardized modular units is redefining project economics. Operators increasingly demand customizable modular units that allow for flexible expansion as production profiles change. Innovations in Produced Water Treatment and integrated Gas Sweetening technologies are now standard, helping firms like Roska DBO Inc. and Expro Group meet stringent discharge requirements while optimizing hydrocarbon recovery from marginal or maturing oil fields.
COVID-19 impact and recovery trajectory for the sector
The pandemic caused significant supply chain disruption, delaying critical shipments of Two and Three Phase Separators and other essential components. Recovery has been robust, driven by a strategic focus on resilient supply chains and localized manufacturing. The current trajectory suggests a healthy compound annual growth rate (CAGR) of 4.24%, as the industry prioritizes lean, efficient EPF setups to manage volatile commodity price environments post-2020.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is dominated by tier-one providers including Schlumberger Limited, Halliburton, and Technip Energies. These firms maintain market share by offering end-to-end processing solutions, from Flare Systems to Dew Point Control Units. Smaller, agile players like Pyramid E And C and Specialist Services successfully differentiate by focusing on specialized, high-capacity skid-mounted facilities tailored to complex, site-specific onshore and offshore extraction challenges.
Executive Summary: Synthesis of findings
Our analysis projects the Early Production Facility Market to reach 16.41 Billion by 2033, reflecting a steady 4.24% CAGR. This growth is underpinned by technological advancements in modular facility design and a tactical shift toward high-capacity processing. Strategic investments by players like Worley Limited and Saipem highlight the industry's focus on accelerating revenue realization through rapid, high-integrity temporary infrastructure deployment.
Market Forecast 2027 to 2033
From 2027 to 2033, the market is poised to expand from its current baseline, reaching a total valuation of 16.41 Billion. This trajectory assumes consistent demand for Offshore and Onshore early production assets. Key growth pockets include Medium and High Capacity facilities, as field power generation and integrated processing units become essential for cost-sensitive assets looking to maintain efficiency during the transition to permanent infrastructure.
Segmentation Analysis: Categorization and Roles
Segmentation is categorized by Component, Facility Type, and End-Use Industry. Components like Gas Dehydration and Desalting units are vital for upstream processing quality. Facility types—ranging from Single-Container Units to Permanent Central Processing Facilities—enable operators to choose the right scalability. This granularity allows TETRA Technologies Inc. and Penspen Limited to align specific technical capabilities with the unique reservoir characteristics of their clients' assets.
Geographic Distribution: Regional Market Analysis
The Early Production Facility Market is geographically fragmented, with high demand in the Middle East, West Africa, and the North Sea. Regions with mature assets drive demand for Permanent Tie-In and Export Facilities, while emerging frontier markets favor mobile containerized systems. TAQA KSA and PetroServe International demonstrate strong localized influence, navigating complex port logistics and local content requirements to support major regional energy operators.
In-depth Regional Review
The Middle East remains a powerhouse for High Capacity facilities due to extensive integrated field processing needs. In contrast, North Sea projects lean heavily on Permanent Offshore Early Production Facilities to withstand harsh marine environments. Companies like Technip Energies are central to these regional dynamics, leveraging deepwater engineering expertise to deploy robust, reliable modular facility solutions that meet strict regulatory and safety benchmarks.
Strategic Positioning of Leading Companies
Global leaders like Schlumberger, KBR, and Petrofac position themselves as turnkey EPC partners, focusing on high-end integrated solutions. Conversely, firms like Roska DBO Inc. and Production Solutions Thailand Limited emphasize operational flexibility and maintenance-heavy service models. This strategic divergence ensures that clients can select partners based on the level of technical integration required, whether for standardized modular units or complex, bespoke processing arrangements.
Porter's Five Forces Assessment
The industry exhibits moderate bargaining power of buyers, as operators demand increasingly custom solutions. Threat of new entrants remains low due to high capital expenditure and strict safety certifications. Competitive rivalry is intense among firms like Saipem and Worley, while substitute technologies for early production are limited by the physical requirement to process oil at the wellhead before final transport via existing export infrastructure.
SWOT Analysis: Strategic Outlook
Strengths lie in the agility of modular designs. Weaknesses include the high cost of custom skid-mounted setups. Opportunities are abundant in digitization and automated monitoring of Gas Sweetening and Dew Point units. Threats center on fluctuating OPEC+ production policies and potential shifts in global energy transition incentives, which may force a pivot toward decarbonization-ready EPF infrastructure over traditional fossil fuel-focused configurations.
Value Chain Analysis
The value chain starts with raw material providers (steel, specialty alloys) and moves through component engineering by firms like CECO Environmental. Manufacturers then integrate these into skid-mounted or containerized modules. The final link is the operational service provider, such as Petrofac, which deploys these units to end-users for extraction. Value flows heavily toward those providing integrated, efficient, and reliable processing uptime at the field site.
Investment Insights and High-Potential Areas
Investors should target companies focusing on compact skid-mounted systems and produced water treatment innovations. With a projected market value of 16.41 Billion by 2033, firms that can offer rapid-deployment modular units are well-positioned for higher margins. Specifically, investments in technologies that lower the environmental footprint of Flare Systems will be critical, as ESG compliance becomes a mandatory requirement for securing contracts with major multinational oil and gas firms.
Conclusion and Key Takeaways
The Early Production Facility Market is an essential component of modern upstream energy development, bridging the gap from exploration to production. Key takeaways include a projected 4.24% CAGR, a persistent need for modular scalability, and the critical strategic importance of specialized companies like Halliburton and KBR. Future success depends on technological adaptation, particularly in the realms of automated processing, water treatment, and carbon-efficient infrastructure.
Research Methodology
Our baseline estimates are triangulated through a multi-layer methodology. We synthesize global trade registry data, primary interviews with facility project managers, and macroeconomic energy indicators. This rigorous approach filters out market noise, ensuring our valuation of 12.27 Billion and subsequent projections reflect actual project pipelines, contract awards, and regional capital expenditure cycles across the major oil-producing hubs.
Scope of the Report: Parameters and Limitations
This report covers the Early Production Facility Market globally, analyzing Onshore and Offshore applications across all listed facility types. While it provides deep insights into modular, skid-mounted, and permanent configurations, the scope is limited to upstream infrastructure. It excludes midstream transmission pipelines or downstream refining assets, focusing strictly on field-level processing and stabilization technologies utilized during the initial production phases of hydrocarbon fields.
Recent Developments and Market Announcements
Recent activity highlights a surge in strategic alliances between modular fabricators and service firms. Companies like TETRA Technologies Inc. have announced updates to their Produced Water Treatment capabilities, while others are launching compact, high-capacity skid-mounted systems to capture market share in North America and West Africa. These moves underscore a broader trend: the race to provide faster, more efficient processing to meet the immediate demands of global energy markets.