Market overview of the American Football Betting Market
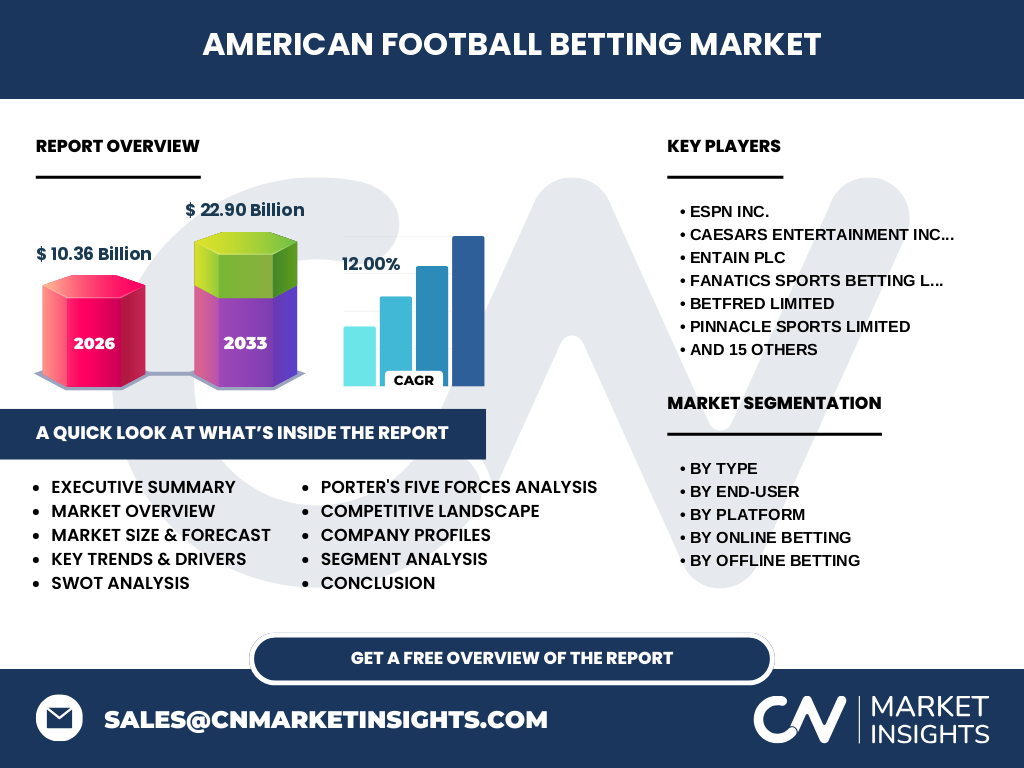
The American Football Betting Market represents a multi-billion dollar ecosystem encompassing wagering on NFL and collegiate games. Valued at 10.36 Billion in 2026, this sector facilitates massive transactional volume through online and offline channels. It serves as a critical growth engine for global gaming operators, integrating complex stochastic modeling with real-time sports data to drive engagement across diverse legal jurisdictions.
Structural Growth Drivers, Restraints, and Opportunities
Growth is propelled by digital transformation and state-level legalization in the U.S. Key restraints include stringent regulatory compliance enforced by bodies like the American Gaming Association. However, the move toward micro-betting provides significant opportunities for incumbents like DraftKings Inc. and FanDuel Group Inc. to deepen customer lifetime value via rapid, play-by-play wagering experiences.
Emerging trends and growth patterns shaping the industry
The industry is shifting toward hyper-personalized UX and integrated media experiences. In-play betting has become the dominant growth vector, allowing platforms to capture high-frequency engagement. Furthermore, we see Fanatics Sports Betting LLC utilizing their massive sports merchandise database to cross-pollinate, creating a unique omnichannel synergy that outpaces traditional bookmaking models in the American Football Betting Market.
Impact of COVID-19 and recovery trajectory
The pandemic acted as an accelerant for digital adoption, forcing a pivot from retail-heavy models to mobile-first interfaces. While brick-and-mortar revenue stalled, the rapid recovery was characterized by a permanent shift to mobile app-based betting. Operators like BetMGM LLC leveraged this period to refine their customer acquisition funnels, resulting in a resilient post-pandemic growth trajectory that has redefined modern consumer habits.
Competitive landscape and strategic dynamics
The landscape is defined by high concentration among Tier-1 operators, including Caesars Entertainment Inc., Entain Plc, and Kindred Group Plc. Strategy involves aggressive marketing spend and technology acquisitions to capture market share. Penn National Gaming Inc. and BetRivers Interactive Gaming LLC utilize distinct loyalty ecosystems to maintain retention against dominant players, fostering a high-intensity battle for consumer attention in this lucrative market.
Executive summary of key findings
Our research identifies the American Football Betting Market as a high-growth sector, projected to reach 22.90 Billion by 2033 with a CAGR of 12.00%. The synthesis of technological innovation and regulatory expansion provides a robust outlook. Investors should note that scalability relies heavily on data-driven pricing engines and the ability to navigate diverse, localized regulatory frameworks across North American markets.
Market forecast from 2027 to 2033
From 2027 to 2033, the market will experience a sustained compound annual growth rate of 12.00%. This trajectory reflects the normalization of sports betting in major jurisdictions. We project market value to expand from its baseline, ultimately reaching 22.90 Billion. This growth is underpinned by advanced algorithmic wagering and the maturation of regional sports media partnerships.
Segmentation analysis breakdown
Segmentation is categorized by Type, End-User, and Platform. Online betting remains the high-growth leader, while Offline betting—comprising retail sportsbooks and kiosks—provides essential brand presence for major operators like Betfred Limited. Recreational bettors drive the bulk of volume, whereas Professional bettors demand sophisticated exchange betting products, necessitating deep market liquidity and precise risk management tools.
Geographic distribution and regional performance
Performance is highest in North American jurisdictions where state-level legislation has been optimized for online expansion. European operators, such as Betsson AB and 888 Holdings Plc, have successfully exported risk management expertise to these developing regions. Disparities in tax rates and licensing requirements between U.S. states remain the primary variable affecting regional profitability and operational footprint.
In-depth review of key regional markets
The U.S. market stands as the premier region, driven by the massive popularity of the NFL. States with favorable tax regimes see higher investment from firms like PointsBet Holdings Limited. Conversely, emerging markets in Latin America and specific segments in Europe provide diversification opportunities for firms like 1X Corp N.V. and Rabona N.V. to hedge against North American regulatory fluctuations.
Strategic positioning of leading companies
Companies are bifurcated into legacy sportsbook operators and digital-native entrants. DraftKings Inc. and FanDuel Group Inc. focus on aggressive user acquisition through innovative gamification. Meanwhile, firms like Pinnacle Sports Limited prioritize high-limit professional volume, maintaining a unique position in the value chain by catering to sophisticated bettors who value price over entertainment-focused product features.
Porter's Five Forces assessment
The American Football Betting Market experiences intense competitive rivalry and moderate threat of new entrants due to high licensing costs. Supplier power, specifically regarding official sports data providers, is high, pressuring operator margins. Buyer power remains significant for high-end players who leverage competitive odds across multiple platforms, forcing operators to differentiate through customer service and seamless technology.
SWOT analysis of the sector
Strengths: Deep fan loyalty and high tech penetration. Weaknesses: Regulatory fragmentation and high tax burdens. Opportunities: Live in-play betting expansion and integration with streaming media giants like ESPN Inc. Threats: Increasing responsible gambling mandates and macroeconomic pressures impacting discretionary spending. Strategic success hinges on navigating these risks while maximizing technological efficiency in the betting process.
Value chain analysis and industry flow
The value chain originates with raw data providers and software developers, flowing through operators, and concluding with end-users. Technology innovators and bookmakers manage risk, while payment processors ensure high-velocity transactions. The chain is highly sensitive to the quality of real-time data feeds, which serve as the primary raw material for establishing accurate, competitive odds for the American Football Betting Market.
Strategic investment insights and high-potential areas
We recommend focusing on B2B software providers that enable micro-betting and automated risk management. High-potential areas include AI-driven churn prediction tools and platforms that leverage social betting features. Investments in companies that possess multi-state licenses while maintaining lean operational structures—similar to the model seen at BONS Ltd. or Megapari Limited—offer the best risk-adjusted returns.
Conclusion and key takeaways
The sector is poised for exponential growth, reaching 22.90 Billion by 2033. Success will be determined by technological differentiation, regulatory agility, and the ability to capture the recreational segment. Stakeholders must prioritize responsible gaming compliance to ensure long-term sustainability while capitalizing on the massive, ongoing shift toward mobile, live-action sports wagering across the North American theater.
Research methodology overview
Our baseline estimates are triangulated through proprietary trade registry data, primary stakeholder interviews with executive leadership, and analysis of macroeconomic indicators. We perform rigorous regression modeling on historical betting volumes and state tax reports. This multi-layered approach ensures that our findings remain grounded in verifiable industry activity, minimizing speculative bias in the 10.36 Billion to 22.90 Billion growth forecast.
Scope and limitations of the report
This report focuses on the American Football Betting Market, covering both online and offline betting types. The scope is limited to legal, regulated markets and does not account for grey market activity. While our 2027–2033 forecast is comprehensive, it remains subject to significant changes in national legislative frameworks, which serve as the primary limiting factor for global market expansion and profitability.
Recent developments and strategic moves
Recent developments show a trend toward media-betting integrations, exemplified by partnerships between gaming firms and major broadcasters. Fanatics Sports Betting LLC and BetMGM LLC continue to refine their omnichannel capabilities through strategic M&A. New product launches focused on real-time player props are becoming standard, reflecting a broader effort by industry players to capture deeper engagement within the American Football Betting Market.