Market overview and industry significance of the Shipping Containers Market
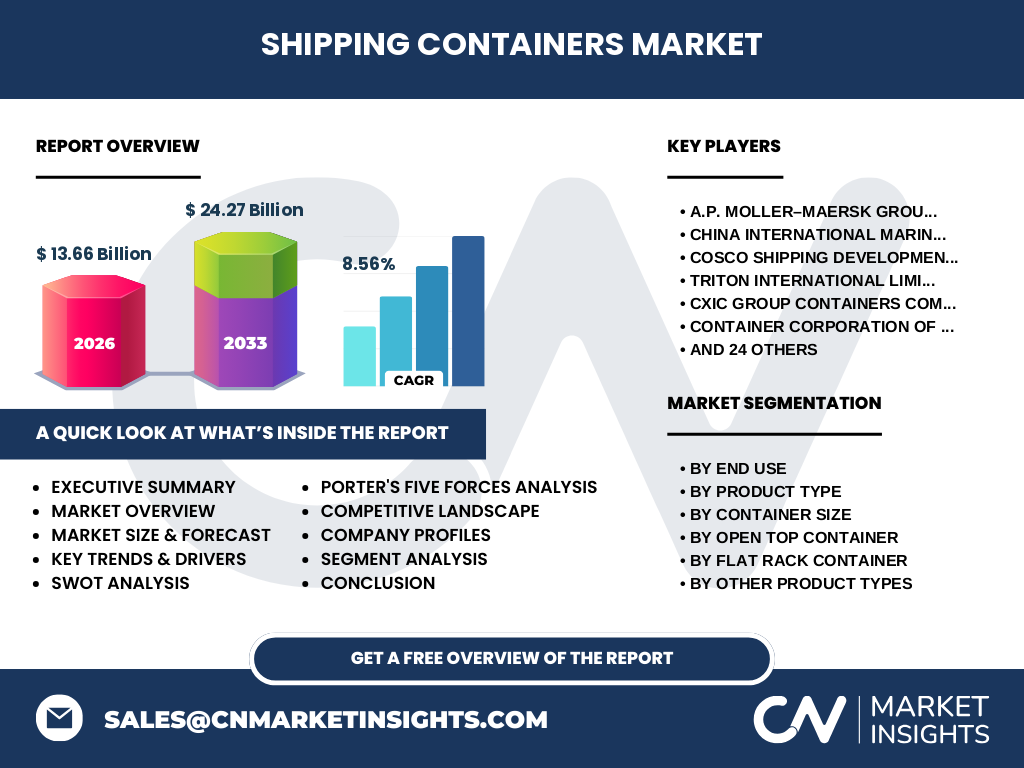
The Shipping Containers Market represents the backbone of global intermodal logistics, encompassing containers designed for durable transit across sea, rail, and road. Valued at 13.66 Billion in 2026, this sector is essential for maintaining global supply chains. Our analysis defines the scope as inclusive of dry storage, refrigerated, and specialized units that facilitate the efficient transport of everything from raw industrial commodities to temperature-sensitive pharmaceuticals.
Structural Growth Drivers, Restraints, and Challenges
Growth is primarily driven by rising e-commerce volumes and the globalization of trade, which necessitates efficient, standardized cargo handling. However, the market faces significant headwinds including volatile steel prices and stringent environmental regulations from the International Maritime Organization (IMO). These hurdles create a strategic pivot point, where companies must balance high-volume production with the demand for sustainable, low-carbon container solutions to remain competitive.
Emerging trends and growth patterns in containerization
A core shift involves the integration of IoT-enabled smart containers, allowing real-time tracking of cargo integrity. We observe a strong growth pattern in high-cube container adoption, as shippers maximize stowage density within standardized port vessel slots. These trends reflect a broader strategic move toward optimizing throughput in high-density corridors, led by tech-forward logistics providers and manufacturers like CIMC.
COVID-19 impact analysis and recovery trajectory
The pandemic caused unprecedented disruption, initially freezing manufacturing before triggering a massive surge in demand for maritime transport. This created a supply-demand imbalance that elevated freight rates. Our research indicates a resilient recovery trajectory, as players like Maersk and Textainer diversified their fleet management strategies, leveraging strategic inventory buffers to stabilize operations against future global logistical shocks.
Competitive landscape and strategic dynamics
The landscape is dominated by heavyweights such as A.P. Moller–Maersk Group, COSCO SHIPPING, and CIMC, creating a high level of market concentration. Strategic dynamics are defined by vertical integration—where shipping lines manufacture their own inventory—and aggressive M&A activity. These giants leverage vast capital reserves to control the production lifecycle, effectively creating high barriers to entry for smaller, specialized niche manufacturers.
Executive summary of the global Shipping Containers Market
Our analysis projects a robust CAGR of 8.56% from 2027 to 2033, leading to a market size of 24.27 Billion. The market is maturing toward specialized and smart container technology. Success for stakeholders in this competitive field hinges on manufacturing efficiency, the ability to navigate fluctuating steel costs, and the strategic deployment of leasing services to balance capital-heavy balance sheets.
Market forecast from 2027 to 2033
We anticipate a valuation surge to 24.27 Billion by 2033, reflecting consistent demand across key global trade routes. This 8.56% CAGR is underpinned by rapid industrialization in developing markets and the expansion of cold-chain infrastructure. We believe companies positioning their production capacity for high-cube and refrigerated containers will capture a disproportionate share of this projected growth through the next decade.
Segmentation analysis of the Shipping Containers Market
Segmentation is critical to understanding value capture. Product-based segments include dry storage, refrigerated, and special-purpose containers. End-use sectors range from food and beverages to vehicle transport. Each segment serves a unique economic role: for instance, high-cube refrigerated units are essential for the healthcare cold-chain, whereas dry storage remains the workhorse for high-volume consumer goods, each requiring distinct production quality standards.
Regional market analysis and geographic performance
Geographically, the Asia-Pacific region remains the dominant production hub, with hubs in China and India (supported by Container Corporation of India Limited) setting the pace for supply chain output. Meanwhile, North America and Europe function as the primary consumer-driven import markets. This regional split forces a reliance on complex, long-haul repositioning logistics, which continues to influence global pricing and fleet utilization rates.
In-depth review of key regional markets
In the Asia-Pacific corridor, manufacturing volume is bolstered by proximity to steel mills. Conversely, the North American market is focusing heavily on intermodal connectivity and the expansion of internal storage solutions, evidenced by companies like Sea Box Inc. adapting to domestic cargo needs. These distinct regional dynamics necessitate a decentralized approach to inventory management, tailored specifically to local infrastructure and regulatory shipping constraints.
Strategic positioning of leading companies
Leading players like Triton International and Textainer focus on asset-heavy leasing models, providing liquidity to shipping lines. Meanwhile, CIMC and CXIC Group leverage manufacturing prowess to drive scale. This bifurcation allows the industry to balance the capital-intensive nature of building containers with the operational agility required to move them across global port systems efficiently and profitably.
Porter's Five Forces analysis of the industry
The industry experiences high rivalry among a handful of global manufacturers. Supplier power is moderate, tied to raw steel market volatility. However, buyer power is significant given the presence of massive shipping conglomerates. New entry is difficult due to the capital intensity of the manufacturing lifecycle, yet technological innovation—such as smart tracking—provides an emerging opportunity for firms to differentiate their service offerings.
SWOT analysis of the Shipping Containers Market
Strengths: Established global standards (ISO) and high operational resilience. Weaknesses: High susceptibility to fluctuating commodity prices. Opportunities: Rapid adoption of smart containers and logistics digitization. Threats: Rising geopolitical tensions affecting trade routes and stringent environmental mandates from regulatory bodies. Understanding these factors is vital for stakeholders to maintain market competitiveness in an evolving, digitally-interconnected global trade environment.
Value chain analysis from raw materials to end-users
The value chain originates with raw material procurement—primarily Corten steel—processed by manufacturers like BSL Containers Ltd. Containers are then sold to leasing firms or shipping lines. The flow reaches the end-user via complex intermodal networks, finally ending in secondary or tertiary storage applications. Optimization at each link, particularly in container repositioning and maintenance, significantly impacts the total cost of ownership for logistics firms.
Investment insights and high-potential areas
High-potential investment is gravitating toward refrigerated and offshore container segments, which command higher margins than standard dry units. We recommend focusing on companies developing eco-friendly, energy-efficient manufacturing processes to mitigate future environmental tax risks. Investing in the smart container ecosystem also provides a hedge against commodity price drops, as these companies transition from simple asset providers to data-driven service partners.
Conclusion and key takeaways
The Shipping Containers Market is set for stable growth, reaching 24.27 Billion by 2033. Success will be determined by a firm's ability to integrate smart tracking technology, optimize global fleet repositioning, and adapt to stricter environmental standards. Investors should monitor leaders like Maersk and CIMC, as their strategic moves will continue to define the standard for logistical excellence in this essential global sector.
Research methodology and triangulation techniques
Our research methodology employs data triangulation by cross-referencing industry trade registries, primary stakeholder interviews with C-suite executives, and secondary macroeconomic indicators from global port authorities. We adjust these baselines against historical growth patterns and current geopolitical trade flow data to ensure our market size estimates and 8.56% CAGR projections are both statistically robust and practically grounded in real-world logistical reality.
Scope of the report coverage and parameters
This report covers the global Shipping Containers Market, including dry, flat rack, refrigerated, and special-purpose units. The analysis spans from 2026 to 2033, focusing on major players like Triton, Textainer, and THIELMANN Group. Limitations include excluding private, non-commercial container manufacturing and focusing exclusively on standardized commercial cargo units to ensure high data integrity and direct relevance to industrial logistics stakeholders.
Recent developments in the Shipping Containers Market
Recent developments highlight a flurry of strategic partnerships aimed at green shipping and container modularity. Notable moves include announcements from Maersk Container Industry regarding sustainable unit production and new technology rollouts for real-time monitoring by industry innovators. These shifts suggest that the market is rapidly moving toward a smarter, more sustainable future, as firms respond to both regulatory pressures and the rising demand for transparency in cargo transit.