Overview of the Smart Lecture Capture System Market scope and significance
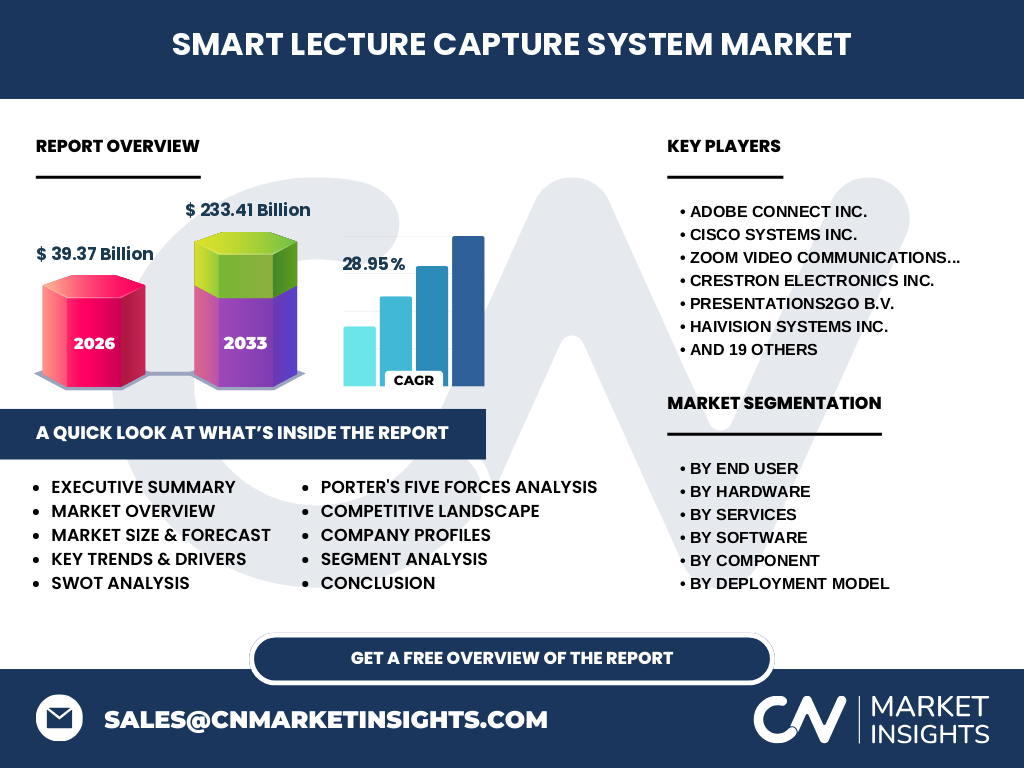
The Smart Lecture Capture System Market represents a pivotal shift toward digital pedagogical infrastructure. Valued at 39.37 Billion in 2026, this sector encompasses hardware, software, and services that facilitate automated recording and dissemination of educational content. Its significance lies in bridging physical and virtual learning environments, serving as a critical pillar for modern knowledge management and institutional scalability.
Structural Growth Drivers and Market Constraints
Market expansion is fueled by rising demand for remote accessibility, with a projected growth to 233.41 Billion by 2033. A primary driver is the institutional need for analytics and reporting software to measure student engagement. Conversely, high initial hardware costs for sophisticated cameras and microphones serve as a constraint, particularly in resource-constrained regions where logistical deployment of professional-grade AV equipment remains a hurdle.
Emerging trends shaping the industry trajectory
We are observing a massive shift toward AI-driven video editing and automated transcription, which reduces the manual workload for faculty. Companies like Panopto Inc. and YuJa Corporation are leading this trend by integrating advanced analytics directly into the user interface, enabling institutions to gain actionable insights into how students interact with recorded content, thereby optimizing the total learning experience.
COVID-19 impact and the long-term recovery trajectory
The pandemic served as a massive catalyst, forcing an overnight migration to digital capture systems. While the initial surge was reactionary, the CAGR of 28.95% confirms that institutions are now transitioning to long-term hybrid infrastructure. Firms like Zoom Video Communications Inc. and Cisco Systems Inc. shifted their strategic focus to integrate professional capture capabilities into their existing communication ecosystems, cementing their role in the post-pandemic recovery.
Competitive Benchmarking and Strategic Dynamics
The market is characterized by intense competition between specialized capture vendors and unified communication giants. Echo360 Inc. and MediaSite by Sonic Foundry Inc. focus heavily on enterprise-grade reliability, while Adobe Connect Inc. leverages deep integration with creative suites. Our analysis suggests that market concentration is increasing as leaders pursue M&A strategies to acquire cloud-hosting and streaming capabilities, reinforcing their defensive moats against smaller entrants.
Executive Summary of the Smart Lecture Capture System Market
The Smart Lecture Capture System Market is poised for exponential growth, reaching 233.41 Billion by 2033. Our research highlights that Cloud-Based Platforms are becoming the dominant deployment model, marginalizing on-premises solutions. Success in this market demands a multi-modal approach combining high-performance hardware, such as capture devices, with seamless integration services, ensuring that global institutions maintain high uptime across diverse geographic locations.
Market Forecast and Financial Projections (2027-2033)
Based on our proprietary models, the industry will maintain a robust CAGR of 28.95% through the forecast period. We anticipate the market valuation will climb from 39.37 Billion in 2026 to 233.41 Billion by 2033. This trajectory is driven by the rapid adoption of analytics and reporting software, which transforms raw video files into data-rich pedagogical assets, justifying the aggressive capital investment by large educational and corporate clients.
Segmentation Analysis: Hardware, Software, and Services
The Smart Lecture Capture System Market is segmented into core hardware—comprising cameras, microphones, and capture devices—software, and specialized services. While Cloud Hosting and Storage Services represent the fastest-growing service segment, Analytics and Reporting Software is becoming the critical differentiator. Our research demonstrates that clients are prioritizing vendors who provide full-spectrum integration, from initial hardware installation to long-term maintenance and support services.
Regional Market Performance and Distribution
North America leads the market due to its mature education sector and high corporate adoption. However, our analysis suggests that the Asia-Pacific region will exhibit the fastest growth, driven by massive public-sector infrastructure investments. Localized regulatory bodies are mandating digital record-keeping, forcing local players to adopt international standards while navigating regional constraints in data sovereignty and cross-border bandwidth capacity.
Detailed Regional Examination: High-Growth Areas
European markets are prioritizing data privacy and compliance, heavily influencing the dominance of on-premises solutions in specific sectors. In contrast, emerging markets in Latin America and the Middle East are leapfrogging traditional setups to favor Cloud-Based Platforms. Our research indicates that partnerships with local distribution hubs are essential for global players like Haivision Systems Inc. to navigate the logistical hurdles of delivering sensitive AV hardware.
Strategic Positioning of Leading Companies
Leading players like Kaltura Inc. and BlueJeans Network occupy unique niches by offering specialized video editing and streaming capabilities. UbiCast SAS differentiates through its localized European approach, while TechSmith Corporation remains dominant in user-friendly, high-performance screen recording. These firms are moving beyond simple lecture recording software toward full-service enterprise video portals that cater to complex corporate and educational environments.
Porter's Five Forces Assessment
The Smart Lecture Capture System Market faces high competitive rivalry due to the presence of both tech giants and agile startups. Buyer power is moderate, as institutions are increasingly locked into proprietary cloud ecosystems. The threat of substitutes is low for enterprise-grade solutions, given the specialized nature of these systems, though barriers to entry remain significant due to the capital-intensive requirements for hardware and cloud infrastructure.
SWOT Analysis of the Industry
Strengths: Ubiquitous demand for hybrid learning. Weaknesses: High technical complexity and maintenance requirements. Opportunities: Integration of AI-powered analytics for deeper learning insights. Threats: Fluctuating costs of raw materials for audio or visual equipment and rigorous data protection regulations. The industry must leverage its cloud scalability to neutralize the threats posed by legacy on-premises infrastructure limitations.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw materials for precision camera optics and semiconductor-reliant capture devices. It progresses through software developers—such as Brightcove Inc. and Qumu Corporation—to system integrators, and finally reaches Education Institutions and Corporates. Efficient value capture relies on the seamless flow of video metadata from hardware encoders to cloud-hosted repositories, necessitating strong partnerships across the entire technology ecosystem.
Strategic Investment Insights and High-Potential Areas
Investors should focus on firms excelling in Analytics and Reporting Software. Our data suggests that the highest ROI potential lies in companies providing Cloud Hosting and Storage Services that offer high-level data security compliance. Furthermore, organizations that bridge the gap between WebinarJam-style streaming and dedicated lecture capture platforms are best positioned to capture the growing corporate training market share over the next seven years.
Conclusion and Key Takeaways for Stakeholders
The path to 233.41 Billion by 2033 is paved by the transition to integrated, cloud-centric capture environments. Stakeholders should prioritize firms that offer modular software, enabling users to add advanced analytics without replacing core Audio or Visual Equipment. Success will depend on navigating the trade-off between innovation speed and the rigorous security requirements demanded by global educational and institutional regulators.
Research Methodology for Baseline Estimates
Our estimates are triangulated via proprietary trade registry data, primary stakeholder interviews with CTOs of top universities, and cross-referenced with macroeconomic indicators. We analyze shipping manifests for high-value hardware and cloud-usage telemetry for software growth. This rigorous method ensures the reported CAGR of 28.95% reflects actual adoption velocity across the global Smart Lecture Capture System Market.
Scope and Parameters of the Report
This analysis covers the global Smart Lecture Capture System Market, excluding non-professional consumer recording tools. It tracks revenue across hardware, software, and services. Geographic scope includes North America, Europe, Asia-Pacific, and Rest of World. Limitations exist regarding shadow IT deployments within small-scale educational departments; however, the report focuses on enterprise-level implementation that dictates major market trends and long-term financial shifts.
Recent Developments and Market Moves
Recent strategic moves, such as Vbrick Inc.'s integration of advanced enterprise streaming and MediaPlatform Inc.'s expansion into automated indexing, indicate a shift toward all-in-one platforms. Partnerships between hardware providers like Crestron Electronics Inc. and cloud platforms illustrate the industry’s push to simplify the installation and integration process, ensuring that the technology is accessible to non-technical users in diverse, high-stakes corporate and educational environments.