Market overview and industry significance of the Alumina Trihydrate Market
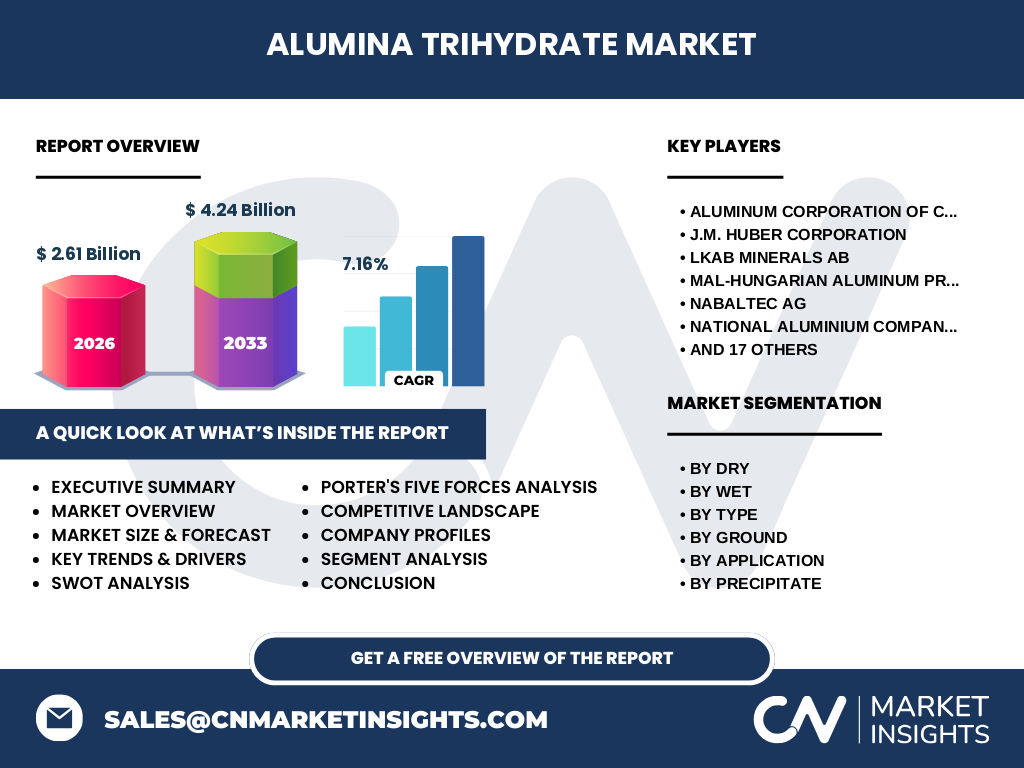
The Alumina Trihydrate (ATH) market serves as a critical pillar in chemical manufacturing, acting primarily as a versatile flame retardant and functional filler. With a 2026 valuation of 2.61 Billion, its significance lies in non-toxic fire suppression for plastics and construction materials. As regulatory bodies enforce stricter building safety codes globally, ATH has transitioned from a commodity mineral to a vital performance additive.
Structural growth drivers, restraints, and strategic opportunities
Primary growth is fueled by the flame retardant sector’s expansion, which is bolstered by eco-friendly mandates replacing halogenated additives. However, logistical hurdles involving the high-volume transport of bulk mineral powders act as a constraint. The key opportunity lies in technical innovation, specifically in surface-treated grades that enhance compatibility with high-performance thermoplastics, providing a significant advantage for specialized producers.
Emerging trends and long-term growth patterns
We are observing a definitive shift toward precipitated grades, which offer higher purity and finer particle size distributions. This trend supports the evolving needs of the paints and coatings industry. Our data suggests a 7.16% CAGR, as manufacturers move away from ground varieties toward gel-derived and co-precipitated alumina trihydrate to achieve superior material properties and regulatory compliance.
COVID-19 impact analysis and recovery trajectory
The pandemic caused temporary supply chain paralysis and demand volatility, particularly in the construction and automotive sectors. However, the Alumina Trihydrate market demonstrated resilience, recovering as green building initiatives accelerated post-pandemic. The current trajectory reflects a V-shaped recovery, with strategic stockpiling by major players like Nabaltec AG and Alteo ensuring supply chain stability during subsequent global economic fluctuations.
Competitive landscape and strategic dynamics
The market is characterized by high concentration, where global titans like J.M. Huber Corporation, Sumitomo Chemical, and Hindalco Industries Ltd. exert significant influence through integrated value chains. Strategic positioning is largely determined by proximity to bauxite sources and the ability to control high-purity precipitate production. Smaller, specialized firms often survive by focusing on niche pharmaceutical-grade or ultra-fine applications.
Executive summary: Synthesis of the Alumina Trihydrate Market
The Alumina Trihydrate Market is poised for substantial growth, rising from 2.61 Billion in 2026 to a forecasted 4.24 Billion by 2033. This expansion is underpinned by robust demand for non-halogenated fire retardants. Strategic focus on sustainable processing and advanced material science will define market leadership, as incumbents adapt to the rising technical requirements of global plastic and construction supply chains.
Market forecast 2027 to 2033
Driven by industrialization in emerging economies and safety regulation tightening, the industry is projected to achieve a CAGR of 7.16%. By 2033, the total market value will reach 4.24 Billion. We anticipate the fastest growth within the precipitate segment, as these products provide the specialized functional characteristics required for next-generation polymer stabilization and complex composite materials.
Segmentation analysis: Breaking down the market
The market is segmented by form—powdered and granulated (dry) versus slurry and suspension (wet). Furthermore, we categorize by type: ground (fine/coarse) and precipitate (gel-derived/co-precipitated). This granularity is critical; for instance, the pharmaceutical segment relies heavily on specific precipitate grades, whereas the plastics sector drives demand for massive volumes of fine-ground ATH, necessitating distinct supply chain and logistical strategies.
Regional performance and geographic distribution
Regional performance is dictated by the density of the building and construction sectors. Asia-Pacific leads in consumption, supported by massive infrastructure investment. Europe maintains a dominant position in high-value precipitated ATH, driven by stringent environmental REACH regulations. North America remains a steady hub for high-performance additives, benefiting from the presence of companies like R.J. Marshall Company and Southern Ionics Incorporated.
In-depth regional review
In Asia-Pacific, growth is exponential, centered around China and India. Conversely, the European market focuses on the value-add segment; manufacturers like Nabaltec AG utilize advanced synthesis to meet European flame retardancy standards. North America exhibits a mature market where consolidation is common, and efficiency in logistics from regional ports is a primary competitive driver for companies like J.M. Huber Corporation.
Company profiles: Strategic positioning
Major players display distinct strategic focuses. Nabaltec AG dominates the high-end flame retardant space, while Hindalco Industries Ltd. leverages its massive alumina refining capacity to control raw material input costs. Jinan Chenxu Chemical Co. Ltd. and Sumitomo Chemical focus on geographic expansion and high-purity scaling. Each participant optimizes their supply chain to mitigate the risks associated with raw bauxite sourcing and regional environmental compliance.
Porter's Five Forces analysis
The Alumina Trihydrate market features moderate-to-high barriers to entry due to high capital intensity and proprietary precipitate production technology. Supplier power is significant for companies reliant on external bauxite. Buyer power remains consolidated within major chemical distributors. Threat of substitution is low, as few minerals offer the specific synergistic flame-retardant properties of ATH at a comparable cost, maintaining high industry attractiveness.
SWOT analysis
Strengths: Ubiquitous, eco-friendly fire retardancy. Weaknesses: Sensitive to energy-intensive production costs and bauxite supply shocks. Opportunities: Expanding into electronic-grade polymers and rising demand for halogen-free compounds. Threats: Fluctuating raw material prices and the threat of legislative shifts affecting mineral extraction operations in key regions like Hungary or China.
Value chain analysis: From raw materials to end-users
The value chain starts with bauxite refining via the Bayer Process, transforming ore into alumina trihydrate. Intermediaries then process this into specialized ground or precipitated forms. These products are distributed to manufacturers in the plastics, paints, and construction sectors. Efficiency at each stage—from kiln operation to final particle sizing—directly impacts the margin profile of major suppliers.
Investment insights and high-potential areas
Investors should prioritize companies investing in surface modification technologies and high-purity precipitated ATH. As the 7.16% CAGR materializes, businesses demonstrating vertical integration and local logistical advantage in emerging Asian hubs offer the highest potential. Reducing the carbon footprint of production through renewable-energy-integrated refining is also a key competitive differentiator for long-term valuation.
Conclusion and key takeaways
The Alumina Trihydrate market is a high-growth sector set to reach 4.24 Billion by 2033. The shift toward precipitate grades and specialized filler applications is undeniable. For stakeholders, success depends on navigating the convergence of environmental policy and manufacturing precision. Companies that balance production scale with advanced chemical engineering will lead the market through the next decade.
Research methodology
Our analysis triangulates data from official trade registries, annual corporate disclosures, and proprietary primary stakeholder interviews with industry executives. We validate these findings against macroeconomic output-per-sector indicators, ensuring that the 2.61 Billion baseline and future projections are grounded in verified industrial capacity reports rather than mere anecdotal trends or speculative estimates.
Scope of the report
This report examines the global Alumina Trihydrate market across all major segments: powdered, granulated, slurry, and suspension. It spans global regions, including North America, Europe, and Asia-Pacific. Limitations exist regarding volatile geopolitical trade tariffs and the exact proprietary R&D spend of private entities, which are modeled based on proxy capital expenditure data from public market peers.
Recent developments and strategic moves
Recent activity highlights a focus on capacity expansion and strategic partnerships. Companies like Sumitomo Chemical have announced optimization projects to stabilize supply. Simultaneously, new product launches in the precipitated category by Nabaltec AG signify a move toward higher-margin, technical-grade applications. These developments collectively support our forecast of 4.24 Billion by 2033 as the industry matures into more complex, high-value technical roles.