What is the strategic scope and definition of the Artificial Intelligence (AI) In Travel Market?
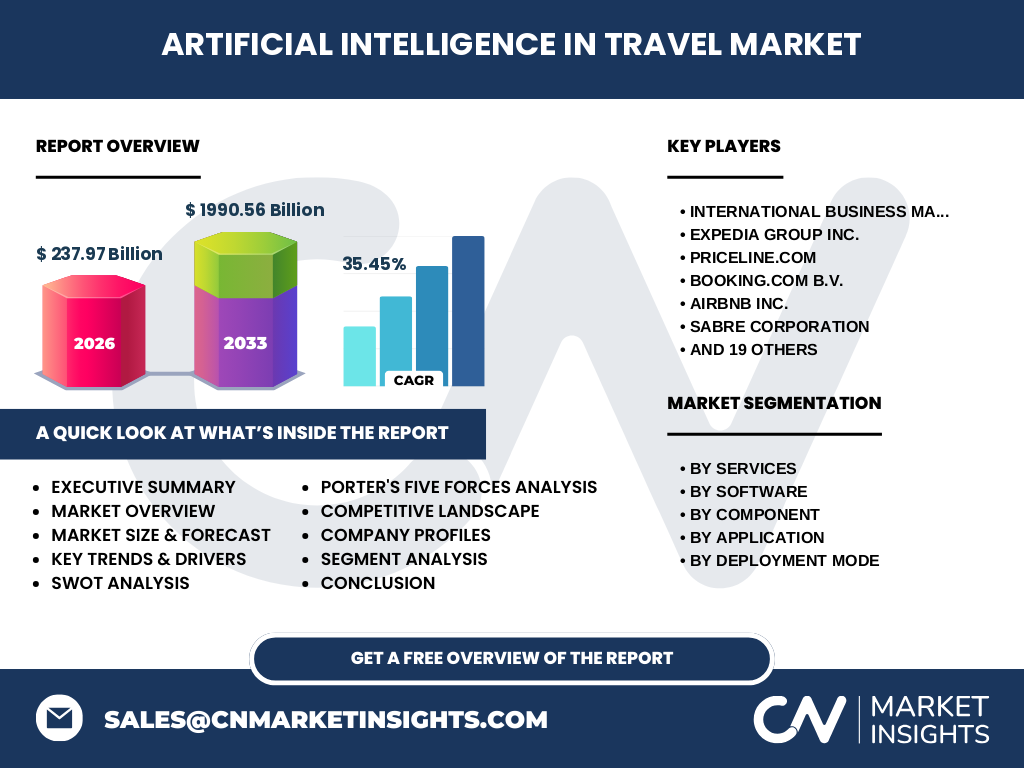
The Artificial Intelligence (AI) In Travel Market represents the integration of advanced algorithms into global tourism infrastructure. Valued at 237.97 Billion in 2026, the market encompasses software, such as personalized recommendation engines, and professional services that optimize travel logistics. It serves as the digital backbone for travel tech giants like Sabre Corporation and Expedia Group Inc., fundamentally redefining how consumers interact with global reservation ecosystems.
Structural Growth Drivers and Market Constraints in AI Travel Solutions
Primary growth is fueled by the 35.45% CAGR, driven by demand for real-time revenue management software. However, the market faces logistical hurdles, including strict data privacy regulations like GDPR and localized compliance requirements. The opportunity lies in security and fraud detection, where companies like Cendyn Group LLC leverage AI to mitigate financial risk within complex cross-border booking pipelines.
Emerging tech trends shaping the industry trajectory
The shift toward hyper-personalization is the standout trend. Innovators like Hopper and TripAdvisor Inc. are deploying AI-driven predictive analytics to capture customer intent. This move away from static search results toward AI-powered travel booking platforms ensures that end-users receive curated itineraries, drastically increasing conversion rates for travel providers by aligning supply-side availability with hyper-specific demand signals.
Post-pandemic recovery and the AI pivot
The COVID-19 pandemic acted as a catalyst for digital transformation. Post-recovery, the industry pivoted toward touchless technology and automated customer service. Companies like Booking.com B.V. accelerated their adoption of cloud-based chatbots to manage volatile cancellation cycles. This structural shift proved that AI-driven operational resilience is no longer optional, solidifying its place as a cornerstone for surviving future global supply chain disruptions.
Competitive landscape and strategic market concentration
Market concentration is high, dominated by conglomerates like Priceline.com and Travelport Worldwide Ltd. These players leverage massive data silos to train proprietary AI models. The competitive benchmarking reveals a clear divide: established OTAs focus on volume-based booking platforms, while specialized firms like OTA Insight Ltd. provide niche data analytics and insights services, effectively carving out dominance in specific vertical segments of the travel value chain.
Executive Summary: High-level synthesis of AI in travel
The Artificial Intelligence (AI) In Travel Market is poised for explosive expansion, reaching a projected 1990.56 Billion by 2033. Our research suggests that integrating cloud-based deployment with AI-powered personalization is the critical success factor. For stakeholders, the mandate is clear: invest in scalable, intelligent infrastructure to capture value from the projected high-growth CAGR of 35.45% while navigating evolving global regulatory landscapes.
Forecast outlook: 2027 to 2033
The trajectory is defined by a significant valuation increase, moving from 237.97 Billion in 2026 to 1990.56 Billion by 2033. This growth reflects the industry’s transition from pilot programs to full-scale enterprise deployment. We anticipate that revenue management software and personalized recommendation engines will lead this surge, as travel providers utilize AI to maximize yield management amidst shifting global consumer sentiment and economic patterns.
Segmentation analysis: Breaking down the market role
The market is bifurcated into Software and Services. Software components include CRM tools and chatbots, which directly manage customer touchpoints. Services provide the implementation layer, such as Consulting and Training, essential for traditional players like Hotelbeds Group to modernize legacy architecture. This synergy between hardware-agnostic software and high-touch support services is critical to maintaining sustained operational efficiency across diverse geographic regions.
Regional market distribution and performance
Performance varies by region, with North America leading in AI-powered booking platform adoption. Europe follows, heavily influenced by regulatory compliance requirements. Meanwhile, the Asia-Pacific region displays the fastest growth due to rapid digitalization in emerging tourism markets. Companies like Agoda Company Pte. Ltd. and MakeMyTrip Limited are optimizing localized digital marketing services to tap into these high-growth populations, creating a fragmented yet highly lucrative global landscape.
In-depth regional review: Localized dynamics
In North America, the focus is on Operations Management AI to handle complex labor logistics. In Europe, the strict EU AI Act dictates the deployment of customer-facing chatbots, forcing innovation toward privacy-compliant models. Conversely, the Middle East and Asia-Pacific corridors are prioritizing cloud-based travel planning tools, leapfrogging legacy systems to build hyper-connected, tech-forward tourism ecosystems that align with modern global travel expectations.
Strategic positioning of leading companies
Major entities like International Business Machines Corporation provide the foundational AI infrastructure, while industry-specific players like Sojern Inc. and Adara Inc. focus on data-driven marketing. SAP Concur dominates the corporate segment, emphasizing efficiency. This strategic positioning allows these companies to capture specific slices of the market, ensuring that AI tools are effectively applied to both leisure-focused travel apps and complex enterprise-level booking systems.
Porter's Five Forces: Assessing competitive intensity
Competition is fierce among existing incumbents like Kayak Software Corporation and Skyscanner Ltd. The threat of new entrants is mitigated by the prohibitive cost of training high-fidelity travel data models. Buyer power remains high, as consumers demand seamless UX, while supplier power is centralized among data providers. Ultimately, the industry is shifting toward a platform-driven ecosystem where data dominance dictates market survival.
SWOT analysis of the AI travel sector
The strengths include immense data volume and rapid scalability via cloud-based deployment. Weaknesses involve high implementation costs for SMEs. Opportunities abound in security and fraud detection, where AI can preemptively identify risks. Threats remain centered on geopolitical stability and tightening international data regulations, which could potentially stifle the rapid growth projected for 2027-2033 if not managed through compliant technological adoption.
Value chain analysis: From raw data to end-user
The value flow begins with raw travel inventory data—such as airline seats or hotel availability—processed through revenue management software and AI recommendation engines. This data is refined into actionable insights via Data Analytics and Insights Services. The final tier involves consumer-facing platforms like Despegar.com Inc. or Fareportal, which deliver the personalized experience, ensuring the value chain captures maximum margin through Digital Marketing Services and precision booking.
Investment insights and high-potential areas
Investors should target AI-powered security and fraud detection, which remains an underserviced vertical. There is also significant upside in Training and Support Services as legacy carriers struggle to implement AI tools effectively. Based on the 35.45% CAGR, allocating capital toward companies like Duetto, which specialize in high-yield revenue management, offers the most robust risk-adjusted return within the broader Artificial Intelligence (AI) In Travel Market.
Conclusion: Synthesizing the market future
The Artificial Intelligence (AI) In Travel Market is in a phase of aggressive maturation. With a forecast reaching 1990.56 Billion by 2033, the integration of AI is not merely an enhancement—it is an existential necessity. Players who successfully bridge the gap between cloud-based operational efficiency and individualized traveler experiences will dictate the future of global tourism. Data-driven agility is now the primary competitive differentiator.
Methodological approach to market valuation
Our methodology utilizes triangulation: cross-referencing global trade registry data, proprietary primary stakeholder interviews, and secondary macroeconomic indicators. We analyze company annual reports, such as those from Expedia Group Inc., and adjust for regional inflation and tech adoption variance. This rigorous framework ensures our projections reflect the real-world complexities of the travel market, providing an accurate, validated forecast for the 2027-2033 period.
Scope and limitations of the report
This report focuses on the Artificial Intelligence (AI) In Travel Market, covering software, services, and deployment modes from 2026 to 2033. It explicitly excludes general-purpose software outside travel and limits analysis to AI-specific applications. Limitations include the unpredictable nature of regional regulatory shifts and potential rapid disruption from generative AI advancements that may impact long-term adoption rates in specific geographic sectors.
Recent market developments and strategic moves
Recent developments underscore a race toward strategic partnerships. Notable moves include integration of generative AI into customer-facing chatbots by Cleartrip Private Limited and expanded cloud-based infrastructure investments by major global airlines. These announcements, combined with new personalized recommendation product launches, signal an industry-wide effort to capture value from the projected market growth, ensuring that AI remains at the center of the next generation of travel tech.