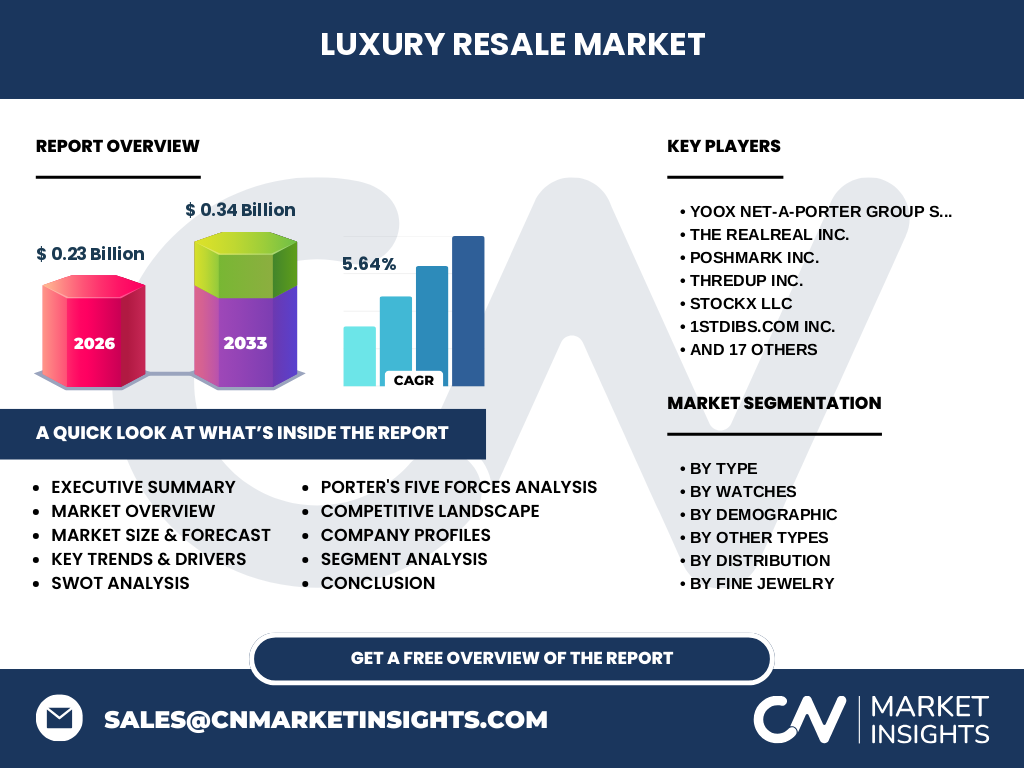
Market Overview: Defining the Luxury Resale Market landscape
The Luxury Resale Market represents a sophisticated secondary ecosystem for high-end assets. Valued at 0.23 Billion in 2026, this sector encompasses the circular lifecycle of premium goods, ranging from iconic leather handbags to horological investments. It functions as a critical hedge against inflationary pressures, allowing discerning collectors and budget-conscious aspirational buyers to access brands while promoting sustainable consumption patterns globally.
Structural Growth Drivers, Restraints, and Opportunities
Primary growth is fueled by digitally-native platforms that minimize friction in global trade. While logistics hurdles and authenticity verification concerns act as market restraints, the industry finds massive opportunities in AI-driven appraisal tools. Players like The RealReal and Vestiaire Collective are effectively capturing consumer trust, creating a robust framework to overcome regional regulatory variations and supply chain fragmentation.
Emerging Trends and Strategic Patterns
The shift toward 'investment-grade' asset ownership is the most significant trend. We are seeing a move from purely disposal-based reselling to strategic curation. Technologies ensuring provenance transparency, such as blockchain-backed certificates, are becoming standard. This evolution is particularly visible in high-value segments like Vintage Watches and Limited Edition Watches, where historical rarity dictates resale liquidity.
COVID-19 Impact and Recovery Analysis
The pandemic acted as a catalyst for digitalization, forcing a rapid shift toward online resale channels. While initial supply chains faced localized constraints, the sector saw a post-pandemic surge in demand as consumers re-evaluated luxury investments. The recovery trajectory remains strong, driven by improved logistics for Luxury Furniture and Designer Tech, confirming a permanent change in consumer habits regarding pre-owned goods.
Competitive Landscape and Strategic Dynamics
Market concentration is evolving as StockX LLC and 1stdibs.Com Inc. dominate specific niches like sneakers and interior design. Strategic dynamics favor firms offering comprehensive authentication services. With players like Fashionphile Group LLC and Rebag competing for market share, the industry is seeing aggressive investments in logistical hubs to optimize the movement of high-value inventory between buyers and sellers.
Executive Summary: Key Findings
Our analysis reveals a highly resilient market positioned for consistent growth. The sector is set to expand from 0.23 Billion in 2026 to 0.34 Billion by 2033, growing at a CAGR of 5.64%. This trajectory underscores the transition of luxury goods from consumption items to liquid financial assets, fundamentally altering how traditional brands interact with their secondary market.
Market Forecast: 2027 to 2033 Projections
We forecast a steady CAGR of 5.64% throughout the forecast window. By 2033, the total market size is projected to reach 0.34 Billion. This growth is contingent on continued expansion in Apparel and Accessories and the increasing maturity of cross-border trade regulations, which will facilitate higher volumes of Fine Jewelry and Leather Goods transactions worldwide.
Segmentation Analysis of the Luxury Resale Market
The market is segmented by Type, Demographic, and Distribution. Key segments include Apparel and Accessories, Watches, and Leather Goods, each serving distinct consumer needs. Distribution is bifurcated into online platforms, brick-and-mortar stores, and specialized consignment boutiques. This granularity allows stakeholders to target specific niches, such as Brooches within Fine Jewelry or Luxury Cars in the Other Types category.
Regional Performance Dynamics
Geographic distribution shows that mature western economies and rapidly emerging luxury hubs lead the charge. Regulatory environments in the EU and North America provide the legal framework for professionalized resale, while Asia-Pacific markets exhibit the fastest growth. These regions are experiencing localized constraints regarding import-export taxes, necessitating specialized logistics strategies for firms like Luxepolis Retail Services Pvt Ltd.
In-Depth Regional Review
The North American market dominates due to high digital adoption, while the EMEA region benefits from deep-rooted heritage markets in vintage luxury. Conversely, the APAC market is rapidly adopting online platforms for Luxury Watches. Each region faces unique logistical hurdles; for example, customs clearance at major international ports remains a decisive factor for firms operating complex cross-border Fine Jewelry supply chains.
Strategic Positioning of Leading Companies
Companies are segmenting by value proposition. YOOX Net-a-Porter Group S.p.A. leverages deep brand relationships, whereas ThredUp Inc. focuses on mass-scale Apparel and Accessories logistics. Meanwhile, Luxury Closet Inc. and Cudoni provide white-glove concierge services. This competitive positioning ensures that whether a consumer seeks Small Leather Goods or Rare Vintage Watches, there is a specialized intermediary catering to that specific liquidity requirement.
Porter's Five Forces Assessment
The threat of new entrants is moderate, mitigated by high barriers in authentication technology. Buyer power is increasing, balanced by the strong brand equity of the items being traded. Supplier power remains a concern for rare Limited Edition Watches, while intense rivalry among platforms like Depop Limited and Grailed Inc. keeps transaction fees competitive, ultimately driving efficiency within the total 0.23 Billion market.
SWOT Analysis of the Industry
Strengths include robust demand for sustainable luxury; Weaknesses involve the high cost of authentication infrastructure. Opportunities lie in the untapped potential of Luxury Furniture and Art and Collectibles. Threats remain centered on macroeconomic volatility and potential regulatory shifts affecting the legal sale of high-value items across borders, which could impact the projected 0.34 Billion market size.
Value Chain Analysis
The value chain starts with the original retail transaction, moving through individual owners, and finally to re-commerce platforms. Value is added through professional cleaning, authentication, and marketing. Key nodes involve regional logistics providers and specialized appraisal hubs. By the time Leather Goods or Fine Jewelry reaches the final buyer, the platform has successfully mitigated the asymmetric information inherent in peer-to-peer resale.
Investment Insights and Recommendations
Investors should focus on authentication-tech innovators and platforms with niche dominance in high-margin segments like Watches and Fine Jewelry. Our analysis suggests that companies integrating circular economy KPIs into their valuation models offer the best risk-adjusted returns. Targeting emerging markets where secondary luxury infrastructure is still nascent represents a high-potential strategy for long-term capital appreciation beyond the 2033 horizon.
Conclusion and Key Takeaways
The Luxury Resale Market is professionalizing rapidly. With a forecasted expansion to 0.34 Billion by 2033, the industry demonstrates its viability as a sustainable alternative to primary retail. Success in this market is predicated on trust-based technology, logistics efficiency, and deep segment specialization, ensuring that pre-owned assets retain their value and appeal in an increasingly circular global economy.
Research Methodology: Triangulation Strategy
Our estimates are triangulated using a multi-modal approach. We ingest trade registry data, conduct primary interviews with C-suite executives at firms like Timepiece 360 Ltd., and synthesize secondary macroeconomic indicators. This robust methodology ensures that our CAGR of 5.64% accurately reflects the real-world friction of supply-side inventory constraints and demand-side demographic shifts, providing a reliable baseline for investment planning.
Scope and Parameters of the Report
This report covers the global Luxury Resale Market, specifically examining Apparel, Accessories, Watches, Fine Jewelry, and Leather Goods. It excludes counterfeit trade and focuses exclusively on legitimate, authenticated resale channels. The geographic scope includes North America, EMEA, APAC, and LATAM. Our focus is on the period 2026-2033, providing specific insights into the logistical and regulatory environments affecting these high-value segments.
Recent Developments and Strategic Moves
Recent activity is defined by strategic partnerships between traditional luxury houses and resale platforms. We have observed increased venture capital funding flowing into AI-driven authentication startups. Notable moves include consolidation among mid-tier players to achieve economies of scale in global Small Leather Goods shipping, reflecting a broader intent to streamline the user experience while protecting the brand equity of the items traded.