Market Overview: Defining the Aviation Grade Titanium Sponge Market
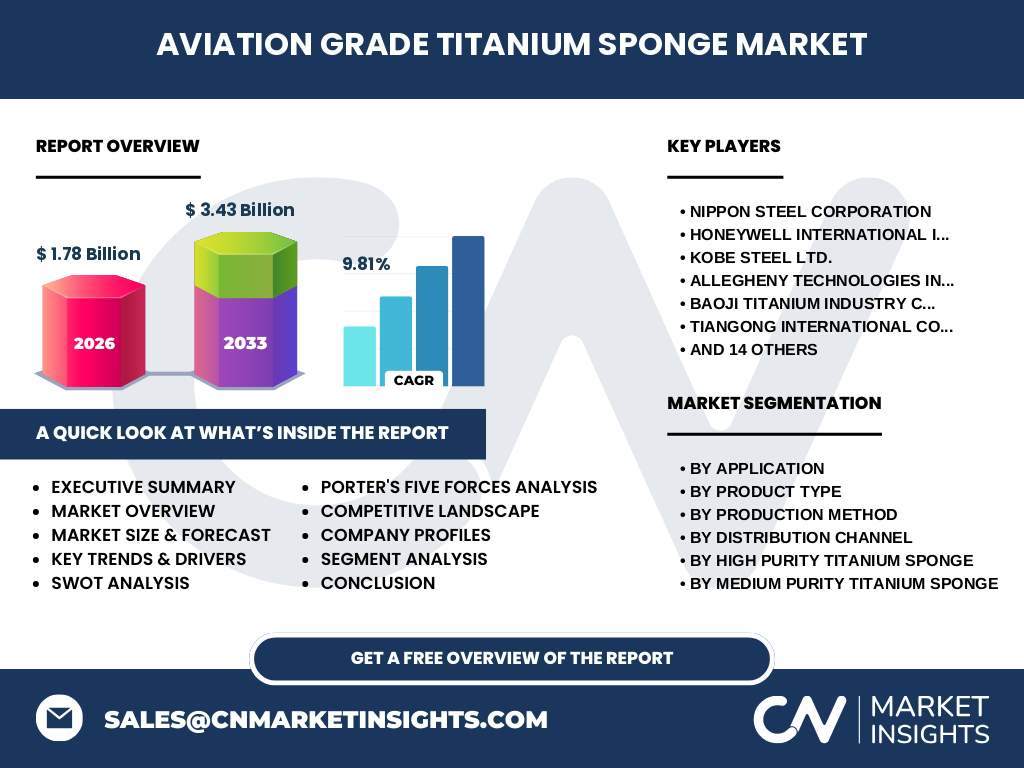
The Aviation Grade Titanium Sponge Market serves as the bedrock for modern aerospace engineering, providing the essential high-purity raw material required for critical airframe and engine components. Our analysis defines this sector as the critical upstream node in the titanium supply chain, where Kroll or FBR processed metals are converted into aerospace-certified alloys. With a valuation of 1.78 Billion in 2026, this market is a specialized, high-barrier-to-entry sector essential for national defense and commercial aviation safety.
Structural Growth Drivers and Market Restraints
The Aviation Grade Titanium Sponge Market is primarily propelled by the surge in commercial aircraft production and defense modernization. Key drivers include the adoption of lightweight alloys to enhance fuel efficiency. However, strict regulatory hurdles from bodies like the FAA and EASA, coupled with the volatility of raw material access, act as primary restraints. Strategic players must balance high production costs against the unrelenting demand for high-purity sponge in demanding flight conditions.
Emerging Trends in the Titanium Sector
We are witnessing a definitive shift toward sustainability and process efficiency, specifically through the Fluidized Bed Reactor (FBR) process. This trend is reshaping the Aviation Grade Titanium Sponge Market by reducing energy consumption compared to the traditional Kroll process. Furthermore, the rising demand for additive manufacturing-compatible titanium powders is forcing traditional sponge producers like Nippon Steel and Kobe Steel to pivot toward higher purity standards to capture premium aerospace margins.
COVID-19 Impact and Recovery Trajectory
The pandemic caused a sharp contraction in the Aviation Grade Titanium Sponge Market due to global supply chain paralysis and the stagnation of commercial airline fleets. However, the recovery trajectory has been robust, fueled by a backlog in aircraft deliveries. Current data suggests that the market has successfully bypassed the 2026 1.78 Billion baseline, with aerospace manufacturers prioritizing stock-piling to mitigate future logistical disruptions and geopolitical uncertainty in supply chains.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is heavily concentrated among global titans like Nippon Steel Corporation, Kobe Steel Ltd., and Allegheny Technologies Incorporated (ATI). These firms leverage their proprietary smelting capabilities to dominate the high-purity segment. Meanwhile, firms like Baoji Titanium Industry Co. Ltd are aggressively scaling output. Our research shows that market concentration remains high, as players with long-standing aerospace qualifications hold a distinct competitive advantage over emerging low-cost manufacturers.
Executive Summary: Synthesis of Key Findings
This report confirms the Aviation Grade Titanium Sponge Market is entering a high-growth phase. We forecast the market to reach 3.43 Billion by 2033, growing at a CAGR of 9.81%. Success in this sector hinges on navigating the transition from standard production methods to specialized, ultra-high purity grades. Stakeholders must prioritize investment in technological innovation and regional supply chain security to capitalize on the sustained expansion of both commercial and military aerospace programs.
Market Forecast: 2027 to 2033 Projections
Based on our proprietary modeling, the Aviation Grade Titanium Sponge Market is set for significant expansion, escalating from the 2026 baseline to a valuation of 3.43 Billion by 2033. This growth, reflecting a steady 9.81% CAGR, is driven by the rapid modernization of global air fleets and increased defense expenditure. We anticipate the most significant fiscal gains will materialize between 2029 and 2031 as new engine platforms scale production.
Segmentation Analysis: Product and Application Mapping
Our segmentation framework divides the market by Product Type—High Purity vs. Medium Purity—and Application. High-purity sponge is critical for aerospace alloys, while medium-purity variants serve industrial turbines and structural airframe parts. Understanding these segments is vital, as the Aviation Grade Titanium Sponge Market increasingly favors high-purity inputs to meet the stringent fatigue-resistance requirements mandated for modern, high-stress flight environments.
Regional Market Analysis: Geographic Performance
The Aviation Grade Titanium Sponge Market performance is currently localized within major aviation manufacturing hubs. North America and Europe lead in consumption due to the concentration of major airframers, while the Asia-Pacific region is surging in production capacity, led by Baoji Titanium and Toho Titanium. Trade registries and localized port data suggest that logistical efficiency is becoming a major determinant of regional competitiveness, particularly as supply chains consolidate around key international shipping nodes.
Company Profiles: Strategic Positioning of Industry Leaders
Leading companies like Honeywell International Inc. and ATI utilize vertical integration to control the flow from titanium sponge to finished aerospace components. Conversely, companies such as Toho Titanium Co. Ltd. and Luoyang Shuangruiwanji focus on optimizing the Kroll process to capture market share in high-volume, mid-tier supply. Our analysis reveals that strategic partnerships between these producers and original equipment manufacturers (OEMs) are the primary driver of stable, long-term revenue growth.
Porter's Five Forces: Competitive Forces Assessment
The Aviation Grade Titanium Sponge Market faces intense rivalry among a few established global players. While the threat of new entrants is low due to extreme capital requirements and aerospace certification barriers, the bargaining power of buyers—major aerospace OEMs—is exceptionally high. This forces constant innovation in production efficiency and cost-reduction, as manufacturers must prove metallurgical consistency to survive the rigorous vendor vetting processes of top-tier aircraft builders.
SWOT Analysis: Strategic Outlook
Strengths: Unmatched material durability. Weaknesses: High energy-intensity during the Kroll process. Opportunities: Expanding the Aviation Grade Titanium Sponge Market into next-gen space exploration and hypersonics. Threats: Fluctuating raw material prices and geopolitical shifts affecting ore imports from key regions. This analytical framework highlights that the market’s resilience depends on its ability to hedge against volatile input costs while maintaining the high standards required for aerospace flight components.
Value Chain Analysis: From Ore to End-User
The Aviation Grade Titanium Sponge Market value chain begins with mineral extraction, moving through sponge production—using Kroll or FBR—to alloy melting, forging, and eventual component fabrication. Value flow is highly constrained by the requirement for AS9100 certification at every stage. We note that profitability is highest at the sponge-to-alloy conversion phase, where firms like Kobe Steel and ATI provide specialized metallurgical formulations that add significant value beyond the raw material costs.
Investment Insights: Strategic Recommendations
We recommend that investors prioritize firms currently optimizing Cold Hearth melting and FBR technologies. The Aviation Grade Titanium Sponge Market offers long-term alpha for companies that can demonstrate supply chain transparency and consistent quality. Targeted investment in regional plants near key aviation clusters, such as those in East Asia and the US, offers the best protection against logistical bottlenecks and satisfies the increasing demand for locally-sourced, certified aerospace materials.
Conclusion and Key Takeaways
The Aviation Grade Titanium Sponge Market is a critical, high-growth industrial sector expected to reach 3.43 Billion by 2033. The primary takeaways from our research are that technological agility in production and the ability to navigate complex regulatory frameworks are the most significant markers of long-term success. Firms that can innovate on purity while managing energy-intensive production costs will define the future of this essential aerospace commodity market.
Research Methodology: How We Triangulate Data
Our analysis for the Aviation Grade Titanium Sponge Market utilizes a multi-layered triangulation approach. We integrate trade registry data, primary interviews with key aerospace metallurgy experts, and secondary macroeconomic indicators. By cross-referencing production output from major players like Nippon Steel with global aircraft delivery schedules, we provide a proprietary estimate that accounts for both current demand and long-term industrial capacity, ensuring the highest level of accuracy for our market forecasts.
Scope of the Report and Coverage Parameters
This report examines the global Aviation Grade Titanium Sponge Market, covering the competitive landscape, technical production methodologies, and regional demand dynamics. The scope excludes consumer-grade non-aerospace titanium to ensure data precision regarding high-purity aerospace requirements. Our analysis is bounded by the forecast period of 2027 to 2033 and focuses exclusively on the commercial, military, and spacecraft sectors, providing a deep-dive into the materials that define the modern aerospace industry.
Recent Developments: Strategic Moves in the Market
Recent activity in the Aviation Grade Titanium Sponge Market shows a trend of strategic consolidation and capacity expansion. Major announcements from Kobe Steel and Baoji Titanium indicate heavy investment in automation to stabilize yield. Furthermore, recent partnerships between sponge producers and aerospace engine manufacturers signify a move toward exclusive supply agreements, aiming to secure reliable inputs of high-purity titanium in an increasingly volatile global raw material market environment.
Summary: Impact of Production Methods on Market Value
The transition in production methodology is the most significant internal dynamic within the Aviation Grade Titanium Sponge Market. While the Kroll process remains dominant, the rise of the Fluidized Bed Reactor (FBR) is offering a superior efficiency profile. Our analysis shows that producers capable of scaling FBR technology are gaining a competitive edge, enabling them to meet the 9.81% CAGR requirements by providing higher-purity material with a lower overall carbon and energy footprint.