Market overview and industry significance of the Moisturizers Market
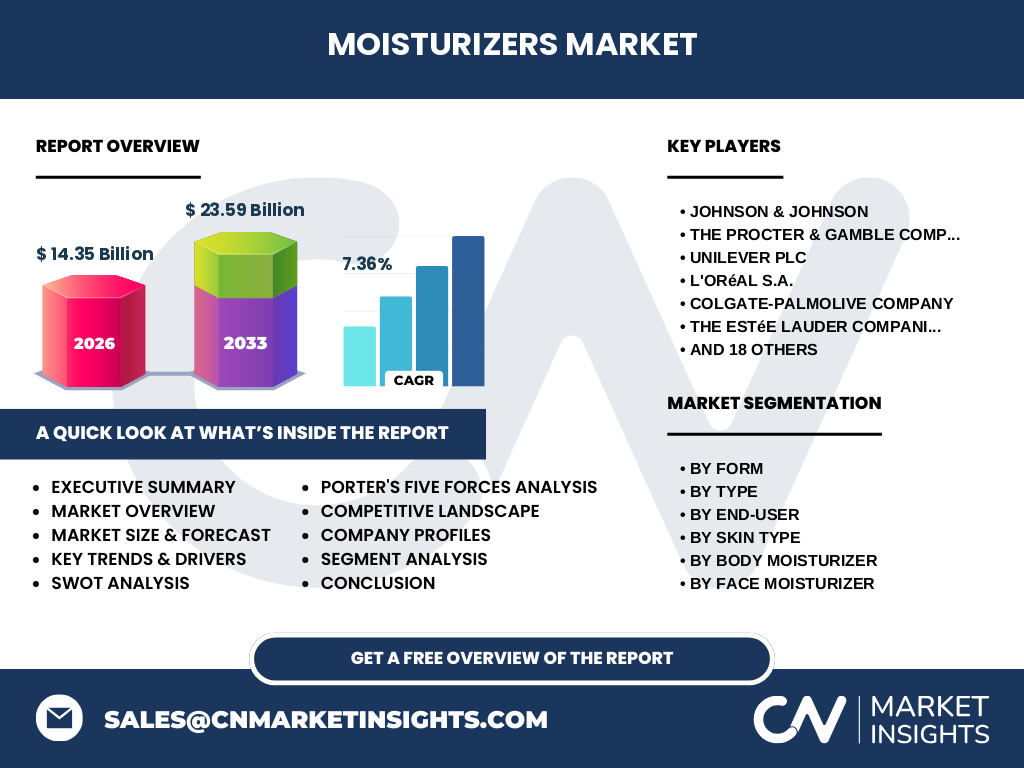
The Moisturizers Market represents a core pillar of the personal care industry, encompassing formulations designed to maintain skin barrier integrity. With a 2026 market size of 14.35 Billion, the sector is critical to dermatological health. Industry participants must navigate complex regulatory environments like the FDA and EU Cosmetic Regulation to ensure efficacy, while leveraging raw materials like ceramides and hyaluronic acid to meet consumer demands for medical-grade hydration.
Core structural growth drivers and market restraints
Growth is primarily driven by rising consumer awareness regarding preventive skincare and the normalization of gender-neutral beauty routines. However, the market faces logistical hurdles, including volatile supply chain costs for specialized emollients and humectants. Our research highlights that geopolitical instability impacting shipping through key hubs like the Port of Shanghai forces firms like L'Oréal S.A. to localize supply chains to mitigate inventory disruption.
Emerging trends and innovation patterns in the Moisturizers Market
The shift toward clean-label, high-performance formulations is reshaping product development. Innovation is now centered on biotech-derived peptides and personalized skincare algorithms. Companies like The Estée Lauder Companies Inc. are increasingly focusing on the serums and gels segment, which offers higher margins than traditional creams. This movement emphasizes ingredient transparency, requiring strict adherence to environmental safety standards set by regional regulatory bodies.
The impact of COVID-19 and recovery trajectory
The pandemic caused a temporary contraction in retail-heavy segments but accelerated the digital transformation of distribution channels. With online stores becoming the primary point of purchase during lockdowns, firms like Unilever PLC pivoted resources toward direct-to-consumer platforms. Recovery has been robust, characterized by a renewed emphasis on self-care and sanitizing-related dryness, leading to consistent growth as supply chains normalized across global markets.
Competitive benchmarking and strategic dynamics
The Moisturizers Market is characterized by a concentrated landscape dominated by industry titans like Johnson & Johnson, The Procter & Gamble Company, and Kao Corporation. Strategic dynamics focus on M&A activity to acquire niche, high-growth sustainable brands. This competitive posture forces incumbents to invest heavily in R&D to differentiate their face moisturizer portfolios against emerging indie challengers that utilize aggressive social media marketing.
Executive Summary: Synthesis of market findings
Our analysis confirms that the Moisturizers Market is poised for significant expansion, transitioning from a 2026 valuation of 14.35 Billion to a projected 23.59 Billion by 2033. This reflects a CAGR of 7.36%. The convergence of premiumization in the face moisturizer segment and high-frequency usage of body lotions among aging populations remains the cornerstone of this positive long-term growth forecast.
Projected growth trajectory from 2027 to 2033
Driven by robust demand in emerging economies, the market is set to achieve a CAGR of 7.36% through the forecast period. We anticipate the total valuation will reach 23.59 Billion by 2033. The primary engine for this acceleration is the widening demographic of users for anti-aging moisturizers and specialized medicated body treatments, supported by continuous technological advancements in delivery systems.
Breakdown of market segments and their strategic roles
The market is segmented by form, type, end-user, and skin type. While creams hold volume, serums and gels within the face moisturizer category serve as high-value innovation drivers. Segmenting by skin type—specifically sensitive and dry—allows for tailored marketing strategies that drive consumer loyalty. Our research suggests that the infant and kids segment is also gaining traction as parents prioritize hypoallergenic, science-backed care.
Geographic distribution and regional performance
Regional performance is dictated by disposable income levels and skin-specific environmental challenges. North America and Europe dominate in premium anti-aging products, while the Asia-Pacific region displays rapid growth in the gel and lotion segments. Logistical efficiency in these regions is heavily reliant on established distribution networks, including supermarkets and hypermarkets, which remain the high-volume backbone of regional retail for major players like Shiseido Company Limited.
In-depth review of key regional market dynamics
In North America, demand for fragrance-free and medical-grade moisturizers remains high, influenced by clinical dermatologist endorsements. Conversely, the Asia-Pacific region is witnessing a surge in tinted moisturizers and hydration masks, driven by evolving beauty standards. Companies like Amorepacific Corporation are effectively leveraging regional manufacturing hubs to minimize lead times, contrasting with the import-heavy logistical strategy often seen in secondary markets.
Company profiles and strategic positioning
Leading entities like Beiersdorf AG and Clarins Group maintain dominance through massive brand equity and R&D pipelines. Burt's Bees Inc. leverages a natural, ingredient-led positioning to capture the growing eco-conscious consumer base. Meanwhile, HCP Wellness Private Limited and Nutrix International LLC are emerging as key contract manufacturers, providing critical white-label support that allows smaller startups to enter the competitive moisturizers market with lower entry barriers.
Porter's Five Forces analysis of the market
The threat of new entrants is moderate due to high marketing costs, yet niche brands disrupt via digital agility. Supplier power is low due to the commoditized nature of base raw materials, but high for specialty active ingredients. Competitive rivalry is intense among major incumbents, while buyer power is increasing due to the wealth of information available through online reviews and competitive price matching.
SWOT Analysis: Market internal and external factors
Strengths: Established distribution channels and high brand loyalty. Weaknesses: Heavy reliance on synthetic chemicals that face increasing regulatory scrutiny. Opportunities: High growth potential in the men's skincare segment and personalized formulations via AI. Threats: Rising raw material costs, shifting international environmental trade regulations (like REACH), and potential supply chain bottlenecks in critical logistics corridors that could disrupt the global flow of premium personal care goods.
Value chain analysis and industry structure
The value chain initiates with raw material suppliers of surfactants and botanical extracts, moving into formulation R&D by companies like Revlon Inc. and Kiehl's LLC. Manufacturing occurs in specialized facilities, followed by distribution through online and specialty stores. Value capture is highest at the consumer end, where brand storytelling and clinical evidence effectively justify premium pricing structures for advanced moisturizing solutions.
Investment insights and high-potential areas
Investors should prioritize the men's and infant/kid segments, which currently demonstrate significant white space for growth. High-potential ROI exists in companies integrating sustainable packaging and biocompatible ingredients. Our analysis indicates that the most successful ventures in the 2027–2033 period will be those that effectively leverage AI-driven personalization to solve specific, granular skin concerns, a trend currently under-penetrated in traditional mass-market retail channels.
Conclusion and key takeaways for stakeholders
The Moisturizers Market presents a compelling growth narrative, transitioning from 14.35 Billion in 2026 to 23.59 Billion by 2033. Success hinges on a hybrid strategy: balancing mass-market distribution through supermarkets and hypermarkets with premium digital-first engagement. Stakeholders should focus on regional agility, particularly in responding to localized ingredient regulations and consumer preferences for clean, evidence-based dermatological solutions.
Research methodology and triangulation processes
Our baseline estimates are derived through a triangulation of primary stakeholder interviews, including industry dermatologists and supply chain managers, with secondary data from trade registries and macroeconomic indicators. We cross-reference retail audit data with company financial reports to ensure accuracy. This multi-layered approach ensures that our 7.36% CAGR projection accounts for both localized consumer behavior and broader global economic variables influencing the moisturizers market.
Scope of the report and coverage parameters
This report covers the global moisturizers market across all primary form factors, including creams, lotions, and gels. It analyzes geographic performance across North America, Europe, Asia-Pacific, and LAMEA. Limitations include the exclusion of professional dermatological-only clinical procedures, focusing strictly on over-the-counter and specialty retail moisturizing products. The scope is defined to assist strategic planning for manufacturers, retailers, and private equity investors.
Recent developments in the market
Recent activity is defined by strategic partnerships between beauty conglomerates and ingredient innovators. For instance, recent product launches by Avon Products Inc. and Mary Kay Inc. have emphasized sustainability and transparency. Furthermore, companies like Natura Europa SAS have announced significant supply chain investments to reduce their carbon footprint, reflecting a broader trend where environmental performance is becoming a key competitive differentiator in the moisturizers market.