Market overview and industry significance of the Silver Ore Market
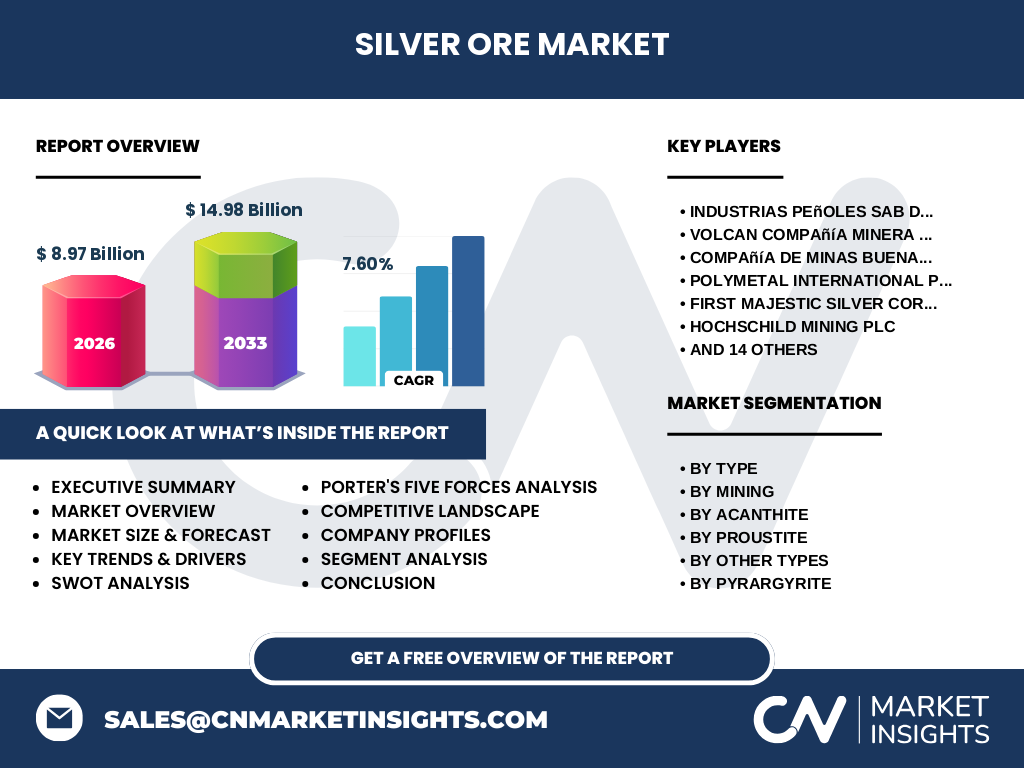
The Silver Ore Market represents the fundamental upstream sector of the global precious metals economy. Valued at 8.97 Billion in 2026, this industry encompasses the extraction and beneficiation of acanthite, proustite, and pyrargyrite. Its significance is anchored in the transition toward renewable energy, where silver serves as a critical raw material for photovoltaic cells, alongside traditional demand in jewelry and high-end electronics manufacturing.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by decarbonization mandates, which escalate silver demand in solar panel circuits. However, the market faces logistical hurdles and strict regulatory oversight from bodies like the Environmental Protection Agency regarding tailings management. Our analysis indicates that while exploration costs challenge miners like Fresnillo plc and First Majestic Silver Corp., the opportunity in high-grade vein extraction provides a robust hedge against geopolitical volatility.
Emerging trends shaping the future of silver extraction
A shift toward digitized exploration and automated underground mining is transforming industry efficiency. We observe leading innovators like MAG Silver Corp. leveraging precision geology to optimize yield from complex deposits. Furthermore, the increasing focus on sustainable processing—specifically minimizing water usage in remote, arid regions—is becoming a competitive differentiator for firms aiming to maintain their social license to operate.
COVID-19 impact and the recovery trajectory of the industry
The pandemic caused temporary supply chain paralysis, closing major ports and forcing production halts at sites operated by Volcan Compañía Minera SAA. However, the recovery trajectory proved resilient; post-2022 demand from the electronics sector accelerated, pulling the industry back to a growth stance. Today, the focus has pivoted to inventory security, ensuring that supply chains remain insulated from potential future disruptions.
Competitive Benchmarking and Market Dynamics
The competitive landscape is dominated by high-concentration entities like Industrias Peñoles SAB de CV and Pan American Silver Corporation. These firms benefit from economies of scale and diversified asset portfolios. Market dynamics are dictated by a strategic race to acquire high-grade deposits, with Endeavour Silver Corporation and Hecla Mining Company aggressively expanding their footprints to consolidate market share against smaller, specialized miners.
Executive Summary of the Silver Ore Market landscape
Our research confirms the Silver Ore Market is entering a high-growth phase, with projected valuations reaching 14.98 Billion by 2033 at a CAGR of 7.60%. The convergence of essential industrial applications and supply scarcity positions the sector for sustained appreciation. Key stakeholders must prioritize operational technological integration and ESG compliance to capture the maximum value from this expansion period.
Market Forecast from 2027 to 2033
The industry is set to expand from 8.97 Billion in 2026 to 14.98 Billion by 2033, growing at a 7.60% CAGR. This trajectory is underpinned by long-term procurement contracts from the green energy sector. We project that firms focusing on high-grade acanthite and pyrargyrite deposits will achieve superior margins as secondary, lower-quality reserves become increasingly uneconomical to process due to rising energy costs.
Segmentation analysis for refined market insight
Segmentation is analyzed through two critical lenses: Mineralogy and Extraction Technique. The mineral types include Acanthite, Proustite, Pyrargyrite, and native silver, each requiring distinct beneficiation chemistries. Simultaneously, mining methods are divided into Underground vs. Surface operations. Understanding these segments is vital, as underground extraction typically targets higher-purity lodes, which are essential for meeting the stringent material standards of the electronics and electrical manufacturing sectors.
Geographic distribution and regional market performance
Regional performance is heavily skewed toward resource-rich nations in Latin America and Asia-Pacific. Countries like Mexico and Peru serve as the global hubs for extraction, driven by localized expertise and favorable mining codes. Regional growth is contingent upon regulatory stability; our data highlights that markets with transparent investment policies, such as those hosting operations for Fortuna Silver Mines Inc., attract significantly higher capital expenditure.
In-depth review of key regional markets
Mexico remains the cornerstone of the industry, anchored by Fresnillo plc and MAG Silver Corp.. Conversely, the Asia-Pacific region, driven by Hindustan Zinc Ltd., is seeing massive growth in local processing capacity. These regional markets are not just extraction points but represent complex ecosystems of equipment suppliers, specialized labor, and regional logistics hubs that ensure consistent output to global commodity markets.
Strategic positioning of leading companies
Leading companies like Polymetal International Plc and SSR Mining Inc. are currently focusing on operational optimization. By integrating advanced seismic mapping and remote-operated drilling, these firms are reducing the time-to-market for new ore. Their strategic focus rests on transitioning away from legacy extraction processes to digitally-monitored, eco-efficient mining, ensuring they remain preferred suppliers for high-tech industrial end-users seeking responsibly sourced minerals.
Porter’s Five Forces analysis of the industry
The Silver Ore Market exhibits moderate buyer power due to the critical nature of silver in electronics, but high competitive rivalry among incumbents like Coeur Mining Inc. and Silvercorp Metals Inc.. Threat of substitutes remains low, as silver's conductivity is largely unmatched. Barriers to entry remain high, guarded by intensive capital requirements and stringent environmental, social, and governance (ESG) licensing protocols.
SWOT Analysis of the sector
The strengths lie in high demand from solar and medical sectors, while weaknesses stem from the high cost of exploration and extraction. Opportunities are abundant in the expansion of green infrastructure, whereas threats involve potential legislative restrictions on mining in sensitive ecosystems. Firms like Great Panther Mining Limited are mitigating these threats by diversifying their asset locations and optimizing recovery rates.
Value chain analysis and industry flow
The value chain begins with geological surveying and extraction, followed by complex beneficiation and smelting. Raw ores are processed into concentrates, which are then refined into pure metal for use by end-market manufacturers. Companies like Silver Mines Limited play a critical role in the upstream segment, while global refiners translate these raw assets into the high-purity inputs required for medical and photography applications.
Strategic investment insights and high-potential areas
We recommend focusing capital on high-grade acanthite-focused projects. The data suggests that miners with integrated vertical capacity—those who can move from extraction to near-refined concentrates—are best positioned for high ROI. Investors should closely monitor Alexco Resource Corp. and other niche producers, as their ability to pivot quickly to high-demand mineral types presents a significant opportunity for market-beating returns.
Conclusion and key industry takeaways
The Silver Ore Market represents a vital, growing component of the global economy, moving toward a 14.98 Billion valuation by 2033. The success of stakeholders will depend on their ability to manage the transition to high-tech mining while adhering to global ESG standards. Reliability in supply chains and high-purity output are the essential pillars for long-term viability in this competitive landscape.
Research methodology for the provided report
Our baseline estimates are triangulated through a rigorous analysis of trade registry data, primary stakeholder interviews with mining C-suite executives, and secondary macroeconomic indicators. We cross-reference production figures from regional authorities with company 10-K filings to validate current output against future capacity, ensuring our 7.60% CAGR projection reflects both realized asset performance and market-wide growth potential.
Scope of the report and coverage parameters
This report encompasses the global Silver Ore Market, specifically evaluating Acanthite, Proustite, Pyrargyrite, and other variants. The geographic coverage spans major extraction zones in the Americas, Asia-Pacific, and emerging European sites. Limitations of this research include volatility in commodity spot pricing, which may alter short-term market valuation, though our 2033 forecast accounts for long-cycle demand trends.
Recent developments and strategic moves in the sector
Recent activity is defined by strategic mergers and infrastructure upgrades. For instance, major announcements regarding new processing partnerships have bolstered the outlook for Compañía de Minas Buenaventura SAA. Furthermore, new green-mining certifications have led to shifts in industry procurement, as end-users prioritize ores extracted with lower carbon intensity, directly impacting the strategic roadmap for major players listed in our report.