Market Overview: Defining the Cosmetics Stores Market landscape
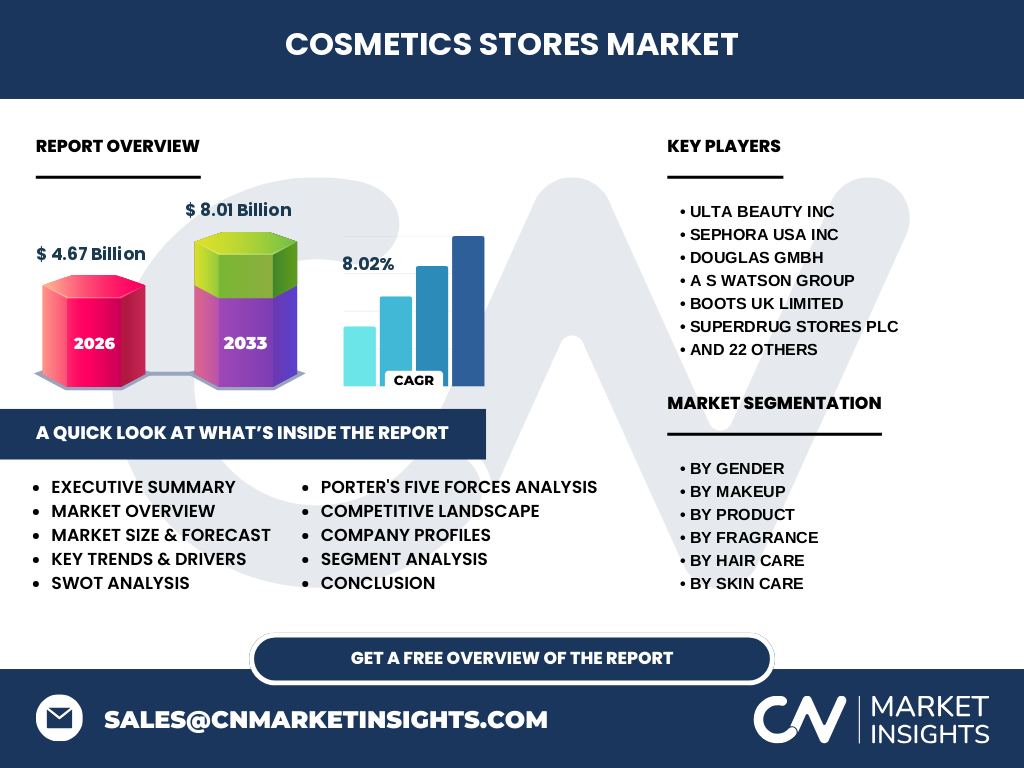
The Cosmetics Stores Market represents the physical and digital retail ecosystem for beauty, encompassing skin care, hair care, and fragrance. In 2026, the market reached a valuation of 4.67 Billion. It serves as a vital bridge between manufacturers and consumers, heavily influenced by regulatory standards such as the EU Cosmetic Regulation (EC) No 1223/2009. Our analysis highlights this sector's shift toward experiential retail as a primary significance for value creation.
Structural Growth Drivers and Market Restraints
Primary growth is driven by the 8.02% CAGR, fueled by rising demand for clean-label raw materials and personalized men's grooming products. However, logistical hurdles at major ports often disrupt supply chains, while stringent FDA compliance acts as a barrier for smaller boutiques. Our research indicates that success depends on navigating these regulatory frameworks while balancing the rising cost of imported ingredients in specialized cosmetic formulations.
Emerging Trends Reshaping Cosmetics Retail
The shift toward omnichannel personalization is the most critical emerging trend. Consumers now demand seamless integration between offline stores and digital apps, a space where Nykaa FSN E-Commerce Ventures and Sephora USA Inc excel. Growth is heavily influenced by the adoption of virtual try-on technologies for lip products and face makeup, fundamentally altering the traditional in-store testing experience and increasing conversion rates through interactive digital engagement.
Post-Pandemic Recovery Trajectory
The COVID-19 impact significantly accelerated the shift toward online distribution channels. While physical stores faced temporary shutdowns, the industry’s recovery trajectory shows a robust rebound as foot traffic returns to prestige retail outlets like Ulta Beauty Inc. Based on our analysis, the pandemic prompted a structural change in inventory management, pushing retailers to adopt lean retail models that hedge against future supply chain volatility while prioritizing digital agility.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is highly concentrated among dominant players including A S Watson Group, Boots UK Limited, and DM Drogerie Markt GmbH. Strategic dynamics involve heavy investment in loyalty programs and exclusive brand partnerships. We observe that retailers are focusing on niche portfolios—like Lush Cosmetics’ sustainability focus or Kiehl’s LLC’s dermatological expertise—to differentiate themselves in an increasingly crowded retail market, aiming to capture higher margins from brand-loyal premium shoppers.
Executive Summary: High-Level Market Synthesis
The Cosmetics Stores Market is poised for significant expansion, with a forecast growing from 4.67 Billion in 2026 to 8.01 Billion by 2033. Our research confirms that the premium segment and unisex grooming category will be primary catalysts. Sustained growth relies on the successful synthesis of tech-driven retail environments and physical touchpoints, ensuring that retailers remain the primary destination for discerning consumers.
Market Forecast and Long-Term Projections (2027-2033)
We project the market to reach 8.01 Billion by 2033, expanding at a steady 8.02% CAGR. This forecast accounts for shifting consumer demographics and increased spending in the Skin Care and Fragrance segments. Our data-driven model suggests that as discretionary income grows in emerging markets, demand for high-end retail experiences provided by groups like Mecca Brands Pty Ltd will continue to outpace traditional retail growth.
Segmentation Analysis: Deep Dive into Product and Gender
Market segmentation is defined by clear categories: Gender (Men, Women, Unisex), Makeup (Face, Eye, Lip, Tools), and Skin Care (Moisturizers, Serums, Masks). Each segment plays a specific role; for instance, the Men's Grooming segment is currently an under-penetrated, high-growth area. By integrating Kose Corporation Retail and Kanebo Cosmetics Inc, we see how segment-specific product strategies effectively capture diverse consumer requirements across both economy and premium price brackets.
Regional Market Performance and Geographic Distribution
Geographic performance varies significantly, with Europe and North America maintaining strong positions due to established regulatory bodies and high retail infrastructure density. Asia-Pacific is experiencing rapid growth, driven by players like Innisfree and Etude House. Our analysis identifies that localized market constraints—such as customs duties for imported bath and body products—continue to influence the geographic distribution of inventory and regional pricing strategies for international chains.
In-Depth Regional Review: Key Geographic Hotspots
Western Europe remains a hub for premium retail, supported by heavyweights like Douglas GmbH and Rossmann GmbH. Conversely, Southeast Asia represents a high-potential zone for Guardian Health and Beauty. Our analysis shows that regional growth is closely tied to supply chain proximity; companies that can manage local logistics for fragrance and hair treatments near key distribution centers in high-traffic trade regions significantly outperform their competitors on shelf-fill consistency.
Company Profiles: Strategic Positioning and Market Focus
Leading players like MAC Cosmetics and Inglot Cosmetics focus on professional-grade appeal, while Yves Rocher International emphasizes botanical ingredients. Sa Sa International Holdings Limited maintains a dominant footprint in value-oriented retail. Our assessment identifies that their strategic positioning relies on unique value propositions—such as curated product selection or aggressive e-commerce expansion—that allow these brands to maintain distinct market shares even as global consolidation continues to intensify.
Porter’s Five Forces: Competitive Forces Assessment
The threat of new entrants is moderate due to high capital requirements for retail branding. Buyer power is high, forcing retailers like Superdrug Stores plc to innovate on loyalty rewards. Competitive rivalry is intense, as global players vie for shelf space. Supplier power is tempered by the abundance of raw material providers, though specific high-quality organic ingredients create supply chain bottlenecks that influence final product pricing and availability.
SWOT Analysis: Strategic Strengths and Threats
Strengths include the resilience of Skin Care, while weaknesses often involve high operational overheads for brick-and-mortar stores. Opportunities exist in digital integration and men's grooming. Threats encompass volatile raw material costs and shifting regulatory requirements. Our SWOT analysis underscores that retailers must leverage their internal data assets to mitigate these threats, turning operational weaknesses into competitive advantages through precise, AI-driven inventory management and customer-centric marketing.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates from raw material sourcing (botanicals, chemicals) flowing through manufacturers, distributors, and ultimately retailers. Companies like SK II Brand Boutiques manage the vertical chain to ensure premium quality. Our value flow analysis reveals that retailers now extract significant margins by controlling the last-mile interaction, utilizing tools and accessories to increase the average order value and strengthening brand equity throughout the entire supply cycle.
Investment Insights: Strategic Recommendations
Investors should prioritize retailers that integrate biotech-driven skin care and sustainable packaging into their offerings. High-potential areas include the unisex personal care category and tech-enabled, personalized retail outlets. Our strategic recommendations focus on identifying partners that demonstrate strong logistical resilience and digital capabilities, as these factors are the most significant indicators of long-term profitability and market sustainability in the 2027 to 2033 period.
Conclusion and Key Takeaways
The Cosmetics Stores Market is robust, with an expected increase to 8.01 Billion. Success requires balancing physical presence with digital agility and adapting to shifting consumer demands in the Hair Care and Fragrance segments. We conclude that the future belongs to retailers who can leverage data to provide personalized experiences while maintaining efficient, compliant, and sustainable global supply chains.
Research Methodology and Data Triangulation
Our methodology involves triangulating trade registry data, annual filings from corporations like Bath and Body Works LLC, and primary stakeholder interviews. We cross-reference this with macro-economic indicators and regulatory updates. This ensures that the 8.02% CAGR estimate and market valuation are grounded in verified, multi-dimensional inputs, providing a high-confidence outlook for the sector's trajectory through 2033.
Scope of the Report and Coverage Parameters
This report covers the global Cosmetics Stores Market, specifically analyzing product segments like cleansers, styling products, and nail care. The scope encompasses major geographic regions, excluding non-commercial artisanal sales. We focus on the distribution channels of offline and online, providing a comprehensive view of retail dynamics, competitive intensity, and the regulatory factors influencing market participants from 2026 to 2033.
Recent Developments: Market Announcements and Strategic Moves
Recent developments show increased partnerships between technology providers and traditional retailers to enhance virtual try-on experiences. Significant announcements from companies like Shu Uemura Cosmetics Inc highlight a strategic pivot toward sustainable formulations. These strategic moves reflect a broader trend of aligning with clean-beauty mandates and investing in digital conversion tools, which are essential for maintaining competitiveness in the high-growth phase leading up to 2033.