Market overview and industry significance of the Data Sovereignty For Warehouse Systems Market
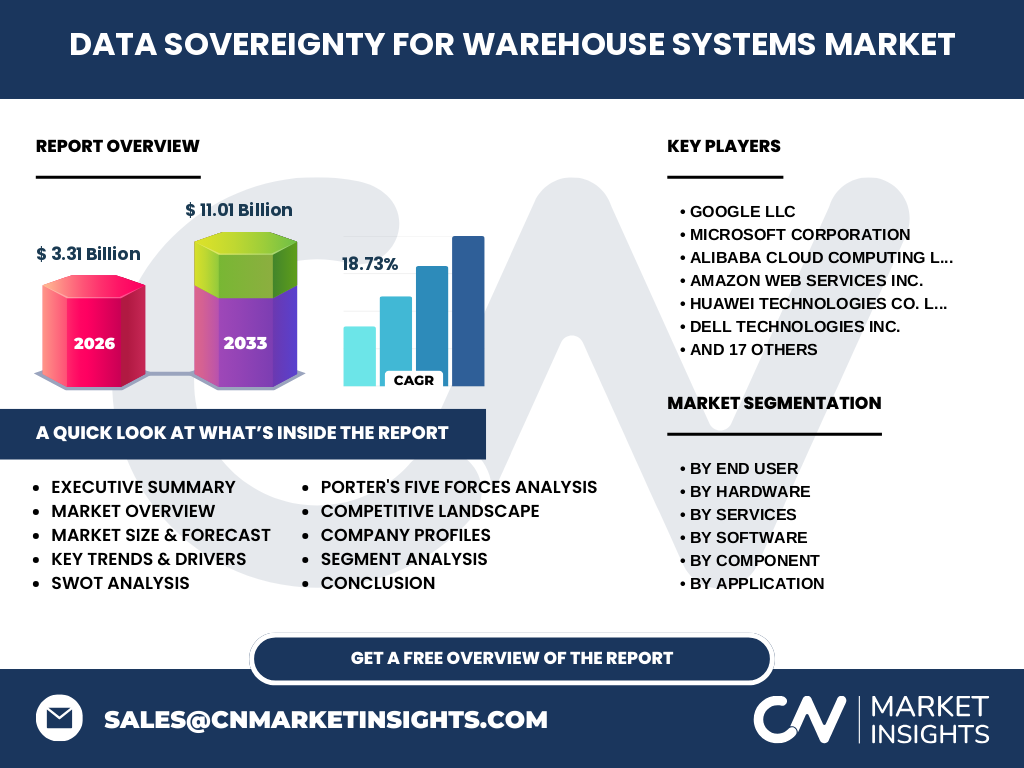
The Data Sovereignty For Warehouse Systems Market is a critical infrastructure domain valued at 3.31 Billion in 2026. It encompasses the governance of logistics data under local legal frameworks like the GDPR or CCPA. As global supply chains face scrutiny, this market provides the essential architectural guardrails to ensure that warehouse operational data remains compliant while maximizing logistical throughput across decentralized storage hubs.
Structural Growth Drivers and Market Constraints
Growth is propelled by aggressive regulatory shifts and the need for localized supply chain autonomy. While the market faces challenges like high capital expenditure for Hardware Security Modules and Network Isolation Equipment, the opportunity lies in mitigating cross-border data leakage. Our analysis indicates that companies effectively balancing data residency with cloud-native flexibility will command the highest market share through 2033.
Emerging trends and growth patterns in the sector
A pivot toward sovereign cloud architectures is redefining the landscape. We observe a trend where edge computing intersects with Data Residency Management Software to keep sensitive inventory data within national borders. This shift is vital for logistics providers operating in politically sensitive regions, ensuring that real-time warehouse telemetry remains insulated from extraterritorial legal access requests or unauthorized third-party data harvesting.
Post-pandemic trajectory and COVID-19 impact analysis
The pandemic acted as a catalyst for digitalization, forcing warehouses to rapidly transition from manual to cloud-integrated systems. However, this shift exposed vulnerabilities in data jurisdiction. Post-recovery, firms are now retrofitting these digital ecosystems with Audit and Compliance Reporting Software to ensure that the accelerated migration during 2020-2022 does not compromise their long-term sovereignty compliance posture within volatile global trade corridors.
Competitive landscape and strategic dynamics
The market is highly concentrated, with tech titans like Microsoft Corporation, Amazon Web Services Inc., and Oracle Corporation providing core infrastructure. Strategic dynamics favor firms that integrate localized infrastructure, such as OVH Groupe SAS or Aruba S.p.A., which capitalize on European sovereign standards. These companies are effectively positioning themselves as neutral compliance brokers in a market where geopolitical tensions often influence hardware procurement decisions.
Executive summary of the Data Sovereignty For Warehouse Systems Market
Our research confirms the Data Sovereignty For Warehouse Systems Market is entering a hyper-growth phase. Valued at 3.31 Billion in 2026, the sector is projected to reach 11.01 Billion by 2033 at a CAGR of 18.73%. Key success factors include deep integration with Manufacturing and Healthcare supply chains, and the deployment of robust Data Classification and Metadata Management Software to ensure regulatory alignment.
Projected growth trajectory from 2027 to 2033
We project the market to sustain a rapid CAGR of 18.73%, reaching 11.01 Billion by 2033. This trajectory is underpinned by massive enterprise investment into Data Localization and Migration Services. As international trade regulations tighten, warehouse operators are moving away from monolithic, centralized cloud models toward sovereign-grade hybrid setups, driving sustained demand for both hardware-based security and specialized software governance.
Segmentation analysis by end-user and technology
Segmentation reveals deep vertical specialization. Healthcare and Manufacturing segments prioritize Secure Storage Systems and Hardware Security Modules to protect proprietary trade secrets and sensitive patient-specific logistics data. Conversely, the Retail sector leans heavily into Policy Enforcement and Governance Software to manage vast volumes of consumer order data while complying with stringent regional privacy mandates and cross-border digital trade laws.
Regional market analysis and performance distribution
Regional performance is dictated by legislative maturity. Europe leads in adoption due to GDPR enforcement, creating high demand for Implementation and Integration Services. North America follows with a focus on Cloud-native sovereignty solutions led by Snowflake Inc. and Databricks Inc. Meanwhile, the Asia-Pacific region is emerging as a hotbed for Dedicated Compute Servers, driven by localized infrastructure policies in manufacturing-heavy economies like China and Vietnam.
In-depth review of key regional markets
The European market remains the most mature, with Atos SE and Scaleway SAS providing indigenous alternatives to hyperscalers. In North America, the market is defined by enterprise-level migrations, where IBM and Dell Technologies Inc. dominate the On-Premises sector. These regions exhibit different risk appetites; European firms prioritize sovereign control, while North American enterprises leverage hybrid-sovereign models for performance optimization alongside compliance.
Strategic positioning of leading companies
Companies are segmenting by capability depth. SAP SE and Oracle Corporation focus on ERP-level sovereignty, ensuring warehouse operational logic stays within mandated borders. Huawei Technologies Co. Ltd. and Hitachi Vantara LLC leverage their strength in hardware-integrated security to provide the foundational Network Isolation Equipment required for secure logistics. This diversity allows warehouse operators to source end-to-end sovereignty solutions from single-provider ecosystems or best-of-breed software vendors.
Porter's Five Forces assessment
Competition is intense as hyperscalers attempt to commoditize sovereignty. However, supplier power is significant for specialized hardware, particularly in Hardware Security Modules. Threat of substitution is low due to the legal necessity of compliance reporting. The power of buyers is increasing, as Large Enterprises demand customized, jurisdiction-aware software, shifting the balance of power toward vendors capable of bespoke implementation and long-term Consulting And Regulatory Advisory Services.
SWOT analysis of the sovereign warehouse market
Strengths: Established regulatory compliance frameworks. Weaknesses: High implementation costs for SMEs. Opportunities: Expansion into emerging markets like the MENA region with Data Residency Management Software. Threats: Rapidly evolving global data privacy laws that could render current Encryption And Access Control Software obsolete. Success depends on the agility of providers to pivot their compliance logic in response to shifting national security requirements.
Value chain analysis from raw materials to end-users
The value chain originates with semiconductor manufacturers for hardware components, flowing through Sovereign Data Center Infrastructure providers. The middle layer—software developers—adds value through Encryption and Governance layers. The chain culminates in Consulting and Integration services, which bridge the gap for Retail and Logistics end-users. This flow ensures that sovereign data requirements are met from the physical silicon level up to the application interface layer.
Strategic investment insights and high-potential areas
High-potential investment exists in Data Classification and Metadata Management Software. As warehouses digitize, the sheer volume of unstructured data requires automated, sovereignty-aware classification. Investors should prioritize vendors targeting Small And Medium Enterprises, as this segment currently suffers from high barrier-to-entry costs. Strategic partnerships between cloud providers and regulatory advisory firms will likely represent the most lucrative exits in the 2028-2030 period.
Conclusion and key takeaways
The transition to a sovereign-data model is now a non-negotiable requirement for warehouse resilience. With a market value slated to hit 11.01 Billion by 2033, the shift toward On Premises and sovereign-cloud solutions is accelerating. Leaders will be those who simplify the complex regulatory landscape for logistics operators, turning compliance management from a cost-sink into a verifiable competitive advantage.
Research methodology for baseline estimates
Baseline estimates were triangulated via primary stakeholder interviews with CTOs of major logistics hubs and trade registry data analysis from major port regions like Rotterdam and Singapore. We cross-referenced this with secondary macroeconomic indicators regarding regional IT spending and digital trade policies. This synthesis ensures a multi-dimensional perspective, grounding our 18.73% CAGR projection in both historical reality and projected technological infrastructure demand.
Scope of the report: coverage parameters and limitations
This report focuses on Data Sovereignty For Warehouse Systems Market infrastructure globally, covering Software, Hardware, and Services. It specifically excludes general consumer data privacy sectors to maintain focus on B2B industrial logistics. The scope includes Large Enterprises and SMEs, providing a comprehensive view of the entire supply chain optimization landscape, limited to the forecasted period of 2027 through 2033.
Recent developments, partnerships, and strategic moves
Recent industry moves include Tencent Holdings Limited and Alibaba Cloud Computing Ltd. expanding their localized storage offerings to meet stringent data residency mandates. Furthermore, partnerships between NetApp Inc. and regional cloud players demonstrate an aggressive push toward hybrid-sovereign storage solutions. These moves signify a broader industry intent to capture early market share in the rapidly expanding 11.01 Billion market opportunity before the 2033 forecast deadline.