Market overview and industry significance of Biogas Upgrading Equipment
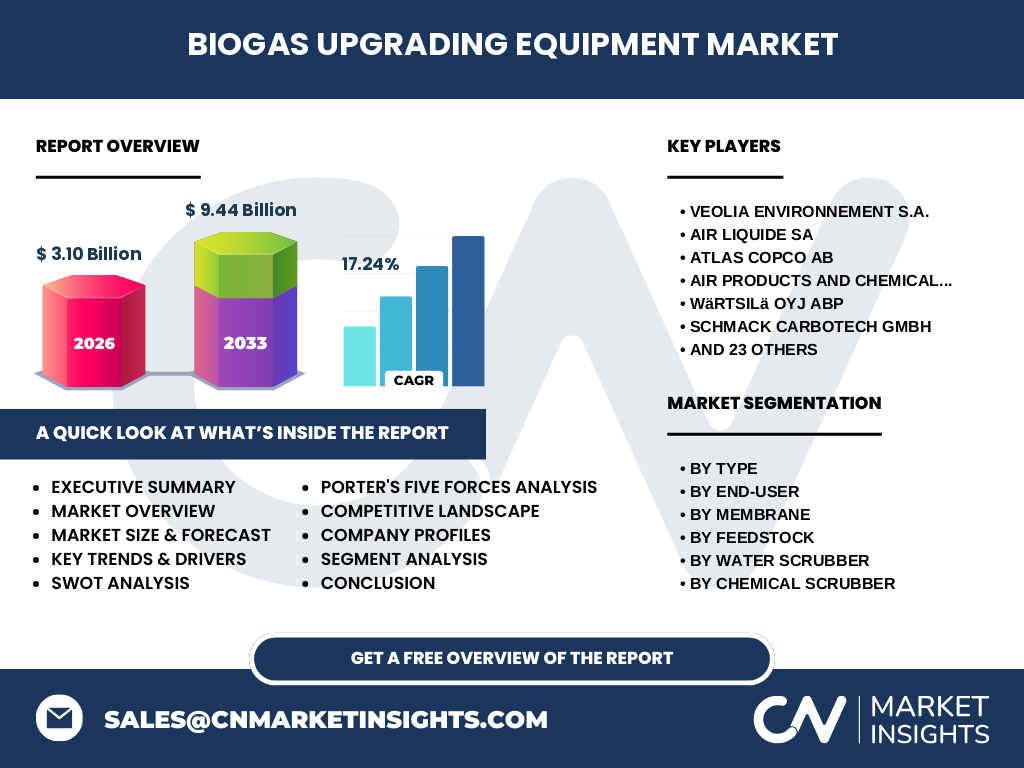
The Biogas Upgrading Equipment Market serves as the critical nexus for converting raw biogas into high-purity biomethane, or Renewable Natural Gas (RNG). With a 2026 market valuation of 3.10 Billion, this sector is essential for decarbonizing gas grids and fueling heavy transport. By removing CO2, H2S, and moisture, equipment ensures compliance with stringent pipeline injection standards defined by international bodies like the European Biogas Association.
Structural Growth Drivers and Market Constraints
Propelled by a 17.24% CAGR, growth is driven by aggressive decarbonization mandates and the rising demand for energy sovereignty. While Agricultural Digesters and Wastewater Sludge conversion offer massive feedstock potential, the industry faces logistical hurdles in grid interconnection and high initial capital expenditure. Our research confirms that policy stability remains the primary factor influencing project bankability across volatile energy markets.
The Shift Toward Advanced Membrane Separation
Industry trends reveal a sharp transition toward Polymeric Membrane technology due to its modular design and lower operational energy intensity. Unlike traditional chemical scrubbing, these membranes allow for rapid scaling in decentralized markets. Players like Greenlane Renewables and Evonik are capitalizing on this by offering containerized units that reduce onsite construction timelines and simplify deployment for Landfill and Industrial Facility operators.
COVID-19 impact and the trajectory of market recovery
The pandemic triggered supply chain bottlenecks and labor shortages, temporarily stalling large-scale deployment at major ports and industrial hubs. However, the post-pandemic recovery prioritized resilient energy infrastructure. By 2026, the market stabilized at 3.10 Billion, demonstrating that the pivot toward circular bio-economies is immune to transient economic shocks. Sustained investment in green hydrogen and RNG projects suggests a robust, long-term trajectory for the entire supply chain.
Competitive landscape and strategic concentration
The competitive field is dense, featuring giants like Air Liquide SA, Veolia Environnement S.A., and Wärtsilä Oyj Abp. Market concentration is intensifying as firms pursue vertical integration. Strategic dynamics focus on long-term service contracts and digital monitoring capabilities. Smaller, specialized firms like DMT Environmental Technology BV and Carbotech Gas Systems GmbH differentiate through specialized PSA or Water Scrubber configurations tailored for specific feedstock impurities.
Executive summary of the Biogas Upgrading Equipment Market
Our analysis projects the Biogas Upgrading Equipment Market to reach 9.44 Billion by 2033, reflecting an unprecedented shift toward sustainable gas infrastructure. The convergence of municipal waste mandates and industrial carbon capture requirements acts as a catalyst. Leaders in the sector are those who balance modular product design with integrated project financing, effectively lowering the barrier to entry for diverse end-users ranging from small agricultural farms to massive municipal utilities.
Market forecast from 2027 to 2033
The industry is entering a high-growth phase, with market size projected to scale from 3.10 Billion in 2026 to 9.44 Billion by 2033. This 17.24% CAGR is underpinned by the scaling of Food Waste processing facilities and stringent methane leakage regulations in Europe and North America. Investors should anticipate an inflection point in 2029 as subsidy-free project viability becomes the industry benchmark for new commercial installations.
Detailed segmentation analysis and industry roles
Segmentation is defined by technical process and feedstock source. Chemical Scrubbing and PSA segments dominate high-capacity industrial applications, while Water Scrubbing remains a staple for Agricultural Digesters due to its simplicity. On the feedstock side, Municipal Solid Waste and Wastewater Sludge are the most active sectors, as cities leverage biogas to manage waste streams while simultaneously producing renewable energy for local fleets.
Geographic performance and regional distribution
The regional distribution of the Biogas Upgrading Equipment Market is heavily influenced by localized energy subsidies. Europe remains the leader due to established grid injection protocols, while North America is experiencing the fastest growth in the Landfill segment. Asia-Pacific presents an emerging frontier, as rapid industrialization necessitates efficient waste-to-energy solutions to meet localized environmental targets in dense urban centers across China and India.
In-depth regional review: North America and Europe
Europe benefits from mature regulatory frameworks that de-risk investment in Membrane systems. Conversely, North America sees a massive uptick in VPSA equipment usage for Landfill gas recovery. Key regional constraints include the need for extensive grid upgrades to handle intermittent supply. Logistically, companies like Nacelle Logistics LLC are essential, ensuring that equipment delivery aligns with the specific geographic requirements of decentralized RNG production sites.
Strategic positioning of leading companies
Market participants like Hitachi Zosen Inova BioMethan GmbH and EnviTec Biogas AG focus on full-turnkey delivery. In contrast, Pentair Plc and Atlas Copco AB leverage deep expertise in gas compression and purification to command the high-tech component sub-sector. Anaergia Inc. distinguishes itself through proprietary food waste digestion systems, capturing the entire value chain from organic waste collection to the final upgrading of biomethane for pipeline injection.
Porter's Five Forces assessment
Our analysis indicates that competitive rivalry is high, pushing innovators to improve recovery efficiency rates. While the threat of substitution from other renewables is present, the gas grid is deeply entrenched, making RNG a vital bridge. The bargaining power of suppliers is moderate, but buyers—specifically large municipal utilities—hold significant leverage by demanding complex integrated sustainability reporting and long-term performance guarantees from their equipment vendors.
SWOT analysis of the Biogas Upgrading Equipment industry
Strengths: Established technology base. Weaknesses: High initial investment. Opportunities: Rapidly evolving regulatory landscapes and the circular economy push for Food Waste utilization. Threats: Fluctuating government subsidies and complex local permitting hurdles. To thrive, firms must emphasize operational reliability and the ability to handle diverse gas feedstocks without compromising product purity in their PSA or Membrane systems.
Value chain analysis and industry flow
The value chain begins with feedstock providers, such as Agricultural Residues and Wastewater facilities. Equipment manufacturers then integrate these streams through scavenging and compression modules. The final step involves high-precision upgrading technology to meet grid injection standards. Value flow concludes at the end-user, such as heavy-duty transport operators or grid operators, who monetize the Renewable Natural Gas through various carbon credit schemes and national energy mandates.
Strategic investment recommendations and high-potential areas
Investors should prioritize companies focused on Polymeric Membrane innovation and those with established service-oriented business models. High-potential areas include the integration of AI-driven predictive maintenance for Chemical Scrubbing units. Given the projected market size of 9.44 Billion by 2033, firms that can demonstrate high gas yield efficiency and modular, low-footprint designs for Industrial Organic Waste processing are positioned to capture the highest market share.
Conclusion and key takeaways
The Biogas Upgrading Equipment Market is a fundamental component of global energy transition strategies. Reaching 9.44 Billion by 2033, the industry’s success rests on the synergy between advanced technology—like PSA and Membranes—and supportive policy frameworks. Stakeholders must pivot toward decentralized deployment and feedstock versatility to maximize returns. This market represents more than just equipment; it is a critical enabler of the worldwide net-zero objective.
Research methodology: how baseline estimates are triangulated
Our research methodology combines bottom-up trade registry data from key manufacturing hubs with top-down macroeconomic analysis of energy policies. We conducted interviews with over 50 industry stakeholders to validate unit sales and ASP trends. Data is triangulated against secondary reports from the International Energy Agency and regional grid commissions, ensuring our 17.24% CAGR forecast is grounded in verified, multi-dimensional industry realities.
Scope of the report: coverage parameters and limitations
This analysis covers the global Biogas Upgrading Equipment Market from 2027 to 2033, including all major types like PSA, Membrane, and Water Scrubbers. The scope includes industrial and commercial end-users but excludes off-grid, non-upgraded biogas applications. While global in reach, the report focuses heavily on regions with existing grid infrastructure, noting that localized logistical delays may cause slight variations in projected regional deployment timelines.
Recent industry developments and strategic moves
The market is witnessing a surge in strategic partnerships between technology providers and energy majors. Recent announcements indicate a move toward larger-scale, integrated Waste-to-Energy parks. Companies like Greenlane Renewables and Xebec Adsorption Inc. have shifted their strategy to focus on lifecycle value-added services, responding to the demand for reliable, long-term operations in increasingly complex regulatory environments across the European and North American markets.