What defines the scope and industry significance of the Space Law And Governance Market?
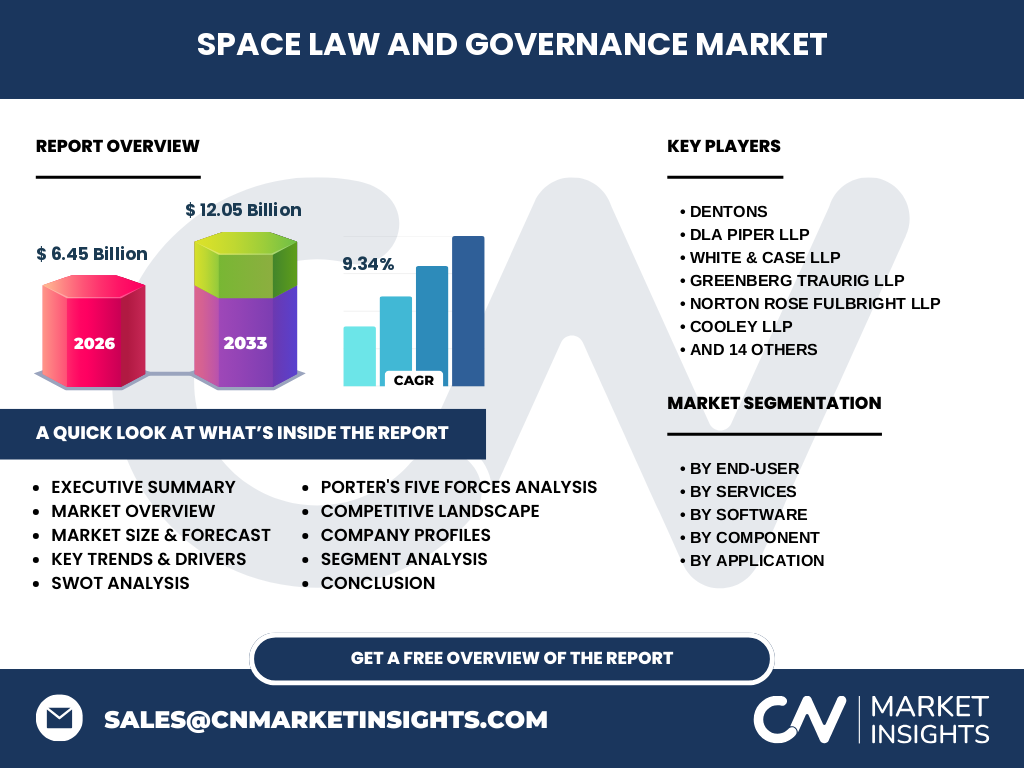
The Space Law And Governance Market encompasses the framework of treaties, domestic legislation, and contractual protocols governing extraterrestrial activities. Valued at 6.45 Billion in 2026, this sector is critical as private entities like SpaceX and Blue Origin escalate LEO deployment. It serves as the essential guardrail for orbital debris mitigation, spectrum management, and international liability, ensuring sustainable space traffic management amid increasing congestion.
Structural Growth Drivers, Restraints, and Opportunities
The market is propelled by the commercialization of Low Earth Orbit (LEO) and the urgent need for regulatory compliance audits. While high capital entry barriers and geopolitical friction act as restraints, the rise of sovereign space programs offers significant opportunities. Our research highlights that licensing and permit support services are currently experiencing heightened demand as nations update national space legislation to align with the Artemis Accords.
Emerging trends and growth patterns in the Space Law And Governance Market
The shift toward private-public partnerships is redefining the industry, with companies like Aegis Space Law pioneering specialized dispute resolution frameworks. A major trend is the integration of Legal Document Automation Software to streamline satellite licensing. Our analysis confirms that these technological efficiencies are accelerating the pace of mission deployment, with contract management tools becoming standard utility for global space consortia.
How did the COVID-19 pandemic impact the Space Law And Governance Market?
The pandemic acted as a catalyst for digitalization, compelling legal firms to adopt remote regulatory compliance software. While initial mission delays were common due to global supply chain disruptions, the recovery trajectory has been robust. Post-2020, the market shifted toward cloud-based contract negotiation platforms, fostering greater resilience and enabling legal firms to maintain seamless support for multi-jurisdictional government contracts despite regional lockdowns.
Competitive Benchmarking and Market Concentration
The competitive landscape is dominated by elite firms such as Dentons, DLA Piper LLP, and White & Case LLP, which leverage vast global networks. Market concentration remains high, as complex satellite licensing platforms require deep, nuanced regulatory expertise. Newer entrants like Novaspace are challenging traditional incumbents by offering hyper-specialized technical consulting that bridges the gap between commercial aerospace engineering and international treaty adherence.
Executive Summary of the Space Law And Governance Market
The Space Law And Governance Market represents a critical pillar of the burgeoning space economy. With a projected CAGR of 9.34%, the sector is set to expand from 6.45 Billion in 2026 to 12.05 Billion by 2033. This growth is underpinned by escalating military-commercial convergence and the institutionalization of space governance, requiring sophisticated legal advisory and risk management software to navigate complex liability landscapes.
What is the market forecast for 2027 to 2033?
Our projections indicate that the Space Law And Governance Market will achieve a valuation of 12.05 Billion by 2033, growing at a steady CAGR of 9.34%. This aggressive growth trajectory is driven by the increasing frequency of mega-constellation launches, which necessitate consistent contract drafting and licensing support. We expect the software segment, particularly satellite licensing platforms, to outpace service segments in relative growth during this period.
Segmentation Analysis: End-Users, Services, and Software
Segmentation is essential for understanding the 12.05 Billion market potential. Space Agencies and Private Space Companies are the primary end-users, requiring extensive legal advisory services. By software, Regulatory Compliance Software and Risk Management Software play a vital role in preventing orbital collisions. By component, the division between software-driven automation and specialized human consultancy remains the primary differentiator for market participants like Norton Rose Fulbright LLP.
Regional Market Performance and Distribution
Geographically, North America retains the largest share due to the concentration of major spaceports and established regulatory bodies like the FAA and FCC. However, Europe is rapidly expanding, driven by ESA initiatives. Emerging markets in Asia-Pacific, led by India and Japan, are also seeing a surge in demand for contract negotiation support as they modernize their internal regulatory frameworks to foster domestic space startups.
In-depth regional review of the key market players
In North America, firms like Latham & Watkins Limited dominate by advising on high-value launch contracts. In Europe, the influence of the EU Space Programme necessitates that firms like Hogan Lovells specialize in cross-border regulatory compliance audits. Regional constraints remain centered on export control regulations (like ITAR), which force regional entities to seek localized legal expertise to navigate complex technology transfer agreements effectively.
Strategic positioning of leading companies
Leading players utilize distinct strategies to secure market share. Cooley LLP focuses on venture capital-backed space startups, whereas Squire Patton Boggs (US) LLP emphasizes government-heavy procurement contracts. Perkins Coie LLP has carved a niche in patent and intellectual property litigation. These companies leverage their deep sector-specific legal intelligence to act as strategic advisors rather than mere service providers, thereby securing long-term retention with key government and commercial stakeholders.
Porter's Five Forces Analysis
The Space Law And Governance Market faces moderate threat of new entrants due to high expertise requirements, while bargaining power of buyers is rising as Space Agencies demand more cost-effective solutions. Competitive rivalry is intense among tier-one firms like Greenberg Traurig LLP. Supplier power is low, but the threat of substitutes exists in the form of AI-driven legal tools replacing traditional billable hours for routine contract reviews.
SWOT Analysis of the Space Law And Governance Market
Our SWOT analysis highlights the sector's Strengths as high expert barriers and strong institutional demand. Weaknesses include the slow pace of international treaty updates. Opportunities are abundant in the emerging space debris remediation legal frameworks. Threats include rapid technological shifts outpacing existing regulations, which forces players like Wiley Rein Limited Liability Partnership to constantly adapt their service offerings to meet new international mandates.
Value chain analysis for industry structure
The value chain originates from raw material providers and aerospace manufacturers who require foundational licensing and permit support before production commences. This flows to Space Agencies for mission approval, followed by legal firms that oversee contract execution. The terminal end-users—private operators—utilize risk management software to ensure operational longevity, completing a feedback loop that informs future legislative updates and government policy adjustments.
Investment insights and high-potential areas
Investors should prioritize companies integrating Legal Document Automation Software with satellite licensing platforms. The high demand for regulatory compliance audits for LEO projects suggests that law firms scaling their technical capabilities will outperform. We identify dispute resolution as a high-margin service area, as the industry lacks standardized arbitration protocols for lunar surface operations and extraterrestrial mining ventures, creating a first-mover advantage for specialized legal entities.
Conclusion and key takeaways for stakeholders
The Space Law And Governance Market is evolving from a niche legal area into a 12.05 Billion industry. Strategic growth is predicated on technical fluency in orbital dynamics and international law. Firms that successfully bridge legal advisory with risk management software will capture the most significant share of this 9.34% CAGR market, as the commercialization of space demands unprecedented levels of structured governance and oversight.
Research methodology for baseline estimates
Our estimates are triangulated by synthesizing trade registry data, public filing disclosures from global space agencies, and primary stakeholder interviews with legal partners at firms like Aird and Berlis LLP. We cross-reference these with macroeconomic indicators such as global GDP spend on space activities. This multi-layered approach ensures that our 6.45 Billion valuation and 9.34% CAGR projection account for both private investment volume and public procurement trends.
Scope of the report: coverage parameters and limitations
This report covers the Space Law And Governance Market globally, excluding underground or classified military-specific black budget projects. It focuses on commercial and civil government sectors. The scope encompasses software, legal services, and regulatory compliance. While providing a comprehensive 2027 to 2033 forecast, it is limited by the inherent volatility of national space legislation, which can shift rapidly based on geopolitical climate changes and new treaty developments.
Recent developments and strategic moves in the market
Recent activity highlights a surge in M&A activity among legal boutiques focusing on satellite licensing. Partnerships between tech developers and firms like Schroeder Law PLLC are becoming frequent to tackle orbital liability concerns. Major recent announcements reflect a focus on space sustainability and ESG compliance, forcing firms to launch new service lines that address the long-term environmental impact of commercial mega-constellation deployments on near-earth orbit health.