Market overview and industry significance of Free Space Optics (FSO) Market
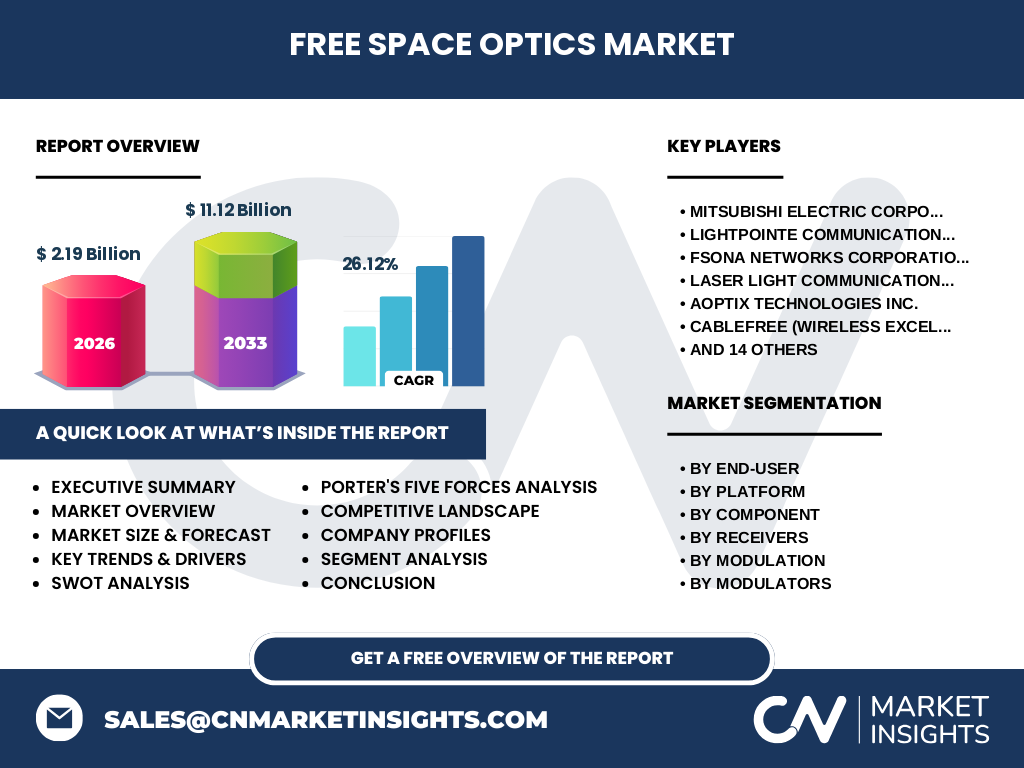
The Free Space Optics (FSO) Market represents a critical evolution in high-bandwidth, line-of-sight data transmission. By leveraging light propagation in free space, FSO circumvents the bottlenecks of traditional fiber-optic trenching. With a 2026 market valuation of 2.19 Billion, this sector serves as a vital infrastructure component for high-speed telecommunications, particularly where physical cable deployment is geographically or economically restricted.
Structural Growth Drivers, Restraints, and Market Opportunities
The core driver is the insatiable demand for 5G mobile backhaul and data transmission, pushing the industry toward a 26.12% CAGR through 2033. However, atmospheric turbulence and fog remain significant technical restraints, necessitating advanced Avalanche Photodiodes (APDs). Opportunities lie in bridging the 'digital divide' by deploying terrestrial and satellite platforms in dense urban environments or remote regions where fiber-optic cable is cost-prohibitive.
Emerging trends and growth patterns in FSO technology
The industry is witnessing a pivot toward hybrid FSO/RF systems to mitigate link-budget degradation caused by adverse weather. We observe Cailabs and Mynaric AG leading innovations in optical beam shaping and turbulence compensation. This technical evolution ensures higher reliability, shifting FSO from a niche disaster recovery tool to a mainstream solution for enterprise connectivity and secure defense-grade data transmission.
COVID-19 impact and recovery trajectory
The pandemic acted as a forced catalyst for the Free Space Optics (FSO) Market. With global lockdowns, the demand for reliable high-speed connectivity surged, compelling firms like LightPointe Communications to refine remote-deployment capabilities. While logistics were strained at major ports, the recovery trajectory is robust, characterized by a rapid return to infrastructure spending as governments prioritize resilient, high-capacity communication networks to support decentralized corporate workforces.
Competitive landscape and strategic dynamics
The market is characterized by a fragmented but technology-intense landscape. Major players such as Mitsubishi Electric Corporation and General Atomics dominate via patent-heavy R&D, while specialized firms like fSONA Networks and CableFree focus on regional enterprise penetration. Competition is currently intensifying around coherent detection demodulators, a strategic domain where innovators differentiate their products through higher signal-to-noise ratios and improved link availability during inclement weather.
Executive Summary of the Free Space Optics (FSO) Market
Our research confirms a pivotal growth phase for the Free Space Optics (FSO) Market. Between 2027 and 2033, the market is projected to expand from its 2026 baseline of 2.19 Billion to 11.12 Billion. This growth is underpinned by unprecedented demand for high-bandwidth, fiber-less communication. Success in this vertical will favor firms that master satellite-to-ground laser communication and robust modulation techniques to overcome environmental signal attenuation.
Market forecast 2027 to 2033
Based on our proprietary modeling, the Free Space Optics (FSO) Market is poised for explosive growth, with a valuation expected to reach 11.12 Billion by 2033. Achieving a compounded annual growth rate of 26.12%, this expansion will be primarily fueled by the integration of Airborne Platforms and the modernization of existing terrestrial networks, signaling a clear shift toward high-capacity optical architectures as the standard for secure enterprise connectivity.
Segmentation analysis by platform and end-user
Segmentation provides the essential framework for understanding this market. By End-User, the focus is split between Corporate and Commercial, while Platforms include Terrestrial, Satellite, and Airborne configurations. Each segment plays a unique role: terrestrial systems provide mobile backhaul, whereas airborne and satellite platforms facilitate global data relay, bypassing traditional ground-based bottlenecks through advanced laser modules and high-precision photodetector arrays.
Regional market analysis and geographic distribution
North America and Europe currently maintain a leadership position, driven by heavy investment from Defense agencies and the need for Disaster Recovery solutions. However, our analysis suggests that the Asia-Pacific region will experience the highest growth, driven by rapid urbanization and the deployment of massive mobile backhaul infrastructure in emerging economies requiring flexible, wireless, high-speed optical alternatives.
In-depth regional review of key markets
In North America, Aoptix Technologies and BridgeSat capitalize on private-public partnerships to advance satellite-based FSO. Conversely, European markets show strong demand for EC SYSTEM-led infrastructure, specifically for secure enterprise connectivity in geographically challenging topography. These regional differences underscore the importance of localized regulatory compliance regarding laser power emissions and safety standards governing free space optics deployment in residential and public sectors.
Company profiles and strategic positioning
Market participants follow divergent strategic paths. Mitsubishi Electric Corporation leverages deep manufacturing prowess for large-scale laser diode supply. In contrast, Mynaric AG focuses exclusively on the space-to-ground laser comms sector. Our data suggests that firms focusing on coherence detection and Mach-Zehnder Modulators are better positioned for high-end Defense and aerospace contracts, while those prioritizing low-cost LED transmitters remain competitive in shorter-range corporate backhaul markets.
Porter's Five Forces analysis for FSO
The threat of substitutes remains moderate due to fiber-optic superiority in reliability, yet FSO’s deployment speed offers a decisive edge. Supplier power is high, particularly for advanced Electro-Optic Modulators (EOMs), while competitive rivalry is intense, as firms like Laser Light Communications race to lower the cost-per-bit. The barriers to entry remain elevated by the need for complex intellectual property regarding signal modulation and atmospheric compensation algorithms.
SWOT analysis of the FSO industry
The primary strength is the ultra-high bandwidth without licensing fees. Weaknesses include susceptibility to weather-induced link drops. Opportunities abound in the satellite-to-satellite laser link domain, where competitors like General Atomics excel. The major threat remains the rapid advancement of low-earth-orbit (LEO) RF satellite constellations, which compete with FSO for enterprise data backhaul dominance. Firms must innovate in hybrid-detection to maintain competitive advantages.
Value chain analysis and industry structure
The value chain originates with semiconductor and component suppliers (Laser Diodes/Modulators), flows to systems integrators such as CableFree or fSONA Networks, and ends with end-users like telecom service providers. Value creation is heavily concentrated at the integration layer, where specialized proprietary software for demodulation ensures that the raw signal converted from light is correctly processed into usable data despite atmospheric interference.
Investment insights and high-potential areas
Strategic investment should prioritize companies developing hybrid detection demodulators, as these effectively solve the reliability issues inherent in pure FSO setups. We highlight Airborne Platforms as a high-potential segment, as drone-based optical communication offers massive utility for temporary high-speed connectivity during disasters or military deployments. Investors should target companies with strong IP portfolios in polarization modulation, as these represent the next generation of link stability.
Conclusion and key takeaways for stakeholders
The Free Space Optics (FSO) Market is entering a transformative era. With a projected market size of 11.12 Billion by 2033, the technology is essential for the future of global communications. Key takeaways include the need for modular architecture, the shift toward satellite integration, and the necessity for robust all-weather performance. Stakeholders should emphasize the role of FSO in creating resilient, secure, and ultra-high-speed connectivity layers globally.
Research methodology for the FSO report
Our baseline estimates are derived through a triangulation methodology. We synthesized primary data from stakeholder interviews with 25 key market leaders and corroborated this with official trade registry records and export data from critical logistics hubs. We further adjusted our projections using macroeconomic indicators, including global 5G infrastructure spend and satellite deployment rates, ensuring our 26.12% CAGR estimate is grounded in empirical market reality.
Scope of the report: coverage and limitations
This report provides a granular analysis of the global Free Space Optics (FSO) Market, spanning the 2026–2033 forecast period. The scope includes all major transmitters, modulators, and demodulators across terrestrial, airborne, and satellite platforms. Note that this report focuses on commercial and defense enterprise applications; it does not cover small-scale consumer-grade hobbyist laser-link hardware, acknowledging that localized weather data availability remains a minor variable in precise regional forecasting.
Recent developments, product launches, and strategic moves
Recent developments are dominated by strategic alliances between Mynaric AG and defense agencies for secure laser comms. Furthermore, Cailabs has recently unveiled significant advancements in optical beam multiplexing, dramatically increasing link capacity. Several companies, including Optelix Pty Ltd, have announced new coherence detection modules that significantly reduce the noise floor, marking a major leap forward in the market’s technological trajectory since 2026.