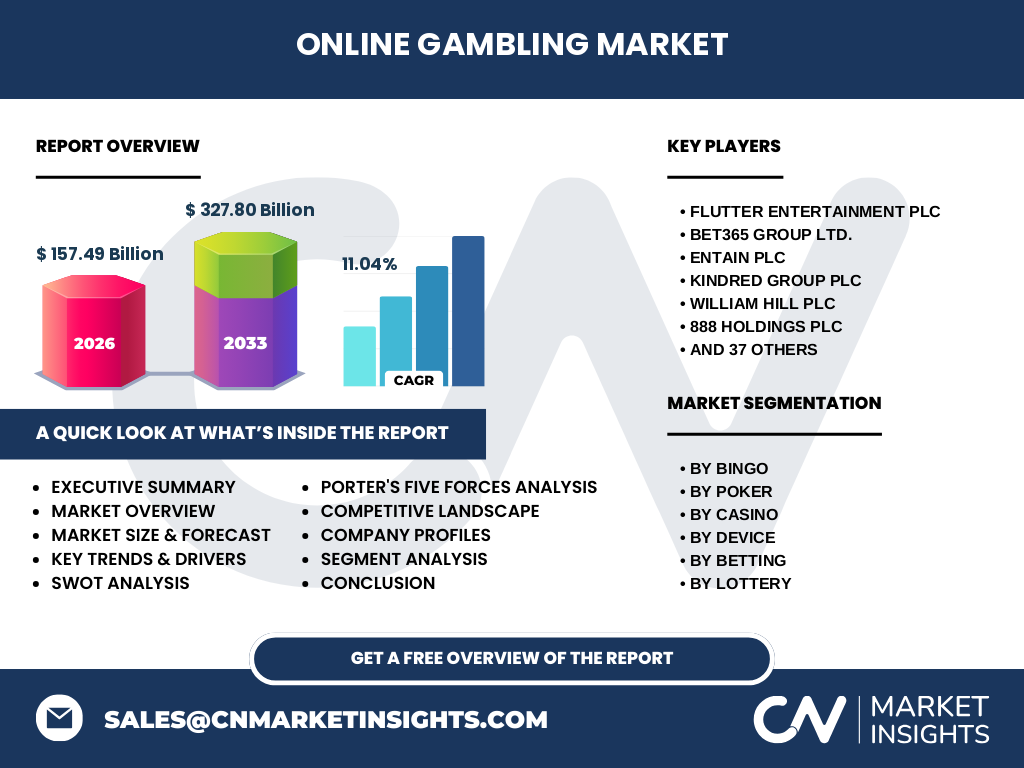
Market overview and industry significance of the Online Gambling Market
The Online Gambling Market represents a sophisticated digital ecosystem where wagering transcends physical boundaries. Valued at 157.49 Billion in 2026, the industry serves as a cornerstone of modern entertainment. It encompasses a vast spectrum, from Live Dealer Games to Sports Betting, functioning under stringent regulatory frameworks managed by entities like the UK Gambling Commission and the Malta Gaming Authority, ensuring integrity in global digital transactions.
Key market drivers, restraints, and opportunities shaping the sector
The primary growth driver is the proliferation of high-speed mobile connectivity, which facilitates seamless In-Play Betting. However, the industry faces regulatory hurdles, such as complex licensing mandates in North America and strict advertising bans in Europe. Yet, the integration of cryptocurrency payment gateways and AI-driven personalized gaming presents significant opportunities for companies like Flutter Entertainment plc to capture untapped demographics through enhanced user retention strategies.
Emerging trends and growth patterns within the industry
A transformative shift is occurring toward E-Sports Betting and hyper-personalized casino experiences. We observe that industry leaders are moving away from traditional static interfaces toward gamified mobile platforms. This trend is crucial for attracting younger cohorts, as evidenced by the strategic pivots at DraftKings Inc. and Betsson AB, who are prioritizing real-time data feeds and social betting features to maintain high engagement levels.
COVID-19 impact analysis and recovery trajectory
The pandemic acted as a catalyst for accelerated digitization, forcing land-based operators to shift resources toward online platforms. While physical venues suffered, the Online Gambling Market witnessed unprecedented adoption rates. The post-pandemic trajectory shows a sustained shift; users who migrated to digital platforms for Poker and Online Lottery have remained, solidifying the industry’s recovery through robust mobile retention and cloud-based gaming services.
Competitive landscape and strategic dynamics
The competitive landscape is characterized by high market concentration among titans such as Flutter Entertainment plc, Entain plc, and 888 Holdings PLC. These players leverage M&A strategies to consolidate market share and secure proprietary software. The market dynamic is shifting from simple customer acquisition to long-term loyalty programs, with companies like Kindred Group plc focusing on sustainability and responsible gaming to differentiate in saturated European markets.
Executive summary of key findings
The Online Gambling Market is poised for substantial expansion, reaching a projected 327.80 Billion by 2033 with a CAGR of 11.04%. Our proprietary research indicates that Mobile remains the dominant delivery device, while Live Dealer Games drive the highest revenue per user. Success in this cycle necessitates agility in navigation of global regulatory landscapes and heavy investment in cutting-edge software solutions to ensure platform security and user trust.
Projected market forecast from 2027 to 2033
Our analysis projects that the market will escalate from 157.49 Billion to 327.80 Billion by 2033, expanding at a robust CAGR of 11.04%. This growth is underpinned by the expansion of legalized sports betting in the United States and the ongoing modernization of Lottery systems in emerging markets. Strategic investments in infrastructure will allow operators to scale services efficiently across diverse jurisdictions.
Segmentation analysis of gaming products and delivery platforms
The market is expertly segmented into Casino, Betting, Lottery, Poker, and Bingo, with Mobile emerging as the primary delivery channel. Live Dealer Games serve as the high-margin segment within casinos, while Sports Betting remains the volume leader. Each segment requires distinct software logic and regulatory compliance, with firms like Evolution Gaming and Microgaming providing the essential infrastructure to support these diverse gaming categories globally.
Geographic performance and distribution
Performance varies by region, with Europe currently holding the largest market share due to mature regulation. However, North America represents the fastest-growing region, driven by legislative changes in U.S. states. Meanwhile, the Asia-Pacific market presents unique challenges due to fragmented legal frameworks, despite high demand for E-Sports Betting. Regional performance is highly correlated with the local government's stance on digital financial oversight and licensing criteria.
In-depth regional review of high-growth territories
In the United Kingdom, companies like Sky Betting & Gaming dominate through brand loyalty and advanced mobile betting apps. Conversely, the U.S. market is defined by the rapid scaling of DraftKings Inc. and BetMGM. These regions require localized content strategies to succeed. The regulatory environment in Ontario, Canada, provides a successful template for other jurisdictions looking to regulate online gambling effectively without stifling operator growth.
Strategic positioning of leading companies
Strategic positioning varies: International Game Technology PLC focuses on high-end B2B software architecture, while Betway and 1xBet prioritize aggressive consumer acquisition through extensive Sports Betting partnerships. Evolution Gaming commands the Live Dealer space, providing high-fidelity, real-time streams that act as a premium offering for casino operators. These companies differentiate themselves through technological moat building and exclusive content licensing to prevent commoditization of their gaming suites.
Porter's Five Forces assessment
The industry faces intense competitive rivalry due to low switching costs for players and high regulatory barriers to entry. Threat of substitutes is moderate, primarily from social gaming, while supplier power is significant for high-end software providers like NetEnt. Our analysis concludes that incumbents maintain their advantage through proprietary data analytics and large-scale brand marketing, effectively neutralizing the threat of new entrants in established markets.
SWOT analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths include robust digital scalability and massive user engagement. Weaknesses involve high operating costs due to regulatory compliance. Opportunities reside in emerging E-Sports Betting and untapped markets in Latin America. Threats center on potential legislative crackdowns and increased focus on anti-money laundering protocols. Success hinges on a company's ability to balance aggressive market capture with stringent responsible gaming compliance in every jurisdiction of operation.
Value chain analysis of the industry structure
The value chain initiates with Software Developers (e.g., Play'n GO, Microgaming), who create the core gaming engines. This flows to Aggregators and Operators like Ladbrokes Coral, who manage customer relationships, payments, and localized marketing. The final stage is the End-User, interacting through Mobile or Desktop interfaces. The integration of payment processors and regulatory audit firms ensures the integrity and flow of capital throughout the entire lifecycle.
Strategic investment insights and high-potential areas
We recommend focusing investment on B2B infrastructure providers and companies with strong local market penetration. High-potential areas include E-Sports Betting platforms and companies leveraging AI-driven personalization to increase player lifetime value. Strategic investors should look for firms with diversified portfolios across different gaming segments to mitigate risk from regulatory shifts in specific product categories like Instant Win Games or Scratch Cards.
Conclusion and key takeaways
The Online Gambling Market is in a period of rapid evolution, projected to reach 327.80 Billion by 2033. The winners in this space will be firms that effectively bridge the gap between technological innovation and regulatory compliance. Key takeaways include the dominance of mobile platforms, the importance of live gaming experiences, and the necessity of data-driven user engagement to navigate an increasingly competitive and scrutinized global landscape.
Research methodology for baseline estimates
Our estimates are triangulated using a hybrid approach. We synthesize trade registry data, public financial disclosures from major operators, and primary stakeholder interviews with C-suite executives across the industry. These are reconciled with secondary macroeconomic indicators and regional regulatory reports. This multi-layered methodology ensures our 11.04% CAGR projection is grounded in hard evidence, providing a reliable foundation for stakeholders planning their 2027-2033 strategic initiatives.
Scope of the report and coverage parameters
This report covers the global Online Gambling Market, excluding non-regulated or illicit gaming ecosystems. The scope includes Casino, Betting, Lottery, Poker, and Bingo segments across major global regions. Limitations include the difficulty of tracking grey-market activity and the variability of localized digital data. The report focuses on formalized enterprise operations and major technology providers, ensuring accuracy and utility for professional market participants and institutional investors.
Recent developments in the industry
Recent strategic moves highlight industry consolidation and technological partnership expansion. Companies like Evolution Gaming continue to launch innovative Live Dealer variants, while Scientific Games focuses on lottery modernization. Additionally, partnerships between media houses and Sports Betting operators are becoming the standard to drive lower acquisition costs. These developments underscore a trend toward integrated ecosystems where content, payment processing, and media visibility converge to capture long-term player retention.