Market overview and industry significance of the Immersive Virtual Stores Market
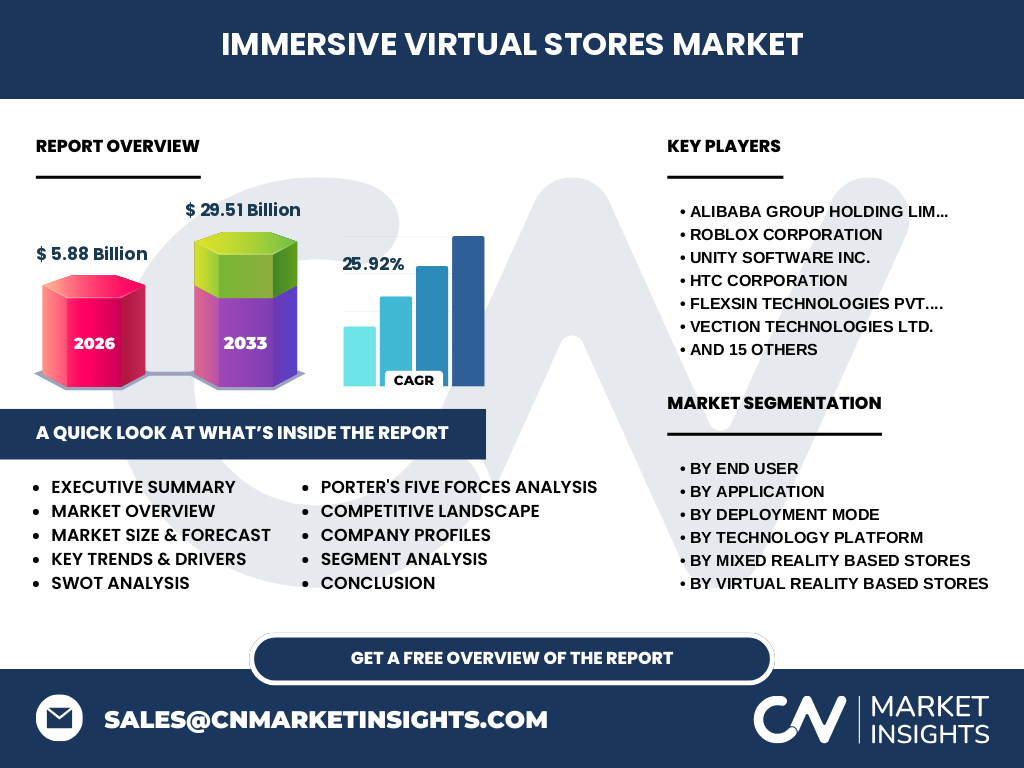
The Immersive Virtual Stores Market represents a paradigm shift in digital retail, transitioning from static e-commerce pages to 3D, interactive environments. With a 2026 market size of 5.88 Billion, this sector is critical for global brands aiming to increase customer dwell time. By leveraging spatial computing and VR, retailers move beyond traditional flat layouts to create brand-immersive digital ecosystems that mimic physical tactile experiences.
Structural growth drivers, restraints, and strategic opportunities
Primary growth is fueled by rising mobile penetration and consumer demand for gamified shopping experiences. While high development costs for hardware remain a restraint, the opportunity lies in Web-Based Three Dimensional Stores that require no downloads. Our analysis suggests companies that bridge the gap between Augmented Reality mobile utility and high-fidelity cloud-based infrastructure are best positioned to capture market share.
Emerging trends and growth patterns shaping the industry
We are observing a massive pivot toward no-download instant access stores powered by game engines. This trend democratizes access, allowing consumers to enter virtual boutiques directly via browser links. Interactive blended reality is also gaining traction, particularly in high-end fashion, where brands like Emperia Ltd. and Obsess Inc. are pioneering seamless 3D storefronts that drive significant conversion uplifts compared to legacy platforms.
COVID-19 impact analysis and recovery trajectory
The pandemic acted as a force multiplier for the Immersive Virtual Stores Market, forcing a rapid transition to remote digital commerce. While initial growth was reactionary, the recovery trajectory has stabilized into a strategic investment phase. Brands now view virtual infrastructure not as a temporary bridge, but as a long-term omnichannel asset essential for surviving shifting regional consumer behaviors.
Competitive landscape and strategic market dynamics
The competitive landscape is highly fragmented, featuring tech-giants like Alibaba and Unity Software Inc. alongside specialized innovators such as ByondXR Ltd. and rooom GmbH. Strategic dynamics are shifting toward platform interoperability. Market concentration remains moderate as firms vie to set the standard for spatial computing, forcing smaller players to find niches in specific verticals like luxury fashion or automotive configuration.
Executive summary of the Immersive Virtual Stores Market
The Immersive Virtual Stores Market is poised for explosive growth, forecasted to reach 29.51 Billion by 2033 at a CAGR of 25.92%. Our research highlights that moving from 2D catalogs to 3D interactive environments is the next frontier of retail competition. Success in this sector requires balancing high-fidelity visuals with cross-platform accessibility, ensuring that brands reach consumers across both desktop and mobile devices.
Market forecast from 2027 to 2033
Driven by sustained adoption, the market is projected to expand from 5.88 Billion in 2026 to a robust 29.51 Billion by 2033. This reflects a steady CAGR of 25.92%, underpinned by increased enterprise investment in holographic device enabled stores and browser-rendered interfaces. We expect a strategic tipping point around 2029 as 5G network maturation reduces latency for high-bandwidth 3D assets globally.
Segmentation analysis by end-user and application
The market is segmented by end-users including Retailers, Fashion Brands, and Real Estate Companies. Fashion and Apparel remain the most aggressive adopters due to the need for virtual try-on solutions. Conversely, Real Estate is leveraging spatial computing for interactive walkthroughs. This segmentation allows for targeted technology deployment, ensuring that the specific VR or AR platform aligns perfectly with the unique consumer journey of each vertical.
Regional performance and geographic distribution
North America and Europe currently lead, driven by the concentration of metaverse-ready tech hubs and high-speed infrastructure. However, the Asia-Pacific region is emerging as a high-growth zone. Localized market constraints, such as varying regulatory approaches to data privacy and digital assets, dictate regional adoption speeds. Companies like HTC Corporation are leveraging localized presence to navigate these specific geographic nuances effectively.
In-depth review of regional market dynamics
In North America, Consumer Electronics Companies are pushing the limits of Headset Dependent Full Immersion Stores. In contrast, emerging Asian markets prioritize Mobile Application Augmented Reality Stores due to mobile-first consumer habits. Understanding these regional shifts is vital for developers; for instance, marketing 3D stores in markets with lower high-end headset penetration requires a focus on Browser Rendered Three Dimensional Stores for broader accessibility.
Company profiles and strategic positioning
Market participants like Roblox Corporation and Decentraland Foundation are positioning themselves as foundational metaverse platforms, while firms like Flexsin Technologies and Trigma Solutions focus on custom enterprise integration. ByondXR Ltd. distinguishes itself through proprietary e-commerce platform integration, enabling seamless transition for retailers. This mix of platform-builders and specialized developers ensures a comprehensive ecosystem capable of servicing diverse technical requirements.
Porter's Five Forces assessment of the market
Our assessment shows high competitive rivalry as firms compete for early-mover status in 3D retail. Supplier power is moderate, resting with game engine providers, while the threat of substitutes remains low for brands requiring true 3D immersion. Barriers to entry are defined by technological complexity, favoring companies that can offer no-download, platform-agnostic solutions that bypass hardware limitations for the average consumer.
SWOT analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths: Superior engagement metrics compared to 2D web. Weaknesses: High development cost for Room Scale Interactive Stores. Opportunities: Integration of generative AI to populate virtual spaces dynamically. Threats: Data privacy regulations (like GDPR) and hardware fragmentation. Overall, the ability to iterate rapidly through Cloud-Based deployments serves as a critical strategic advantage for firms navigating this volatile technological landscape.
Value chain analysis and industry structure
The value chain begins with hardware and platform developers, moves through software integration agencies (like iCreative Technologies), and ends with the retailer's end-customer. Value flow is heavily skewed toward developers who provide cloud-based, low-latency rendering. As industry standards for 3D assets solidify, we expect higher commoditization of backend tools, allowing agencies to focus on high-margin, bespoke user experience design.
Investment insights and strategic recommendations
Investors should target companies bridging Web-Based Three Dimensional Stores and e-commerce backends. The data supports high-potential in AR-markerless solutions, which require no specialized hardware for the user. We recommend focusing on firms that offer modular, scalable storefronts rather than heavy, monolithic custom builds, as scalability remains the primary hurdle for large-scale enterprise adoption in the 2027-2033 period.
Conclusion and key takeaways
The Immersive Virtual Stores Market is an inevitable evolution of digital commerce. With a forecasted 29.51 Billion valuation by 2033, the market offers massive upside for stakeholders who prioritize user accessibility and cross-platform compatibility. The transition to 3D is not merely aesthetic; it is a fundamental shift toward higher conversion and deeper brand loyalty in a saturated global digital marketplace.
Research methodology and triangulation strategy
Our research methodology employs a triangulation approach, combining trade registry filings, proprietary primary stakeholder interviews with industry lead developers, and secondary macroeconomic indicators. We cross-reference company product launches with regional retail traffic data to validate growth estimates, ensuring that the 25.92% CAGR reflects authentic market trends rather than mere theoretical projections based on optimistic vendor hype.
Scope of the report and technical parameters
This report encompasses global market trends across four primary technology platforms: VR, AR, MR, and 3D Web. We focus on deployment modes ranging from on-premises to cloud-native, specifically excluding speculative non-commercial metaverse projects. The scope covers major segments, including Fashion, Real Estate, and Electronics, providing a granular view of the technical requirements and investment necessary for market entry between 2027 and 2033.
Recent developments, partnerships, and product launches
Recent activity highlights a surge in partnership-driven growth, as firms like Pixelette Technologies and Innowise Group announce strategic collaborations to optimize cross-engine compatibility. Furthermore, the launch of mobile-optimized Markerless Augmented Reality Stores by key innovators signifies a pivot toward mass-market accessibility. These developments reinforce our forecast, demonstrating that the market is rapidly moving toward standardization and high-frequency deployment for mid-to-large tier retail brands.