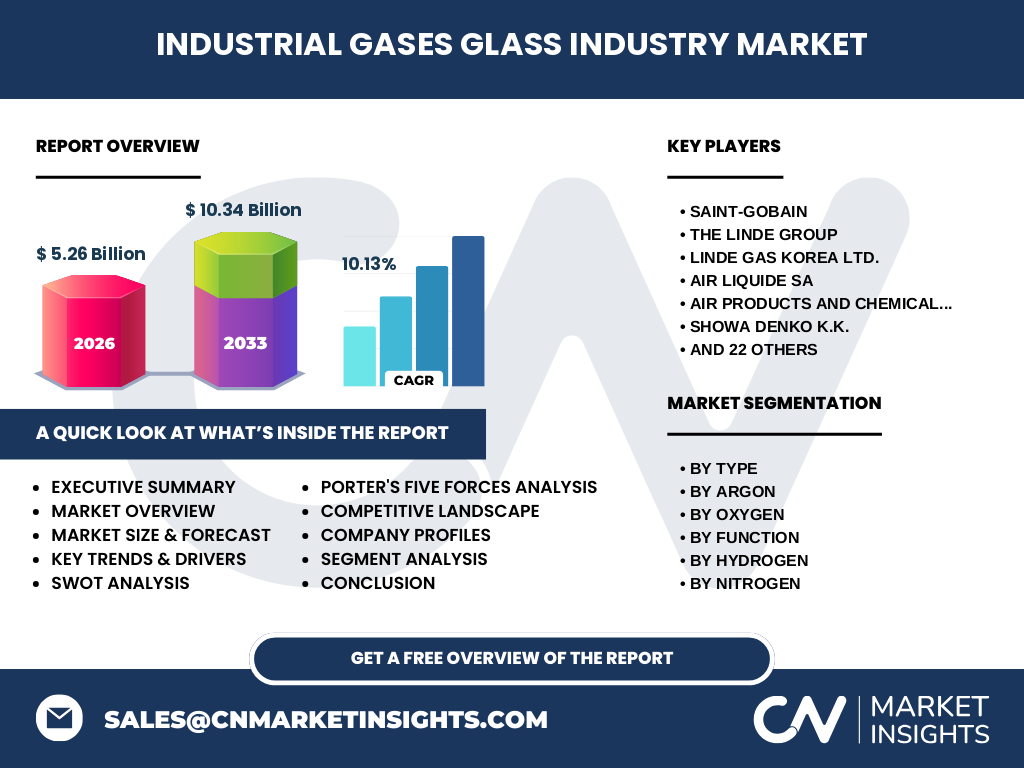
Market overview of the Industrial Gases-Glass Industry Market
The Industrial Gases-Glass Industry Market is a critical upstream sector, currently valued at 5.26 Billion in 2026. It encompasses the supply of high-purity gases like Oxygen, Nitrogen, and Hydrogen, which are indispensable for glass melting, atmospheric control, and surface polishing. Our research shows this market acts as the backbone of modern glass manufacturing, ensuring thermal efficiency and material purity for global production cycles.
Structural Growth Drivers, Restraints, and Opportunities
Growth is propelled by rising demand for fiber glass and energy-efficient float glass, leading to a projected 10.34 Billion valuation by 2033. While high capital expenditures for tonnage distribution systems act as a barrier, the transition toward decarbonization in furnace firing creates immense opportunities. Companies capable of integrating low-carbon hydrogen solutions are positioned to outpace traditional market incumbents.
Emerging trends and growth patterns shaping the sector
The shift toward oxy-fuel combustion technology is a dominant trend, significantly reducing NOx emissions. We observe an increasing reliance on specialty gas mixtures for thin-film glass coatings. Furthermore, digitalization of gas supply management via IoT-enabled tonnage distribution is helping manufacturers like Saint-Gobain and Air Liquide SA optimize operational efficiency and minimize downtime in their glass forming lines.
COVID-19 impact analysis and recovery trajectory
The pandemic caused initial supply chain turbulence in the Industrial Gases-Glass Industry Market, particularly affecting cylinder and packaged gas distribution due to logistic lockdowns. However, the subsequent rebound in demand for construction-grade flat glass and pharmaceutical vials accelerated the recovery. Our analysis suggests that the industry demonstrated resilient growth recovery, returning to a robust upward trajectory with a projected 10.13% CAGR.
Competitive landscape and strategic dynamics
The market is highly concentrated, with dominant players like The Linde Group, Air Products and Chemicals Inc., and Messer Group GmbH leveraging global infrastructure. Strategic dynamics involve aggressive capacity expansion in key manufacturing hubs. Smaller, regional entities like Osaka Sanso Co. Ltd. and Kyushu Air Gas Co. Ltd. compete by offering localized, flexible merchant liquid distribution, effectively serving niche specialty glass producers.
Executive summary of the Industrial Gases-Glass Industry Market
The Industrial Gases-Glass Industry Market is poised for significant expansion, climbing from 5.26 Billion in 2026 to 10.34 Billion by 2033. Driven by industrial evolution and a 10.13% CAGR, the market is transforming toward high-purity, sustainable gas solutions. This executive synthesis confirms that energy optimization and supply chain integration are the primary determinants of competitive success for stakeholders and investors alike.
Market forecast from 2027 to 2033
Our projections indicate that the market will maintain a steady 10.13% CAGR through 2033. By reaching 10.34 Billion, the market reflects sustained demand for high-performance glass in the automotive and architectural sectors. We anticipate that tonnage distribution will become the preferred model for large-scale float glass operations, providing the economies of scale necessary to support long-term revenue growth.
Segmentation analysis by type and function
Market segments include critical gases like Oxygen, Nitrogen, Argon, Hydrogen, and Acetylene. By function, these gases support Forming and Melting, Atmospheric Control, and Finishing or Polishing. Each segment plays a vital role; for instance, Nitrogen is essential for preventing oxidation in specialty glass, while Oxygen is the primary driver for achieving the high furnace temperatures required in modern glass manufacturing.
Regional market analysis and performance
Geographically, the Asia-Pacific region holds a significant share, bolstered by massive glass manufacturing clusters in China, South Korea, and India. Key players like Linde Gas Korea Ltd. and Yingde Gases Group dominate these zones. European and North American markets remain mature, focusing on high-value specialty glass and stringent environmental compliance, which drives the demand for cleaner, more efficient industrial gas delivery systems.
In-depth regional review
In the South Korean market, companies like Nippon Gases Korea Co. Ltd. and Woomjin Precision Gas Co. Ltd. provide essential supply for regional tech-glass giants. Meanwhile, the Indian market, supported by IGC India Ltd., is seeing rapid scaling in fiber glass production. These regional dynamics are heavily influenced by proximity to ports and the logistical ease of merchant liquid distribution systems.
Strategic positioning of leading companies
Leading companies utilize distinct strategic positions: Air Liquide SA and The Linde Group focus on global scale and innovation in decarbonization. Conversely, firms like Air Water Inc. and Iwatani Corporation maintain strong regional defensive moats. CRYOTECH Anlagenbau GMBH specializes in engineered solutions, providing the technological infrastructure needed for complex gas management in high-end specialty glass facilities.
Porter's Five Forces analysis
The Industrial Gases-Glass Industry Market features moderate rivalry due to the high barrier to entry for tonnage distribution infrastructure. Buyer power is high among large-scale float glass manufacturers, yet supplier power is significant for specialty gas providers. The threat of substitutes is low, as no other medium can effectively replace industrial gases for critical melting and atmospheric control processes in modern glass production.
SWOT analysis of the industry
The market's Strengths include robust demand in the construction and automotive sectors. Weaknesses lie in high energy and logistical costs. Opportunities emerge from the shift to green hydrogen for furnace firing, while Threats involve volatile raw material prices and tightening environmental regulations imposed by bodies such as the EU or local environmental protection agencies, forcing operators to innovate rapidly or lose market share.
Value chain analysis from raw materials to end-users
The value chain originates from Air Separation Units (ASUs) and chemical synthesis. Gases are processed, stored, and transported via tonnage, merchant liquid, or cylinder delivery. End-users in container, float, fiber, and specialty glass utilize these gases for refined manufacturing. The flow emphasizes operational safety and precision, as impurities in gases can directly compromise the structural integrity and optical clarity of the final glass product.
Investment insights and high-potential areas
Investors should target companies leading in green hydrogen integration and advanced tonnage distribution services. We identify fiber glass production as a high-growth segment due to its application in wind energy and construction materials. Strategic partnerships with regional players like Gulf Cryo Industrial Gases LLC offer promising entry points for investors looking to capitalize on the rapid industrialization of emerging glass manufacturing hubs.
Conclusion and key takeaways
The Industrial Gases-Glass Industry Market is a high-growth sector set to hit 10.34 Billion by 2033. Key takeaways include the undeniable shift toward sustainable gas application and the continued dominance of large-scale, efficient supply chain models. Success in this market is predicated on balancing technological innovation in gas usage with resilient, cost-effective logistical infrastructure to meet the evolving needs of the glass manufacturing sector.
Research methodology overview
Our methodology utilizes a triangulation approach, combining verified trade registry data and financial filings from companies like Airgas Inc. with primary interviews from industry engineers and procurement managers. We supplement this with secondary macroeconomic indicators and regional industrial output reports to ensure our baseline estimates accurately capture the 10.13% CAGR and broader market trajectory.
Scope of the report coverage
This report covers the global Industrial Gases-Glass Industry Market, focusing on types (Hydrogen, Oxygen, Nitrogen, Argon, Acetylene), applications, and distribution modes. Geographic coverage spans North America, Europe, and Asia-Pacific. Limitations include data volatility due to localized geopolitical events and energy price fluctuations, which are accounted for through sensitivity analysis to provide the most reliable 2027–2033 forecast possible.
Recent developments and strategic moves
Recent developments reflect a surge in partnerships and facility expansions. Major players like HyGear Technology and HoSt Holding B.V. are pioneering on-site gas generation to reduce transport dependency. Simultaneously, competitive moves by Showa Denko K.K. and Matheson Tri-Gas Inc. involve new product launches focusing on higher purity standards, directly addressing the strict requirements for specialty glass applications in electronics and advanced photonics.