Market overview of the Biofuel Testing Services Market
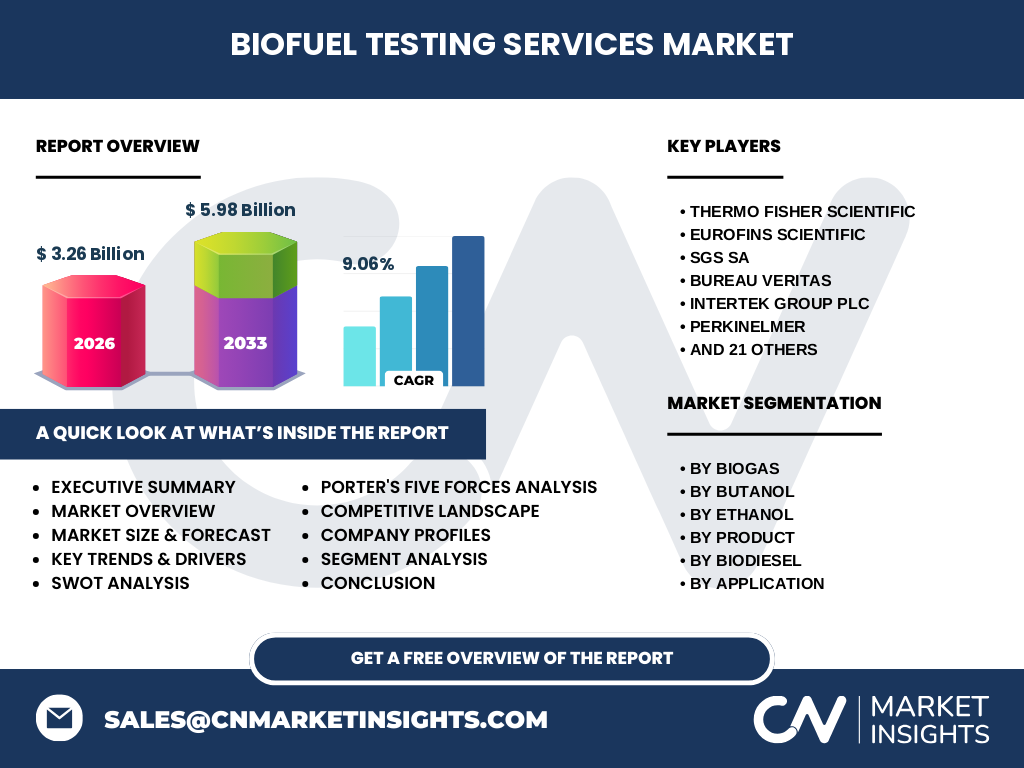
The Biofuel Testing Services Market acts as the critical quality assurance layer for the global transition to sustainable energy. Valued at 3.26 Billion in 2026, this sector encompasses rigorous analytical testing for biofuels like ethanol, biodiesel, and biogas. These services ensure compliance with stringent international standards like ASTM D6751 and EN 14214, mitigating risks related to fuel stability, corrosive contaminants, and engine performance optimization.
Structural Growth Drivers and Market Constraints
Growth is propelled by aggressive decarbonization mandates and the rising demand for low-carbon fuels in aviation and heavy transport. However, the market faces logistical hurdles, particularly in standardization of testing protocols across diverse feedstocks like waste oils or lignocellulosic biomass. Our analysis indicates that companies effectively navigating these regulatory frameworks see significant upside as global refineries pivot away from traditional fossil-based hydrocarbon processing.
Emerging trends shaping the Biofuel Testing Services landscape
A pivot toward Advanced Biofuels, specifically Biojet Fuels and Hydrotreated Vegetable Oil (HVO), is redefining testing requirements. We observe a trend toward on-site, rapid-analysis mobile laboratories which reduce supply chain latency. Innovation in testing technology by leaders like PerkinElmer and Shimadzu Corporation is enabling real-time detection of trace metals and impurities, critical for the stringent specifications required for modern high-performance turbine engines.
Post-pandemic trajectory and COVID-19 impact analysis
The COVID-19 pandemic caused temporary stagnation in biofuel consumption due to aviation sector shutdowns, yet the Biofuel Testing Services Market demonstrated remarkable resilience. As global travel recovered, testing demand surged to meet new sustainability verification mandates. Our research suggests that the crisis accelerated the adoption of automated digital reporting, allowing providers like SGS SA to maintain continuity while supporting the critical supply chains of energy generation and refinery clients.
Competitive Benchmarking and Strategic Dynamics
The market is dominated by global testing giants like Intertek Group PLC, Bureau Veritas, and Eurofins Scientific. Strategic positioning involves expanding footprints near major maritime hubs and production clusters to offer localized, rapid services. Competitive advantage is increasingly gained through technical certifications and the ability to test complex, emerging products like algal biofuels, where standardized testing methodologies remain highly specialized and difficult for smaller labs to replicate.
Executive summary of the Biofuel Testing Services Market
With a projected valuation of 5.98 Billion by 2033, the market is poised for a robust CAGR of 9.06%. This growth is driven by the urgent need for fuel quality verification in the automotive, energy, and aviation sectors. Our synthesis indicates that firms investing in high-throughput automated systems and global accreditation networks are the best positioned to capitalize on this significant expansion through 2033.
Market forecast 2027 to 2033
From 2027 to 2033, we project the sector to grow from its current baseline to 5.98 Billion, maintaining a consistent CAGR of 9.06%. This trajectory assumes increased regulatory pressure on biodiesel and green diesel adoption. The proliferation of localized anaerobic digester gas projects, particularly in rural industrial zones, will further diversify the demand for testing services beyond traditional urban refinery service points.
Segmentation analysis of the Biofuel Testing Services Market
Our analysis breaks down the market into critical segments: Product type (Ethanol, Biodiesel, Biogas, Green Diesel, Butanol), Location (On-site vs. Off-site), and Application (Automotive, Refineries, Mining, Energy). Each segment plays a vital role; for instance, the Green Diesel segment, including HVO, is witnessing high growth as refineries retool, demanding highly specialized analytical services to ensure compliance with specific feedstock purity and cold-flow property requirements.
Regional market analysis and performance
Regional performance is dictated by legislative support, such as the Renewable Fuel Standard in the U.S. and RED III in Europe. North America and Europe currently lead in testing volume due to mature refinery infrastructures. Meanwhile, the Asia-Pacific region is emerging as a high-potential market, driven by localized production of ethanol and increasing investment in algal biofuels within industrial zones near major Asian port hubs.
In-depth regional review
In North America, the focus is on fuel ethanol and biodiesel quality for automotive fleets. Conversely, Europe’s market is heavily skewed toward HVO and renewable diesel verification due to strict environmental directives. Our research indicates that localized Bureau Veritas and Intertek facilities are heavily engaged in regional port monitoring to ensure imported biofuel shipments meet the specific carbon intensity thresholds required for domestic market entry.
Company profiles and strategic positioning
Leading players like Thermo Fisher Scientific and Agilent Technologies lead in providing high-end analytical instrumentation. Service-based giants like ALS Global, TÜV SÜD, and AmSpec LLC focus on third-party verification and lab-as-a-service models. These companies maintain dominance by aligning their geographic expansion with regional biofuel production centers, ensuring they provide the rapid turnaround times essential for supply chain logistics in the energy and mining sectors.
Porter's Five Forces analysis
The market displays moderate competitive rivalry, characterized by high barriers to entry due to stringent ISO/IEC 17025 accreditation requirements. Buyer power remains significant for large-scale refineries, yet the demand for expert technical verification reduces their ability to switch providers easily. Threat of substitutes is low, as chemical analysis is fundamentally required by regulatory bodies to certify biofuels for public use in engines.
SWOT analysis of the industry
Strengths include high demand for quality compliance. Weaknesses relate to the complexity of testing diverse waste-based feedstocks. Opportunities exist in the rapid expansion of Biojet Fuels, requiring new, specialized testing capabilities. Threats center on potential shifts in government subsidy policies that could impact production volume. Companies like Beta Analytic and EnviroLogix effectively mitigate threats by positioning themselves as specialized, high-accuracy service providers in specific testing niches.
Value chain analysis
The value flow begins at the raw material procurement stage (e.g., vegetable oils, residues). Testing services, provided by firms like Saybolt or Element Materials Technology, occur at the production refinery or storage terminal stages. This value chain culminates at the end-user, such as automotive manufacturers or airlines, who require documented proof of fuel quality, ensuring that the entire lifecycle adheres to strict global environmental sustainability standards.
Investment insights and strategic recommendations
Investors should target providers of on-site analytical services and those specializing in Biojet Fuel testing, as these are high-potential areas. Our data suggests that acquisitions targeting regional niche testing laboratories will yield high ROI by capturing localized market share. Strategic focus should be directed toward companies that integrate AI-driven reporting, which significantly enhances operational efficiency and client retention across the entire biofuel supply chain.
Conclusion and key takeaways
The Biofuel Testing Services Market is a fundamental enabler of the global energy transition. With a solid CAGR of 9.06% through 2033, the market will scale to 5.98 Billion. Success depends on technical mastery of emerging fuels like renewable diesel and maintaining broad, global accreditation. The industry is moving toward greater automation and speed, favoring those who invest early in decentralized, tech-enabled laboratory infrastructures.
Research methodology overview
Our analysis triangulates data using a proprietary triangulation model. We cross-reference trade registry data for service volume with primary stakeholder interviews from top-tier testing providers. This is reconciled with secondary macroeconomic indicators and regional refinery capacity growth figures to ensure that our 3.26 Billion 2026 baseline and subsequent 5.98 Billion 2033 forecast provide a highly accurate, defensible market perspective.
Scope of the report coverage
The report covers the global Biofuel Testing Services Market, segmented by product (ethanol, biodiesel, biogas, green diesel, butanol), application, and service location. Our research parameters focus on commercial laboratory testing services used to meet regulatory and performance standards. Geographic scope includes North America, Europe, Asia-Pacific, and Rest of World, excluding internal, non-commercial testing conducted by biofuel manufacturers for private R&D purposes.
Recent developments and industry activity
Recent activity highlights a wave of partnerships between testing firms like Intertek and renewable fuel production plants to implement continuous quality monitoring. Furthermore, announcements from Thermo Fisher Scientific regarding new analytical hardware optimized for HVO testing signal a broader shift in the market. These strategic moves underline the importance of technological agility in responding to evolving global fuel specifications and heightened regulatory scrutiny.