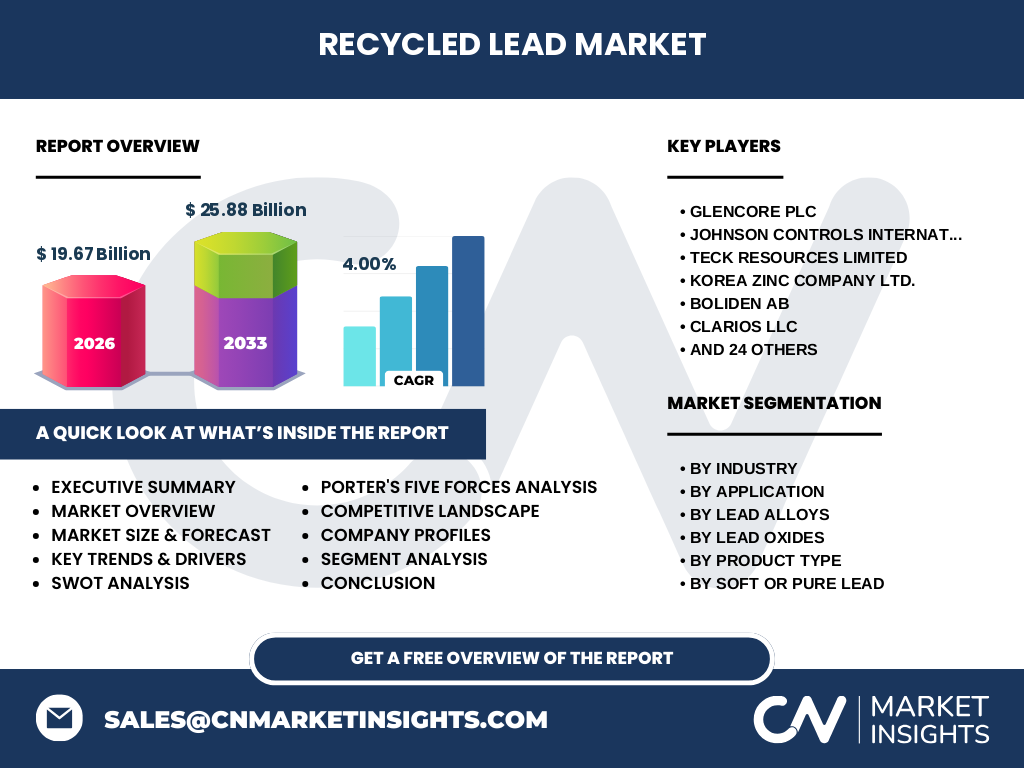
Market overview of the Recycled Lead Market
The Recycled Lead Market represents a vital segment of the circular economy, focusing on the recovery of lead from secondary sources, primarily spent lead-acid batteries. Valued at 19.67 Billion in 2026, this industry is essential for stabilizing global supply chains. By mitigating dependency on virgin lead extraction, companies ensure a sustainable stream of raw material for high-demand sectors like automotive and energy storage.
Structural Growth Drivers and Restraints
The market is propelled by a 4.00% CAGR, driven by the persistent demand for reliable, cost-effective energy storage. However, growth faces significant regulatory headwinds from bodies like the EPA and EU REACH, which impose stringent environmental standards on smelting operations. Companies like Eco-Bat Technologies and Gopher Resource leverage advanced metallurgical processes to manage these logistical hurdles while capitalizing on the shift toward closed-loop battery recycling.
Emerging Trends in Recycled Lead Production
We observe a pivotal shift toward hydro-metallurgical recovery, moving away from traditional pyrometallurgical smelting to reduce carbon footprints. Innovators such as Aqua Metals and ACE Green Recycling are leading this transition. These technologies enhance the purity of battery-grade lead, meeting the increasingly complex specifications required by modern data centers and electric vehicle infrastructure, effectively outpacing older extraction methods.
COVID-19 Impact and Recovery Analysis
The pandemic triggered temporary supply chain disruptions in Recycled Lead Market logistics, particularly affecting the collection of scrap lead from automotive maintenance. However, the subsequent rebound in global manufacturing and the surge in transportation electrification catalyzed a robust recovery. The industry successfully leveraged high demand for backup power systems, ensuring that recovery remained steady, ultimately positioning the sector for growth toward 25.88 Billion by 2033.
Competitive Benchmarking and Market Concentration
The landscape is highly consolidated, featuring tier-one giants like Glencore plc, Teck Resources, and Clarios LLC alongside specialized recyclers. Strategic differentiation is focused on vertical integration, where companies control the cycle from battery collection to refined alloy production. Smaller, nimble players like Gravita India maintain competitive relevance by tapping into decentralized, localized markets that larger firms often overlook in favor of high-volume port-based smelting.
Executive Summary of Global Insights
Our analysis projects the Recycled Lead Market to reach 25.88 Billion by 2033, growing at a steady 4.00% CAGR. This expansion is anchored in the necessity for resource circularity. Major participants are aggressively optimizing their value chains to counter volatility in raw material costs, while regulatory compliance has evolved from a burden into a key competitive advantage that barriers new, less sophisticated market entrants.
Market Forecast 2027-2033
We forecast sustained growth, with the market reaching a valuation of 25.88 Billion by 2033. This trajectory reflects a consistent 4.00% CAGR, underpinned by the essential role of lead-acid batteries in healthcare backup and energy grid stabilization. Our research indicates that steady demand for lead-calcium alloys in start-stop automotive technology will act as a primary engine for these long-term financial outcomes.
Segmentation Analysis of the Industry
The market is bifurcated by application and material type. Key segments include Energy and Transportation, which command the largest market share due to battery demand. Product-wise, the focus remains on Soft or Pure Lead, Lead Alloys, and Lead Oxides. Each segment plays a specialized role, with data centers increasingly driving demand for high-purity battery-grade lead to ensure consistent power reliability during peak load events.
Regional Market Performance and Dynamics
Geographically, the Recycled Lead Market is dominated by regions with high automotive and industrial density. Europe and North America emphasize stringent regulatory compliance, favoring advanced technological recyclers. Conversely, the Asia-Pacific region displays explosive growth, driven by massive domestic consumption of lead-acid batteries. Strategic positioning in major port hubs like Shanghai or Rotterdam remains crucial for minimizing logistics costs in the global trade of secondary lead scrap.
In-depth Regional Review
In North America, companies like RSR Corporation and The Doe Run Resources Corporation set the benchmark for emission control and logistical efficiency. Europe, led by players like Recylex S.A. and Sirmet SAS, focuses heavily on the circular economy directive. These regions contrast with emerging markets where collection networks are currently being modernized to improve the recovery yield of lead oxides and alloys from automotive waste.
Company Profiles and Strategic Positioning
Leaders like Korea Zinc Company Ltd. and Yuguang Gold Lead Co. Ltd. maintain dominance through massive scale and integrated supply chains. Meanwhile, firms like Mayco Industries and Mayer Alloys Corporation differentiate themselves via high-value specialty products like sheet lead and radiation shielding. These strategic choices allow companies to insulate their margins from the commodity price volatility inherent in the broader base-metal recycling industry.
Porter's Five Forces Assessment
The Recycled Lead Market features moderate threat of new entrants due to heavy environmental regulatory requirements. Supplier power is influenced by the availability of spent batteries, while buyer power is concentrated among automotive OEMs. Competitive rivalry is intense, forcing firms like Exide Industries to innovate in lead-antimony and lead-selenium alloy formulations to maintain an edge over competitors operating solely on pure lead volume.
SWOT Analysis: Strategic Outlook
Strengths: Established circular supply chains and high recyclability. Weaknesses: Dependence on automotive battery cycles and energy-intensive processing. Opportunities: Investment in low-carbon hydrometallurgy and expanding into renewable energy grid storage applications. Threats: Stricter environmental mandates and potential shifts toward competing chemistry in battery technologies. Success requires balancing legacy operational efficiency with rapid, innovative technical adoption across the entire value chain.
Value Chain Analysis of Lead Recycling
The value flow initiates with the collection and sorting of spent batteries, critical for maintaining high-quality input material. This moves to smelting and refining, where companies like Engitec Technologies provide the process engineering. Finally, the refined product—ranging from Lead (II) Oxide to specific Lead-Tin alloys—is channeled into manufacturing sectors. Effective value chain management is the differentiator that determines profitability in this highly competitive, capital-intensive landscape.
Investment Insights and Recommendations
We recommend focusing on firms that invest in low-emission recycling technology and those with robust, proprietary battery collection partnerships. High-potential areas include the expansion of lead-acid battery recycling capacity in emerging economies and the development of specialized alloys for the data center sector. Investors should prioritize players like Terrapure Environmental who demonstrate resilience against regulatory shifts while maintaining operational scale in the secondary lead market.
Conclusion and Key Takeaways
The Recycled Lead Market is on a firm growth trajectory, expected to reach 25.88 Billion by 2033. The industry's shift toward technological sophistication is not merely an option but a survival imperative driven by environmental policy and the demand for higher-purity materials. Success in this sector will reward those who can effectively integrate advanced metallurgical innovation with efficient, globalized material collection and distribution strategies.
Research Methodology for Data Triangulation
Our estimates are derived from a robust multi-source framework. We triangulate data from official trade registries, annual disclosures of major players like Glencore plc and Clarios LLC, and proprietary primary interviews with plant managers. This quantitative baseline is validated against macroeconomic indicators such as automotive output and grid infrastructure spending, ensuring the 4.00% CAGR projection is both accurate and reflective of real-world industry conditions.
Scope of the Report and Limitations
This report encompasses the global Recycled Lead Market, specifically covering soft lead, alloys, and oxides. While we account for major industrial sectors, the report does not cover small-scale artisanal recovery or unauthorized smelting operations. Our analysis focuses on legitimate, industrial-scale market participants, providing a high-level strategic overview that serves as a foundation for business planning, investment analysis, and competitive benchmarking within the global supply chain.
Recent Developments in the Industry
Recent strategic moves include partnerships aimed at enhancing battery collection density and the rollout of proprietary green smelting technology by firms like Aqua Metals. Furthermore, significant announcements from Gravita India regarding capacity expansions in various regions indicate a firm commitment to capturing market share. These developments demonstrate a dynamic market landscape where technological investment and capacity scaling define the winners of the next decade of recycled lead production.