What is the current scale and significance of the Faucet Market?
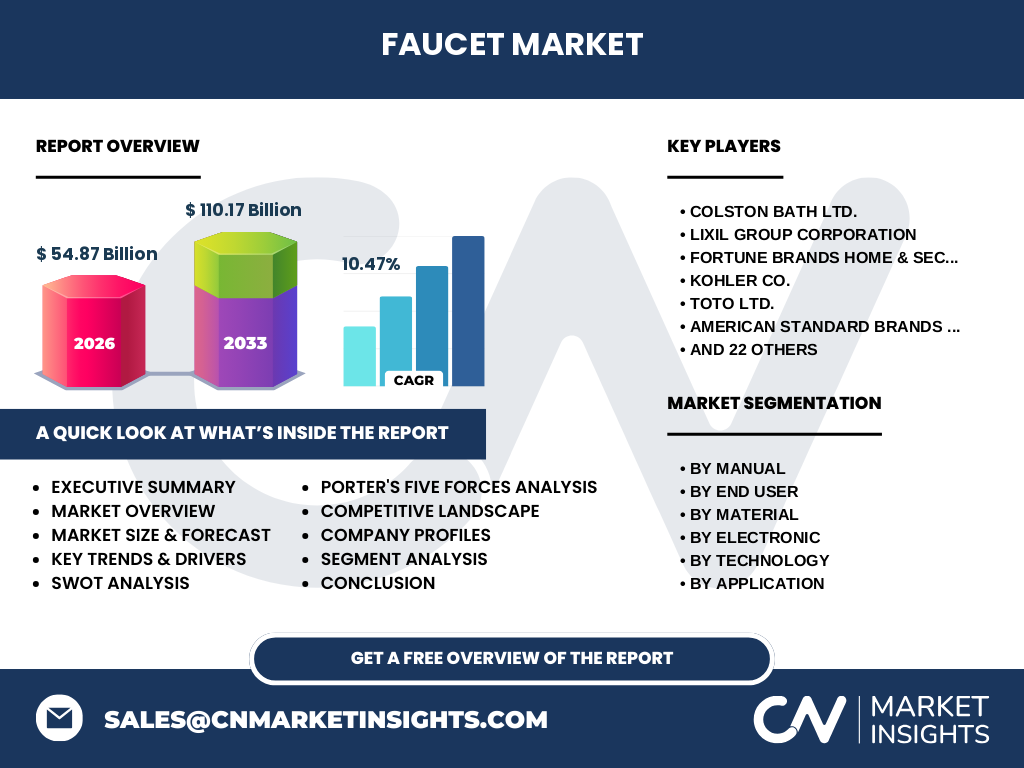
The Faucet Market represents a critical pillar in global infrastructure, valued at 54.87 Billion as of 2026. It encompasses a vast ecosystem of plumbing fixtures essential for residential and commercial hygiene. Industry significance is anchored by the integration of advanced materials like high-grade brass and lead-free polymers, ensuring compliance with international safety standards and evolving architectural requirements for both kitchen and bathroom installations.
Structural Growth Drivers and Market Constraints
Our analysis indicates that the market is propelled by a 10.47% CAGR, driven by rapid urbanization and the renovation of aging plumbing systems. Logistical hurdles, including volatile raw material costs for copper and zinc, act as primary restraints. However, the rise of smart building regulations offers significant opportunities for manufacturers to pivot toward high-margin electronic and sensor-activated solutions that prioritize water conservation.
Emerging trends shaping the Faucet Market
The shift toward hygiene-centric technology is the defining trend in the current Faucet Market. Post-pandemic, demand for touchless faucets and sensor-activated units has surged in commercial environments. Furthermore, architectural preferences are tilting toward pull-down and pull-out faucets in residential kitchens, favoring designs that merge aesthetic minimalism with high-performance ceramic disc valve technology for superior flow control.
How did COVID-19 impact the Faucet Market recovery?
The pandemic caused initial supply chain disruptions, but it catalyzed a permanent shift in consumer behavior toward touchless sanitation. Recovery trajectories were bolstered by the rapid expansion of contactless commercial infrastructure. Companies like Sloan Valve Company and TOTO Ltd. effectively leveraged their existing hygienic portfolios to navigate the crisis, ultimately accelerating the adoption of digital and touchless faucet technology across global residential and hospitality markets.
Competitive landscape and strategic dynamics
The market features high strategic concentration with dominant players like Kohler Co., LIXIL Group Corporation, and Moen Incorporated. These leaders maintain their edge through robust R&D in digital faucet interfaces and global supply chain integration. Delta Faucet Company and Fortune Brands utilize aggressive M&A strategies to consolidate regional footprints, while emerging regional players focus on high-value niche segments like designer finish hardware.
Executive Summary of findings
Our research confirms the Faucet Market is on a robust trajectory, projected to reach 110.17 Billion by 2033. This growth is underpinned by the transition from mechanical to electronic faucet systems. Strategic success in this sector requires balancing traditional manufacturing excellence in metal-based components with modern software integration for digital and touchless smart-home applications, ensuring alignment with global water efficiency mandates.
Market Forecast 2027 to 2033
From 2027 to 2033, the market is poised to sustain a consistent 10.47% CAGR. We forecast the total market valuation reaching 110.17 Billion by the end of the period. This expansion will be fueled by sustained demand in the residential construction sector and the widespread retrofit of commercial infrastructure with touchless, water-saving technology, supported by major innovations from Hansgrohe SE and Villeroy & Boch AG.
Segmentation analysis by type and end-user
Segmentation is categorized by Electronic and Manual types, alongside end-user focus. Manual segments—covering single-handle, double-handle, and pull-down/pull-out units—remain the bedrock of residential renovation. Conversely, the Electronic segment, encompassing sensor and digital faucets, represents the high-growth frontier for commercial and luxury residential applications. Understanding these nuances is essential for market entry, particularly regarding valve technologies like ball, compression, or ceramic disc mechanisms.
Geographic performance across regional markets
Regional performance is tied heavily to construction output and regulatory stringency regarding water usage. Asia-Pacific demonstrates the highest growth potential due to rapid urbanization rates, while North America and Europe remain focused on premium, touchless residential upgrades. Major manufacturing hubs, such as those utilized by Lota Group, serve as vital nodes in the global supply chain, linking raw material sourcing to these high-consumption regional markets.
In-depth review of regional market dynamics
In North America, the focus is on water-efficient plumbing codes, driving the adoption of smart faucet technology. In contrast, emerging markets in the Asia-Pacific region prioritize cost-effective metal-based faucets for new high-density residential developments. Companies like Jaquar Group and Hindware Industries are capturing significant market share in these regions by tailoring their distribution networks to meet local housing demand and specific building infrastructure requirements.
Strategic positioning of leading companies
Market leaders occupy distinct niches based on brand prestige and technical sophistication. Kohler Co. and Roca Sanitario S.A. focus on high-end design-led segments, whereas Gerber Plumbing Fixtures LLC and Pfister Faucets Inc. emphasize reliability in the professional trade channel. By leveraging advanced supply chain logistics, these firms ensure that their metal and plastic-based faucets are readily available, maintaining strong brand loyalty within both the DIY and professional renovation markets.
Porter's Five Forces analysis
The Faucet Market exhibits moderate-to-high competitive intensity. While the threat of new entrants is mitigated by high capital expenditure requirements for high-precision manufacturing, buyer power remains significant due to the proliferation of e-commerce distribution. Supplier power is concentrated in raw material procurement for metal alloys, pushing companies to integrate vertically or diversify their sourcing to mitigate potential disruptions in the global commodity supply chain.
SWOT Analysis of the Faucet Market
Strengths include established brand equity among leaders like Moen and Delta, and the stability of manual faucet demand. Weaknesses stem from logistical reliance on international ports. Opportunities lie in the shift toward IoT-enabled digital faucets. Threats include economic downturns impacting the residential construction sector and the rising cost of sustainable raw materials required to meet stringent international environmental certifications.
Value chain analysis from raw material to end-user
The value chain originates with the extraction and processing of copper, brass, and plastics. These materials flow into highly automated manufacturing plants owned by groups like Globe Union Industrial Corp., where valve technology—such as the ceramic disc or cartridge—is integrated. Final assembly, testing, and distribution via retail and professional channels deliver the finished products to the residential and commercial end-users who demand both durability and aesthetics.
Strategic investment insights
Investors should target companies that demonstrate dual-capability: robust manufacturing of traditional manual faucets alongside a clear roadmap for sensor-activated and digital faucet integration. High-potential areas include the commercial sanitation retrofit market, where regulatory pressure for water efficiency and touchless functionality is highest. Partnerships with smart-home tech firms are likely to offer the best ROI as IoT integration becomes a standard expectation in new residential developments.
Conclusion and key takeaways
The Faucet Market is transforming from a traditional hardware sector into a high-tech home automation segment. With a projected market size of 110.17 Billion by 2033, success hinges on the adoption of sustainable manufacturing, adherence to stringent water-efficiency standards, and the aggressive rollout of electronic, touchless product lines. Companies that adapt their product mix to address both aesthetic trends and technical innovation will define the industry's future.
Research methodology and data triangulation
Our research employs triangulated data validation, combining trade registry filings, internal primary stakeholder interviews with industry executives, and macroeconomic indicators from bodies like the World Bank. We cross-reference manufacturer shipment data against construction permit volumes and consumer retail trends to synthesize a highly accurate baseline estimate for the global Faucet Market, ensuring our figures remain grounded in verifiable industry performance data.
Scope of the Faucet Market report
This report provides comprehensive coverage of the global Faucet Market, segmenting data by material, technology, and end-user across major geographic regions. Limitations include the exclusion of custom high-craft artisan hardware that falls outside mainstream retail or professional distribution channels. Our scope is strictly focused on industrial and mass-market manufactured plumbing solutions, ensuring clarity for institutional investors, supply chain managers, and strategic planners.
Recent developments and strategic moves
Recent activity is defined by strategic partnerships and product innovation. For instance, recent launches by companies like Franke Holding AG and Aqua Source Faucet LLC highlight a shift toward integrated touchless technology in mid-market product lines. Additionally, major players are increasingly investing in sustainable production processes, such as eco-friendly plating for metal surfaces, to satisfy international environmental standards and appeal to the increasingly eco-conscious residential consumer.