What is the current market overview and industry significance of the Outsourcing Services Market?
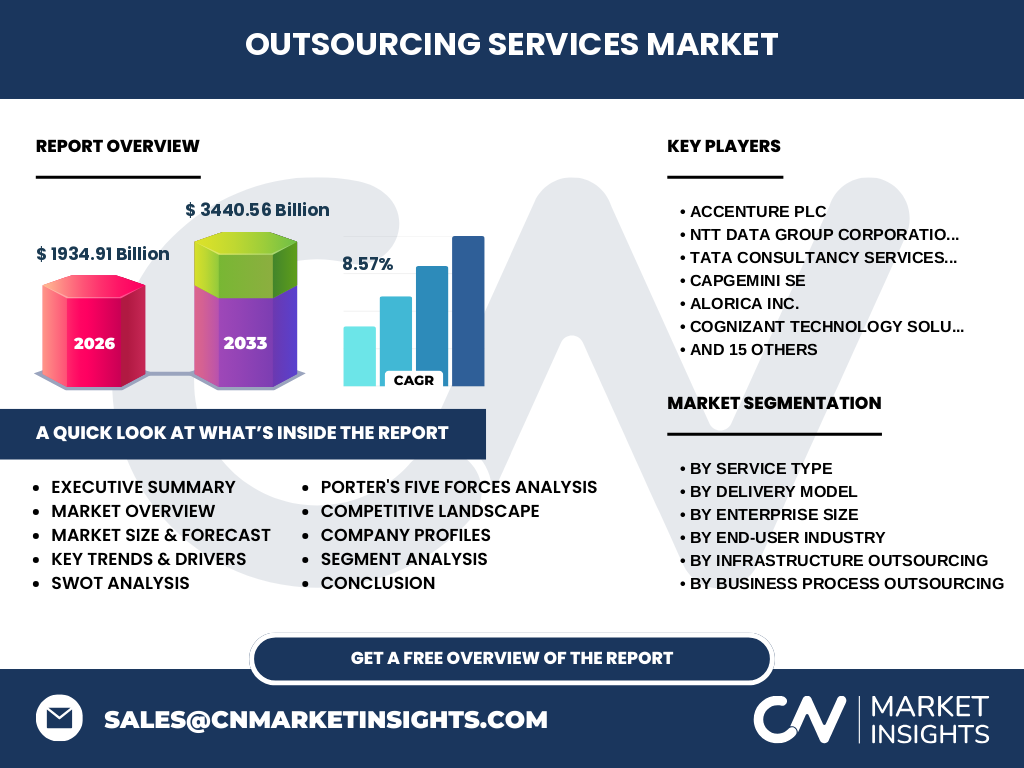
The Outsourcing Services Market represents a vital strategic pillar for modern enterprises, valued at 1934.91 Billion in 2026. It encompasses the delegation of non-core processes—ranging from Information Technology Outsourcing to Knowledge Process Outsourcing—to specialized third-party providers. This industry is essential for operational agility, allowing firms to focus on core competencies while leveraging external expertise to manage complex infrastructure and regulatory requirements across global supply chains.
Structural Growth Drivers and Market Constraints in the Outsourcing Services Market
Primary growth is fueled by the digital transformation imperative and the need for cost-effective scalability. Conversely, market restraints include stringent data sovereignty regulations (such as GDPR) and geopolitical volatility that complicates offshore delivery models. Companies must navigate talent shortages in specialized fields while balancing the demand for Cloud Computing Services against the risks inherent in complex cross-border logistical and compliance frameworks.
Emerging trends and long-term growth patterns in the Outsourcing Services Market
We observe a paradigm shift toward AI-integrated BPO solutions and smarter Infrastructure Management Services. The market is evolving from simple labor-arbitrage models to value-based outcome partnerships. With a projected market value of 3440.56 Billion by 2033, the integration of Cybersecurity Services and automated Data Analytics within outsourcing contracts is becoming a prerequisite for sustaining competitive advantage in a data-centric global economy.
How did the COVID-19 pandemic redefine the recovery trajectory for this sector?
The pandemic acted as a catalyst for remote service delivery, forcing an abrupt transition from legacy on-premise models to robust Cloud Infrastructure Management. While initial disruptions hampered Workplace Services Outsourcing, the recovery trajectory is marked by a permanent shift toward hybrid working models. Firms like TTEC Holdings Inc. and Teleperformance SE successfully pivoted to resilient digital-first strategies, establishing a new baseline for global service continuity.
Competitive Benchmarking in the Outsourcing Services Market
The landscape is highly consolidated among tier-one providers like Accenture plc, Infosys Limited, and Tata Consultancy Services Limited. These giants compete through proprietary automation frameworks and global delivery centers near major ports and tech hubs. Strategic dynamics favor firms with deep vertical expertise in Banking Financial Services And Insurance (BFSI), as they leverage Intellectual Property Research Services to differentiate themselves in a crowded, high-stakes market environment.
Executive Summary: Synthesis of findings regarding the Outsourcing Services Market
Our research confirms the Outsourcing Services Market is poised for significant expansion, with a CAGR of 8.57% through 2033. This growth is underpinned by the increasing complexity of Application Development and the global demand for specialized Recruitment Process Outsourcing. Strategic stakeholders must prioritize investment in Cloud Computing and Disaster Recovery to align with the overarching trends of rapid digital integration and operational resilience.
Market Forecast: Growth projections through 2033
Based on our quantitative models, the market is expected to reach 3440.56 Billion by 2033. This trajectory reflects an accelerated adoption rate among Large Enterprises seeking Network Infrastructure Outsourcing. We anticipate that emerging segments, particularly in Legal Process Services and Cybersecurity, will drive significant incremental value as companies outsource critical governance functions to mitigate systemic risks in an increasingly regulated international business environment.
How does segmentation influence the operational strategy of Outsourcing Services Market participants?
Segmentation is granular, covering BPO, ITO, KPO, RPO, and Infrastructure Outsourcing. Each segment serves a unique purpose: RPO handles human capital scaling, while Infrastructure Outsourcing ensures the stability of Data Center Management. Understanding these segments allows companies like Capgemini SE or Cognizant Technology Solutions Corporation to tailor their delivery models—whether Onshore, Offshore, or Nearshore—to meet the specific fiscal and technological requirements of diverse end-user industries.
Regional performance analysis and geographic market distribution
Regional dominance is shifting toward markets with high digital literacy and favorable tax incentives for tech exports. North America remains the largest revenue contributor due to intense IT Outsourcing demand, while the Asia-Pacific region serves as the primary hub for offshore delivery. European markets, governed by strict EU compliance frameworks, are increasingly shifting toward nearshore arrangements to balance proximity with cost efficiency.
In-depth regional review: Critical constraints and opportunities
Regional performance is dictated by labor cost structures and digital infrastructure maturity. In India and the Philippines, the abundance of skilled labor in Finance and Accounting Services provides a competitive edge. Conversely, regional markets in the Middle East are aggressively investing in government-sector digitization. These regional dynamics require providers to navigate diverse regulatory bodies and localized logistical hurdles to successfully deliver global business intelligence solutions.
Company Profiles: Strategic positioning of key industry players
Major players such as HCL Technologies Limited and Tech Mahindra Limited leverage massive R&D investments to dominate the engineering outsourcing space. Genpact Limited specializes in process-led Data Analytics, while TaskUs Inc. focuses on high-growth, tech-enabled customer support. These companies define their market position by aligning specific service portfolios with the critical needs of retail, healthcare, and telecommunications sectors, often acting as strategic partners rather than simple service providers.
Porter's Five Forces analysis of the Outsourcing Services Market
The threat of new entrants remains moderate due to high capital requirements for global infrastructure. Bargaining power of buyers is high, driven by the shift toward multi-vendor sourcing strategies. Competitive rivalry is fierce among established firms like Wipro Limited and CGI Inc., while substitute services—such as internal AI-based automation—represent a long-term challenge to traditional labor-heavy outsourcing models, necessitating constant innovation in the Application Development space.
SWOT analysis of the global Outsourcing Services Market
Strengths: Operational scalability and deep technical expertise. Weaknesses: Dependence on specific regional labor markets and data security vulnerabilities. Opportunities: Rapid adoption of AI-driven knowledge services and expansion into emerging markets. Threats: Increasing protectionism and geopolitical instability disrupting cross-border data flows. Successful market participants leverage their strengths in Cloud Infrastructure to neutralize these threats and capitalize on the growing demand for specialized Back Office Operations.
Value chain analysis in the Outsourcing Services Market
The value chain begins with raw input data and talent acquisition, flowing through service delivery engines powered by proprietary tech platforms, and ending with high-value output for end-users. Firms like EXL Service Holdings Inc. and Firstsource Solutions Limited manage this flow by integrating advanced analytics directly into client workflows. This structure ensures that value is added at every stage, from candidate sourcing to complex financial analysis.
Investment insights and high-potential areas for growth
Investors should focus on providers specializing in Cybersecurity Services and Cloud Computing Management. The data suggests that companies targeting Small And Medium Enterprises (SMEs) with standardized, low-overhead outsourcing solutions are currently undervalued. Furthermore, areas related to Disaster Recovery and Intellectual Property Research are seeing high demand, providing a lucrative opportunity for firms that can bridge the gap between complex regulatory requirements and operational efficiency.
Conclusion and key takeaways for stakeholders
The Outsourcing Services Market is entering a period of sophisticated growth. With a forecast value of 3440.56 Billion by 2033, success depends on technological agility and the ability to navigate complex international regulations. Key takeaways include the prioritization of AI and cybersecurity integration and the strategic importance of hybrid delivery models, which are essential for maintaining competitive advantage in this rapidly evolving global industry landscape.
Research methodology: How are these baseline estimates triangulated?
Our estimates are derived from a rigorous triangulation process. We synthesize trade registry data, audit annual reports from key players like Hinduja Global Solutions Limited and TDCX Inc., and conduct extensive primary stakeholder interviews. These are cross-referenced with macroeconomic indicators and industry-specific demand drivers. This multi-layered approach ensures the reliability of our CAGR of 8.57% and provides a robust foundation for our comprehensive market analysis.
Scope of the report: Parameters and analytical limitations
This report evaluates the global Outsourcing Services Market, focusing on five primary service types and eight end-user industries. The scope covers major geographical regions but excludes localized, non-scalable consultancy projects. While our data provides a high level of confidence for strategic planning, projections are subject to the inherent volatility of global trade policy and the rapid pace of technological disruption in the Information Technology segment.
Recent developments: Strategic moves shaping the market
Recent activity is defined by strategic M&A and digital partnerships. Players like Sutherland Global Services Inc. and ibex Limited have announced significant investments in generative AI for customer support. Partnerships between major IT providers and Cloud infrastructure giants are accelerating the transition to Managed Infrastructure Services. These developments indicate a market-wide race to integrate advanced automation and high-level business intelligence into the standard service delivery ecosystem.