What is the scope and industry significance of the Movie Theaters Market?
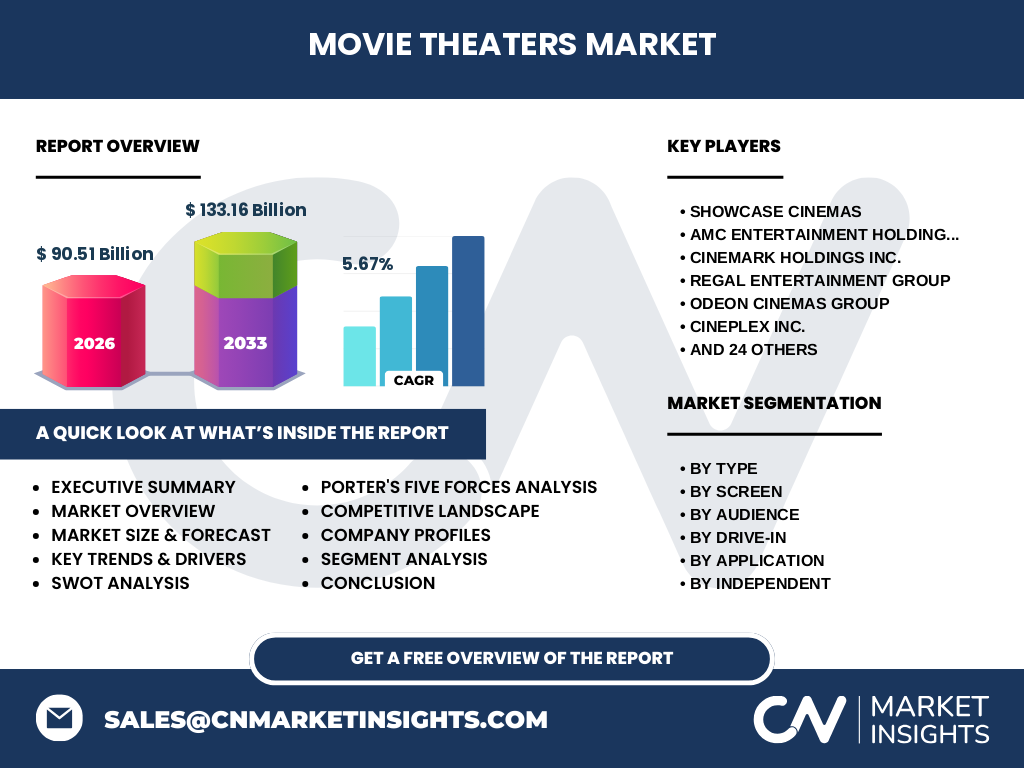
The Movie Theaters Market represents the global infrastructure for large-format exhibition, encompassing multiplexes, IMAX, and independent cinemas. It serves as the vital final node in the film distribution value chain. As of 2026, the sector maintains a 90.51 Billion valuation, acting as a high-stakes cultural engine that drives ancillary revenues across hospitality, retail, and local urban development sectors.
Structural Growth Drivers and Market Constraints
Growth is primarily anchored by the 5.67% CAGR trajectory toward 133.16 Billion by 2033. Key drivers include premiumization—specifically luxury and gourmet F&B offerings. Conversely, structural constraints involve high overhead costs, logistical dependencies on global film distribution hubs, and the ongoing shift toward shortened theatrical exclusivity windows mandated by major studios, which forces operators to pivot toward experiential, multi-purpose venue models.
Emerging Trends and Shift Toward Premiumization
The market is undergoing a technological renaissance, moving from standard 2D to IMAX with laser projection and immersive 3D. We observe a tactical shift toward boutique theaters that prioritize unique audience experiences over volume. Furthermore, the integration of modern drive-ins with advanced digital audio illustrates how legacy exhibition formats are being repurposed to survive in a high-density, digital-first consumer landscape.
How did the COVID-19 pandemic redefine the recovery trajectory?
The pandemic acted as a catastrophic stress test, forcing a liquidity crisis that consolidated the industry. Recovery is now driven by de-risking strategies, where operators like AMC and Cinemark have prioritized high-margin premium multiplex assets. The post-COVID reality shows a robust rebound, with the industry successfully reclaiming its position as a primary social destination through aggressive pricing and exclusive, large-format content eventization.
Competitive Benchmarking and Market Concentration
The Movie Theaters Market is characterized by a concentrated landscape dominated by global titans such as AMC Entertainment, Cinemark, and Regal Entertainment Group. Strategic dynamics are defined by economies of scale in procurement. Meanwhile, regional players like PVR Ltd and CJ CGV maintain competitive moats through localized content strategies, effectively balancing global blockbusters with domestic film slates to ensure consistent footfall.
Executive Summary: Synthesis of Market Findings
Our research indicates that the Movie Theaters Market is entering a phase of high-value maturation. With a projected size of 133.16 Billion by 2033, the industry is successfully navigating the transition from mass-market volume to premium experiences. Success depends on the agility to integrate private screenings and high-end amenities into existing multiplex infrastructure while mitigating the volatility of film release schedules.
Market Forecast: The path to 2033
From 2027 to 2033, the market is poised to grow at a 5.67% CAGR. This growth is underpinned by capital-intensive investments in laser projection and ergonomic luxury seating. Our model assumes that mature markets will emphasize unit-level profitability, while emerging territories will leverage standard multiplex expansion to meet the surging demand for out-of-home entertainment among burgeoning middle-class demographics.
Segmentation Analysis: Breaking down the exhibition landscape
The market is segmented by Type (Multiplexes, IMAX, Drive-In, Independent) and Screen Technology (2D vs. 3D). Multiplexes remain the backbone of the revenue stream, while IMAX segments capture high-margin demand for premium visual fidelity. The classification of independent theaters into art house and boutique sub-segments is critical for identifying niche revenue streams that insulate operators from the cyclical nature of wide-release blockbusters.
Regional Performance and Geographic Distribution
Performance varies drastically across geographies. North America remains a mature, high-spend hub, while the Asia-Pacific region acts as a high-growth corridor. Regulatory bodies like the MPA in the US and local censorship/licensing boards in Asia influence theater logistics. Geographic success hinges on urban penetration; operators like Kinepolis and Vue International excel by dominating key metropolitan transit zones.
In-depth Regional Review
North American growth is tethered to the premium multiplex upgrade cycle. In contrast, PVR Ltd and INOX Leisure highlight the aggressive expansion in India, where multiplex penetration is still outpacing total supply. European markets, led by Odeon and Kinepolis, focus on historical landmark retrofitting and boutique cinema experiences to appeal to older, more affluent demographic segments, driving high average ticket prices.
Strategic Positioning of Leading Players
Companies like Alamo Drafthouse and Marcus Theatres leverage gourmet F&B to transform theaters into lifestyle venues, effectively raising the average transaction value. Meanwhile, CJ CGV and Lotte Cinema utilize aggressive vertical integration to control exhibition in dense urban retail centers. These players prioritize high-frequency repeat visitors through loyalty programs that capitalize on the 5.67% CAGR market growth trajectory.
Porter's Five Forces Analysis
The Movie Theaters Market faces high threat of substitutes from streaming, moderated only by the exclusive theatrical window. Buyer power is moderate but shifting, as loyalty programs incentivize retention. Supplier power is significant, as major studios dictate content flow. The competitive rivalry is intense, forcing differentiation through technology (Laser/IMAX) and hospitality (Luxury F&B), creating high barriers to entry for smaller, independent operators.
SWOT Analysis of the Global Exhibition Sector
Strengths: Unrivaled immersive experience. Weaknesses: Heavy reliance on studio content calendars. Opportunities: Diversification into private screenings and e-sports/gaming events to optimize off-peak hours. Threats: Rapid evolution of home-theater technology and shrinking release windows. Our analysis suggests that proactive adaptation, such as Odeon or Cineplex adopting multi-use venue strategies, is the primary mitigation strategy against these systemic threats.
Value Chain Analysis: From Production to the Screen
The value chain starts with content creation and moves through global film distributors to the cinema. Logistics are governed by digital cinema packages (DCPs) shipped to local sites. The final, critical value-add occurs at the multiplex level, where ancillary retail and Premium F&B generate high-margin revenue. This flow is increasingly reliant on data-driven inventory management and sophisticated CRM platforms to maximize yield per seat.
Investment Insights and High-Potential Areas
High-potential investment lies in luxury and premium multiplex segments where unit economics are strongest. Investors should prioritize operators with diverse revenue models, such as those incorporating private screenings and high-margin boutique amenities. Markets with rising disposable income, specifically within APAC, offer the highest growth potential, as they mirror the developmental trajectory of US-based Harkins Theatres or Galaxy Theatres in their initial expansion phases.
Conclusion and Key Takeaways
The Movie Theaters Market is fundamentally resilient, transforming from a simple film-viewing utility into a sophisticated experiential hub. With a valuation target of 133.16 Billion by 2033, the path forward is marked by technological differentiation and premium service. Success hinges on a company's ability to balance the logistical hurdles of global film procurement with the local necessity of high-end, bespoke consumer engagement.
Methodology: How baseline estimates are triangulated
Our baseline estimates are derived from triangulation: reconciling public trade registry filings, proprietary interviews with regional cinema CEOs, and secondary macroeconomic indicators (e.g., box office gross receipts and CPI-adjusted consumer spending). We apply a weighted-average growth model to historical data to reach the 5.67% CAGR, ensuring the forecast accounts for localized market constraints, regional film regulatory changes, and broader digital shift variables.
Scope of the report: Parameters and limitations
This report encompasses global Movie Theaters Market trends, covering segments from IMAX to drive-ins. Scope includes detailed analysis of 30+ leading players. Limitations focus on regional regulatory volatility; specifically, it excludes informal or grey-market film screenings, focusing solely on established, regulated exhibition entities. Our projections assume current theatrical exclusivity trends remain consistent through 2033.
Recent Developments and Industry Moves
Recent strategic moves include AMC's continued expansion into premium large-format (PLF) screens and PVR/INOX mergers to create economies of scale in the Indian market. Additionally, Alamo Drafthouse has pivoted toward experiential dining integration. These partnerships signal a broader industry trend toward consolidated power and technological upgrades, as operators align to protect their market share against the aggressive content dissemination strategies of major streaming platforms.