Market Overview: Defining the Rig and Oil Field Market landscape
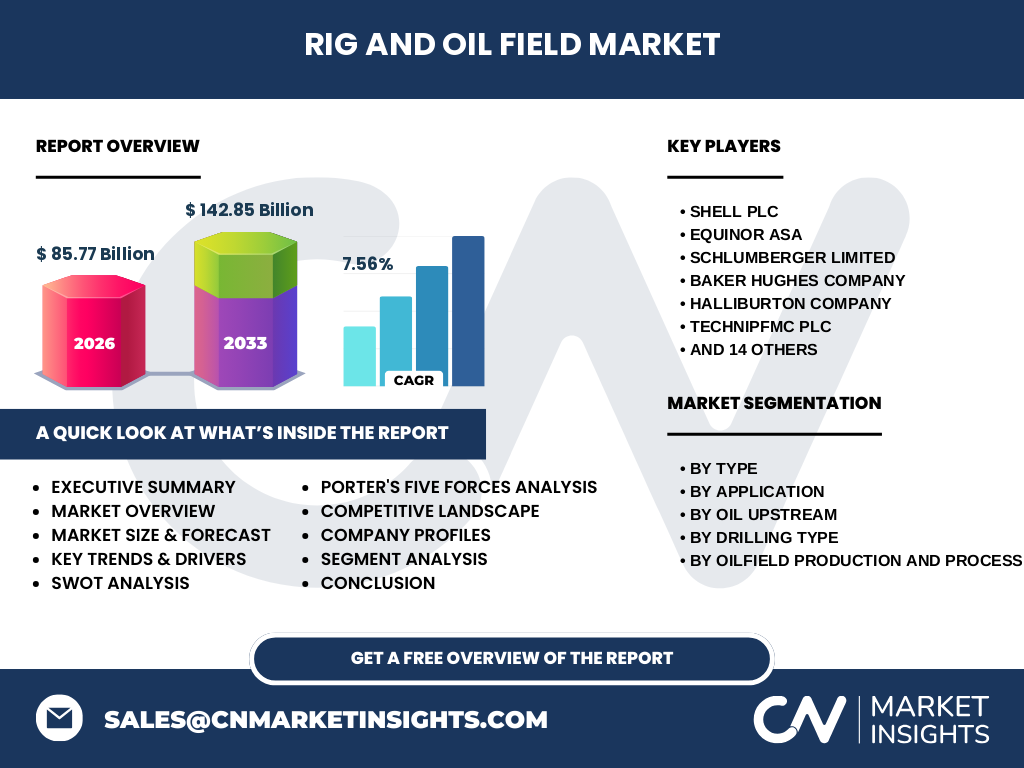
The Rig And Oil Field Market encompasses the expansive ecosystem of exploration, drilling, and production infrastructure. Valued at 85.77 Billion in 2026, this sector represents the critical backbone of global energy security. It spans complex upstream exploration and processing operations, essential for extracting hydrocarbons and preparing them for midstream transport, reflecting the profound industrial significance of energy self-sufficiency across global economies.
Structural Growth Drivers and Market Constraints
Growth is propelled by rising global energy demand and technological optimization in subsea equipment. Our analysis identifies regulatory pressures from bodies like the EPA and localized constraints in jurisdictions like the North Sea as primary hurdles. However, the move toward field level processing units provides a significant opportunity for market players to enhance operational efficiency despite volatile commodity price cycles.
Emerging Trends in the Rig and Oil Field Market
The shift toward digitalized oilfield management is the definitive trend, as firms like Schlumberger and Halliburton integrate AI into well intervention. Additionally, the industry is seeing heightened focus on Liquefied Natural Gas (LNG) processing infrastructure to support global energy transitions. These technological advancements ensure that operational longevity is prioritized alongside traditional extraction methods, defining the next decade of field development.
COVID-19 Impact and Recovery Trajectory
The pandemic triggered a sharp contraction in capital expenditure, forcing a rapid pivot toward lean operations. Our research indicates a resilient recovery as the Rig And Oil Field Market rebounded by focusing on automation and cost-rationalization. Major players successfully navigated supply chain ruptures, transitioning from survival mode back to the high-growth trajectory required to reach the 142.85 Billion projection by 2033.
Competitive Benchmarking: Major Players and Strategic Dynamics
Market concentration is high, dominated by integrated majors like Shell and Equinor, alongside service giants like TechnipFMC and Saipem. These entities leverage strategic partnerships to de-risk high-cost offshore projects. Competitive positioning relies on specialized capabilities in drilling and storage operations, with firms like Transocean and Valaris maintaining dominance through advanced offshore rig fleets tailored for complex, deep-water environments.
Executive Summary: Synthesis of Research Findings
The industry is poised for robust expansion, with a CAGR of 7.56% through 2033. Our synthesis reveals that oil upstream segments, particularly exploration and drilling, are the primary value drivers. With a forecasted market size of 142.85 Billion, success hinges on balancing traditional production with emerging LNG processing requirements and optimizing field workforce accommodation for efficiency in remote, logistically challenging locales.
Market Forecast: Projecting Growth from 2027 to 2033
We project the market to grow from its 2026 baseline of 85.77 Billion to 142.85 Billion by 2033. This sustained growth is supported by an aggressive 7.56% CAGR. Increased investment in integrated oilfield processing complexes and subsea equipment will accelerate in the latter half of the forecast period as legacy fields reach maturation and require advanced intervention to maintain output levels.
Segmentation Analysis: Breaking Down the Industry
The market is segmented by type into Oil Upstream—covering drilling, exploration, and production—and Oilfield Production And Processing Operations. Application segments further range from Field Workforce Accommodation to Industrial Operations and Energy Infrastructure. This segmentation captures the entire lifecycle, from the initial spudding of a well to the final crude oil offtake and terminal distribution processes.
Regional Market Performance and Distribution
Regional performance is dictated by proximity to major hydrocarbon reserves and existing energy infrastructure. The Middle East and North America remain the dominant hubs, while emerging activity in the South Atlantic is accelerating. The Rig And Oil Field Market analysis shows that localized regulatory landscapes, such as those mandated by the Bureau of Safety and Environmental Enforcement, significantly influence regional capital deployment and technological adoption rates.
In-depth Regional Review of Core Markets
In North America, focus remains on shale optimization and well intervention. Conversely, the offshore markets in Europe and West Africa prioritize subsea equipment and deep-water drilling. Asian markets, led by China Oilfield Services Limited, are expanding their Liquefied Natural Gas processing capabilities, showing how geographic regionality drives specific technological demands within the broader Rig And Oil Field Market.
Strategic Positioning of Leading Companies
Leading firms occupy distinct market niches. Weatherford International and KCA Deutag focus on precision drilling, while Subsea 7 and TechnipFMC lead in subsea infrastructure. Noble Corporation and Seadrill maintain high-spec offshore rig fleets. Our analysis suggests that these companies are increasingly diversifying their service portfolios to capture value across both exploration and field-level processing, ensuring their resilience against regional market fluctuations.
Porter's Five Forces: Competitive Assessment
The Rig And Oil Field Market exhibits intense competitive rivalry among established service providers. The threat of new entrants is low due to high capital intensity and complex regulatory barriers. Bargaining power of buyers is significant, particularly among national oil companies demanding cost-effective extraction technologies. Substitutes remain limited in the short term, ensuring that upstream services remain essential to the energy value chain.
SWOT Analysis: Strategic Outlook
Strengths include established technical expertise and massive global infrastructure. Weaknesses involve high sensitivity to volatile crude prices. Opportunities reside in digital transformation and LNG processing expansion. Threats are posed by stringent environmental regulations and shifting global energy policies. This SWOT highlights that players prioritizing operational efficiency will successfully mitigate threats while leveraging their upstream capabilities to drive future growth.
Value Chain Analysis: From Materials to End-Users
The value chain initiates with raw materials—specialized steel alloys and drilling fluids—transitioning through drilling and well intervention services. Value flows into field-level processing and storage operations before reaching Energy Infrastructure And Export Facilities. This integration ensures that raw resources are converted into market-ready commodities, with firms like Baker Hughes providing the necessary instrumentation to maximize output at every stage.
Investment Insights and Strategic Recommendations
Investors should target companies integrated in Liquefied Natural Gas processing and subsea equipment, as these are high-potential areas under the 7.56% CAGR growth model. We recommend monitoring firms that demonstrate technological scalability in their pipeline operations. Companies capable of deploying automated drilling rigs will likely outperform peers in a high-cost environment, providing superior long-term returns for shareholders within the sector.
Conclusion and Key Takeaways
The Rig And Oil Field Market is a fundamental component of the global economy, projected to reach 142.85 Billion by 2033. The primary takeaway is that innovation in production and processing is paramount. Stakeholders must align strategies with both technological trends and regional regulatory requirements to capitalize on the sustained growth driven by rising energy needs and mature field optimization efforts.
Research Methodology: How Baseline Estimates Are Triangulated
Our methodology utilizes a robust triangulation approach, combining audited trade registry data with direct primary stakeholder interviews among executive leadership at firms like Shell and Transocean. We cross-reference these findings with secondary macroeconomic indicators and localized regulatory filings to ensure our market size and forecast accuracy remain precise, creating a highly credible Rig And Oil Field Market analysis.
Scope and Parameters of the Report
This report provides comprehensive coverage of the global Rig And Oil Field Market, focusing on upstream exploration, drilling, and processing activities. The scope includes geographic assessments, competitive benchmarking, and segment-specific forecasts through 2033. Limitations include inherent market volatility in commodity prices and localized geopolitical risks, which are accounted for through rigorous scenario planning and statistical modeling of past market performance data.
Recent Developments and Market Movements
Recent developments underscore a shift toward strategic partnerships, such as joint ventures in offshore drilling to share risks in deep-water basins. Several companies have announced major product launches focused on low-carbon processing units and AI-enabled logistics. These moves, documented in recent press releases from industry titans, reinforce our research findings that efficiency-centric innovation is currently the driving force behind all major investment announcements.