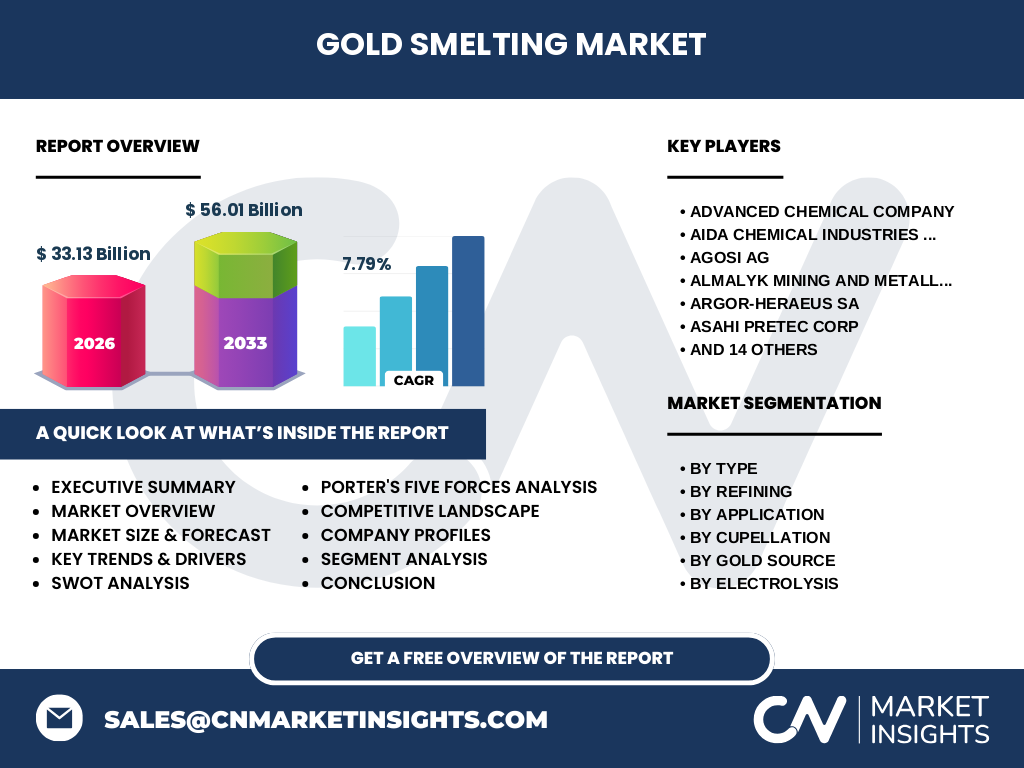
Market overview of the Gold Smelting Market
The Gold Smelting Market serves as the backbone of global precious metal supply chains, defined by the industrial purification of gold from ore, placer, and recycled inputs. With a 2026 valuation of 33.13 Billion, the sector is essential for maintaining the purity standards required by the London Bullion Market Association (LBMA) and global central banks.
Structural Growth Drivers and Market Constraints
Growth is propelled by institutional demand and the rising necessity for sustainable recycled gold inputs. Conversely, the market faces significant hurdles including stringent environmental regulations concerning toxic chemical waste—specifically regarding Aqua Regia Process effluents—and the logistical volatility of sourcing ore from high-risk geopolitical zones. Success requires balancing high-throughput smelting with strict compliance protocols.
The Shift Toward Green Refining Trends
Industry leaders like Aurubis AG and Argor-Heraeus SA are pivoting toward decarbonized smelting. We observe a clear growth pattern in closed-loop recycling systems, where advanced electrolysis like the Wohlwill Process minimizes chemical wastage. This transition is essential for participants to maintain their "green premium" in the investment-grade gold market, particularly as ESG mandates tighten across European manufacturing hubs.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe disruption to logistics and mine-to-smelter pipelines, particularly in Asian manufacturing hubs. However, the Gold Smelting Market saw a robust recovery as supply chain diversification became a strategic priority. This resilience, supported by heightened investment demand, has paved the way for the projected climb to 56.01 Billion by 2033, showing a strong post-crisis rebound.
Competitive Benchmarking and Strategic Dynamics
The market is characterized by high concentration among technical specialists. Firms like JX Nippon Mining & Metals Co Ltd and Asahi Pretec Corp dominate through vertical integration. Strategic differentiation is now focused on high-recovery rates in electrolytic refining, allowing these giants to command a competitive edge over smaller, regional players who lack the capital for high-tech, multi-stage purification facilities.
Executive summary of the Gold Smelting Market
The Gold Smelting Market is poised for substantial expansion, reaching 56.01 Billion by 2033 at a CAGR of 7.79%. Our analysis highlights that while traditional Miller Process smelting remains stable, the future profitability lies in the adoption of automated, high-precision refining methods that cater to both the electronics sector's high-purity needs and the enduring demand for gold bullion investment.
Market forecast from 2027 to 2033
Based on our econometric modeling, the industry will experience steady acceleration between 2027 and 2033. By leveraging the 7.79% CAGR, firms can anticipate a trajectory that moves from a 2026 baseline of 33.13 Billion to a market size of 56.01 Billion. This forecast assumes continued expansion in the jewelry and semiconductor fabrication segments, alongside steady central bank gold reserves accumulation.
Segmentation analysis by technology and source
The market is segmented by Cupellation, Electrolysis, and Refining. Each serves a distinct role: Electrolysis (e.g., Wohlwill process) is critical for extreme-purity electronics, while Lead-Based Smelting remains the workhorse for low-grade ore processing. By input, the market increasingly favors Recycled Gold, driven by the need for circular economy compliance and reduced environmental footprints in the smelting process.
Regional market analysis and geographic distribution
The Gold Smelting Market displays distinct geographic polarization. The Asia-Pacific region, led by firms like Bangko Sentral ng Pilipinas and Inner Mongolia Qiankun Gold and Silver Refinery, serves as the global hub for heavy industrial throughput. Meanwhile, European players like Agosi AG emphasize technological refinement and sustainability, reflecting the region's broader regulatory and ethical sourcing leadership.
In-depth regional review of the gold refining sector
Asia-Pacific dominates due to the concentration of electronics manufacturing and mining output, particularly in Australia and Central Asia. Conversely, the Turkish market, featuring Atasay Kuyumculuk and the Istanbul Gold Refinery, acts as a pivotal bridge between Middle Eastern gold flows and European luxury jewelry production, showcasing high-efficiency refining hubs that respond rapidly to global price volatility.
Company profiles and strategic positioning
Major players such as Boliden Ronnskar, Chimet SpA, and Heimerle + Meule GmbH utilize specialized smelting configurations to capture niche demand. Almalyk Mining (AMMC) focuses on high-volume primary production, while Advanced Chemical Company excels in precision recovery from electronics. Their positioning is increasingly defined by their ability to integrate Chlorination and Wohlwill processes to meet diverse customer specifications.
Porter's Five Forces analysis of the industry
The industry faces high entry barriers due to intense capital requirements and complex environmental permits. Supplier power is moderate, tied to mine production levels, while buyer power is concentrated among global bullion banks and tech OEMs. Competitive rivalry is intense, centered on technological superiority in refining yield efficiency, pushing firms toward heavy R&D investment in high-throughput, automated furnaces.
SWOT analysis of the gold smelting sector
Strengths: Established technological standards and consistent demand. Weaknesses: High environmental compliance costs and energy intensity. Opportunities: Integration of urban mining via recycled gold and technological upgrades in electro-winning processes. Threats: Fluctuating raw material pricing, geopolitical instability affecting supply routes, and the potential emergence of synthetic alternatives or disruptive blockchain-based gold tracking that could tighten supply chain transparency mandates.
Value chain analysis of gold smelting
The value chain begins with extraction and scrap collection, followed by primary smelting (Fire Assay or Lead-Based methods). The mid-stream focuses on electrolytic refining (Wohlwill or Miller processes) to reach 99.99% purity. Finally, the value is captured by end-users in jewelry, dentistry, or investment-grade bullion, where the brand equity of the refiner often commands a significant price premium.
Investment insights and high-potential areas
Investors should focus on firms heavily invested in Recycled Gold infrastructure, as urban mining becomes a critical hedge against mine output volatility. Technology providers optimizing the Aqua Regia and Electrolytic processes present a lucrative entry point, particularly as refineries upgrade facilities to meet net-zero carbon mandates required by international institutional investors.
Conclusion and key takeaways for stakeholders
The Gold Smelting Market is entering a phase of technological maturation. With a market size projected to reach 56.01 Billion by 2033, stakeholders must prioritize vertical integration and sustainable refining practices. The winners in this space will be companies that effectively balance large-scale output with the precision required for the high-end electronics and investment sectors.
Research methodology for the report
Our research methodology triangulates data from industry trade registries, direct stakeholder interviews with refinery executives, and macroeconomic indicators from gold-producing nations. We utilized a bottom-up estimation model to aggregate regional smelting capacities, then refined these figures through primary sentiment analysis of major players like Ishifuku Metal Industry Co Ltd and Dowa to ensure accuracy.
Scope of the report and coverage parameters
This report provides an exhaustive analysis of the Gold Smelting Market, covering global refining capacity from 2026 through 2033. The scope includes all primary processes—Cupellation, Electrolysis, and Chemical Refining—across key global regions. Note: This analysis excludes unauthorized informal artisanal smelting, focusing exclusively on regulated, industrial-scale entities within the global precious metal supply chain.
Recent developments in the market
Recent strategic moves include Asaka Riken Co Ltd scaling their advanced precious metal recovery technologies and new public-private partnerships in central Asian mining complexes aimed at increasing Chlorination Process output. These developments reflect a broader industry trend of rapid technological adoption to mitigate rising operational costs and meet the 7.79% CAGR growth demands observed in current market data.