Market Overview: Defining the scope and significance of the Metagenome-Assembled Genomes (MAGs) Services Market.
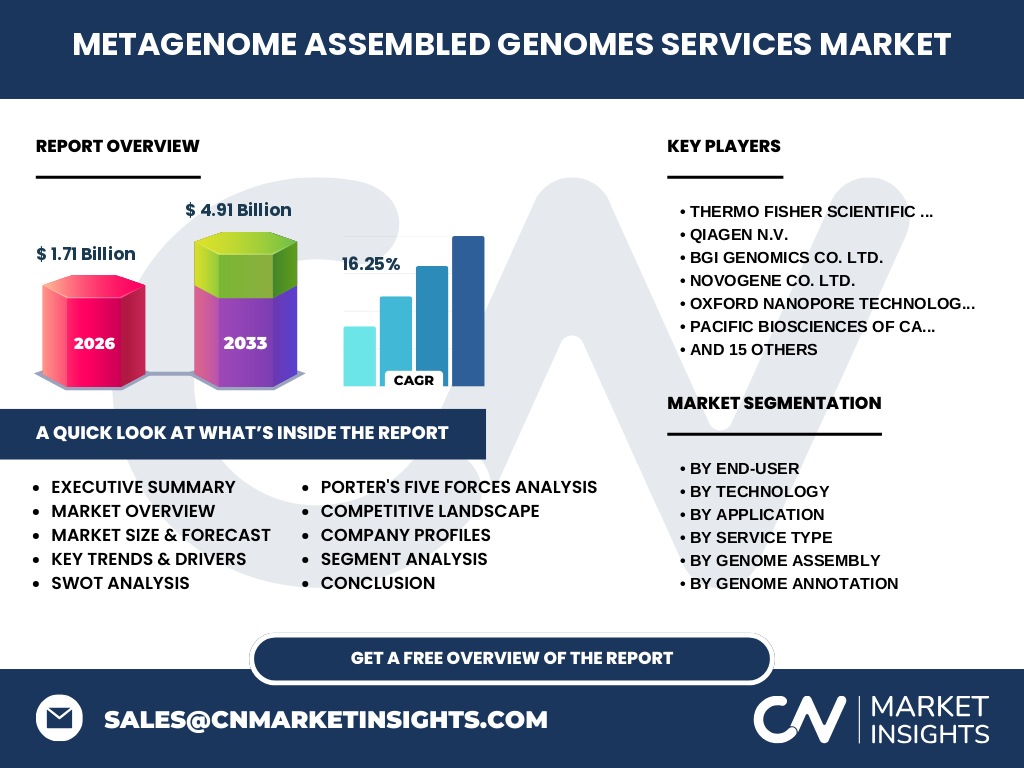
The Metagenome-Assembled Genomes (MAGs) Services Market represents a critical frontier in functional genomics, enabling the reconstruction of individual microbial genomes from complex environmental samples. Valued at 1.71 Billion in 2026, this sector facilitates deep insights into microbial ecology, human health, and biotechnology. It serves as an essential bridge between raw Next-Generation Sequencing data and actionable biological knowledge, powering innovation across diverse industrial and academic landscapes.
Structural Growth Drivers, Restraints, and Opportunities in the MAGs Services Market.
Growth is primarily driven by the falling cost of Third-Generation Sequencing and rising demand for microbiome-based therapeutics. Conversely, high data storage costs and stringent regulatory compliance hurdles imposed by agencies like the FDA remain significant restraints. Opportunities abound in Artificial Intelligence (AI)-based assembly pipelines, which solve complex computational bottlenecks and allow for faster, more accurate metabolic pathway identification in large-scale metagenomic datasets.
Emerging Trends and Strategic Patterns Shaping the Industry.
A pivot toward Cloud-Based Bioinformatics Platforms and hybrid assembly techniques is defining current industry trends. Firms are increasingly prioritizing automated quality assessment and validation to streamline workflows. This shift minimizes manual error and enhances reproducibility, which is essential for biotech firms operating under strict ISO standards. These trends suggest a trajectory toward standardized, highly scalable, and user-friendly metagenomic service ecosystems.
How did the COVID-19 pandemic influence the Metagenome-Assembled Genomes (MAGs) Services Market?
The pandemic acted as a massive accelerant for the Metagenome-Assembled Genomes (MAGs) Services Market, catalyzing rapid investment in viral and microbial surveillance infrastructure. The urgent need for pathogen identification and clinical diagnostics pushed NGS technology into the mainstream. Post-pandemic, we observe a sustained recovery trajectory as investments pivot toward broader environmental monitoring and long-term clinical longitudinal studies, securing the market's robust growth foundation through 2027 and beyond.
Competitive Landscape and Strategic Market Positioning.
The market is characterized by a mix of technology giants like Thermo Fisher Scientific Inc. and QIAGEN N.V., alongside specialized bioinformatics innovators such as Seven Bridges Genomics Inc. and Eagle Genomics Ltd. Market concentration is moderate, with top-tier players focusing on integrated, end-to-end service solutions. Smaller, specialized firms are finding competitive advantages by offering bespoke custom bioinformatics and algorithm optimization, which are vital for niche clinical and agricultural applications.
Executive Summary: A High-Level Synthesis of Market Projections.
Our analysis projects that the Metagenome-Assembled Genomes (MAGs) Services Market will expand from 1.71 Billion in 2026 to 4.91 Billion by 2033, reflecting a solid CAGR of 16.25%. This trajectory underscores the transition of MAGs from purely academic exploration to an indispensable commercial tool for drug discovery, precision agriculture, and regulatory-grade functional annotation. Investors should note this sector's high-barrier-to-entry and critical dependency on sophisticated computational architecture.
Market Forecast: Growth Trajectory from 2027 to 2033.
Between 2027 and 2033, the market is expected to witness explosive growth, reaching a valuation of 4.91 Billion. The CAGR of 16.25% will be supported by the adoption of long-read sequencing across clinical diagnostics and biotechnology sectors. As automated pipelines mature, the cost-per-genome will drop, democratizing access for medium-sized firms and further accelerating the adoption of specialized metagenome binning and comparative genomics annotation services globally.
Segmentation Analysis: Understanding the Core Market Pillars.
Segmentation is categorized by End-User, Technology, Application, and Service Type. Key segments include Pharmaceutical and Biotechnology Companies, driving demand for drug target discovery, and Academic/Research Institutes, fueling methodological R&D. Technology segments cover the spectrum from base Next-Generation Sequencing to advanced AI-based analytics. These segments create a granular value chain, enabling targeted market entry strategies for service providers specializing in specific domains like taxonomic classification or metabolic pathway analysis.
Regional Market Analysis: Geographic Distribution and Performance.
North America leads the Metagenome-Assembled Genomes (MAGs) Services Market due to the concentration of major Contract Research Organizations (CROs) and advanced biotech hubs. Europe follows, with significant focus on regulatory compliance assistance and clinical standardization. Meanwhile, the Asia-Pacific region is emerging as the fastest-growing market, bolstered by rapid infrastructure expansion in countries like China and India, where companies such as BGI Genomics Co. Ltd. maintain a powerful strategic presence.
In-depth Regional Review: Key Regional Markets and Localized Dynamics.
Regional performance is highly influenced by localized infrastructure, such as logistics hubs for sample shipping and the presence of high-performance computing (HPC) clusters. In North America, the market focuses on high-complexity drug discovery, whereas the European market emphasizes comparative genomics for environmental surveillance. These regional nuances necessitate distinct marketing and service delivery models, particularly for global players like Eurofins Genomics Germany GmbH and Novogene Co. Ltd., to maintain regional dominance.
Company Profiles and Strategic Positioning of Leading Industry Players.
Leading companies like Oxford Nanopore Technologies Ltd. and Pacific Biosciences of California Inc. maintain technological superiority in Third-Generation Sequencing. Conversely, software-centric firms such as DNAnexus Inc. and Lifebit Biotech Ltd. dominate the cloud-based bioinformatics landscape. QIAGEN Digital Insights GmbH and Eagle Genomics Ltd. are strategically positioned to lead in functional annotation and data integration, capturing value by transforming raw sequence data into actionable insights for the pharmaceutical industry.
Porter's Five Forces Analysis: Competitive Forces Assessment.
The Metagenome-Assembled Genomes (MAGs) Services Market faces moderate threat of new entrants due to high capital requirements for sequencing equipment and proprietary software. Bargaining power of buyers is rising as research institutes demand more customization. Competitive rivalry remains intense among established firms, while the threat of substitutes is low given the unique utility of metagenome binning, making the market highly attractive for long-term specialized investments.
SWOT Analysis: Strengths, Weaknesses, Opportunities, and Threats.
Strengths: Advanced technical proficiency in de novo assembly and gene prediction. Weaknesses: High reliance on specialized talent and expensive hardware. Opportunities: Rapid expansion into personalized medicine and predictive agriculture. Threats: Evolving global data privacy regulations (e.g., GDPR) and potential cybersecurity breaches in centralized data storage platforms. This analysis reveals the necessity for firms to invest in robust security and data governance frameworks to mitigate identified risks.
Value Chain Analysis: From Raw Materials to End-Users.
The value chain originates with sample collection and nucleic acid extraction, followed by high-throughput sequencing. Value is further added through metagenome binning, annotation, and interpretation. Ultimately, biotech firms and academic researchers leverage these services to develop therapeutic pipelines. The flow of information is critical; successful players like CosmosID Inc. add significant value by providing intuitive visualization, ensuring that end-users derive immediate biological relevance from complex genomic datasets.
Investment Insights: Strategic Recommendations and High-Potential Areas.
We recommend focusing investments on companies developing AI-based pipelines for automated functional annotation, as these represent the highest margin opportunities. There is also a substantial market gap in regulatory compliance assistance, making this a prime area for expansion. Our research suggests that firms capable of offering custom bioinformatics consulting, such as BaseClear B.V., will see superior returns by catering to the increasingly complex needs of the biopharmaceutical sector.
Conclusion and Key Takeaways.
The Metagenome-Assembled Genomes (MAGs) Services Market is set for transformative growth, reaching 4.91 Billion by 2033. Success hinges on a firm's ability to integrate cutting-edge sequencing technology with seamless, user-centric bioinformatics solutions. As the industry moves toward deeper metabolic pathway analysis and clinical application, companies that prioritize data security, AI-driven automation, and regulatory expertise will define the market's future landscape and capture the greatest share of value.
Research Methodology: How are baseline estimates and market data triangulated?
Baseline estimates are synthesized through triangulation of primary stakeholder interviews, global trade registry data, and macroeconomic indicators. We cross-reference proprietary datasets from Contract Research Organizations with annual reports from major public firms like Thermo Fisher Scientific Inc. and QIAGEN N.V. This multi-layered approach ensures the accuracy of our 16.25% CAGR forecast by adjusting for regional disparities and specific market entry barriers in both the clinical and agricultural sectors.
Scope of the Report: Coverage Parameters and Limitations.
This report provides comprehensive coverage of the global Metagenome-Assembled Genomes (MAGs) Services Market, focusing on services from sequence data generation to interpretation. The analysis covers key segments, including genome assembly, annotation, and custom bioinformatics. Limitations include a focus on commercially active service providers; it does not account for internal, non-commercial sequencing operations performed within private laboratories, which are outside the scope of current market size valuations.
Recent Developments: Major Company Announcements and Strategic Moves.
The industry has seen a wave of activity, including significant partnerships between Oxford Nanopore Technologies Ltd. and AI-driven firms to enhance real-time sequencing analytics. Companies like Microba Life Sciences Pty Ltd are actively launching new clinical-grade taxonomic classification tools, while MR DNA LLC has expanded its footprint through strategic moves into high-throughput environmental screening, demonstrating the continuous cycle of innovation required to stay competitive in the MAGs Services Market.