What defines the scope and industry significance of the Semi-Mobile Crushing Plant Market?
The Semi-Mobile Crushing Plant Market encompasses modular, high-capacity machinery designed for flexible deployment in mining and aggregate sectors. These systems bridge the gap between stationary plants and portable units, offering scalability. By enabling localized processing near the extraction point, these plants significantly reduce logistical overheads and fuel consumption, serving as a cornerstone for modern, efficient extraction operations globally.
Structural Growth Drivers and Market Constraints
Driven by rising infrastructure investment, the Semi-Mobile Crushing Plant Market faces a trajectory shaped by mining demand and sustainability mandates. While high initial capital requirements act as a restraint, the opportunity for rapid deployment at remote sites remains a strong catalyst. Operators must navigate stringent local environmental regulations concerning noise and dust suppression to capitalize on shifting urban development needs.
The Shift Toward Hybrid and Electric Power Systems
A pivot toward energy-efficient technology is reshaping the Semi-Mobile Crushing Plant Market. Manufacturers like Metso Corporation and Sandvik AB are prioritizing hybrid and electric-powered systems to comply with global decarbonization targets. This shift minimizes reliance on fossil fuels, reducing the carbon footprint in massive quarrying and mining applications while optimizing operational costs through improved power management.
How did the COVID-19 pandemic influence the sector and its subsequent trajectory?
The pandemic caused initial supply chain disruptions, halting projects and delaying equipment delivery. However, the Semi-Mobile Crushing Plant Market proved resilient as governments accelerated infrastructure stimulus packages to drive economic recovery. This post-pandemic demand fostered a focus on remote-operation technologies and digital monitoring, allowing projects to sustain productivity even with limited on-site labor availability.
Competitive Benchmarking and Market Concentration
The Semi-Mobile Crushing Plant Market exhibits moderate concentration, with dominant players like Thyssenkrupp AG, Komatsu Ltd., and FLSmidth & Co. A/S holding significant market share. These leaders compete by focusing on technological modularity and after-sales support. Specialized firms like Keestrack NV and RUBBLE MASTER HMH GmbH successfully compete by targeting niche recycling applications, emphasizing rapid, high-yield plant configurations.
Executive Summary of the Semi-Mobile Crushing Plant Market
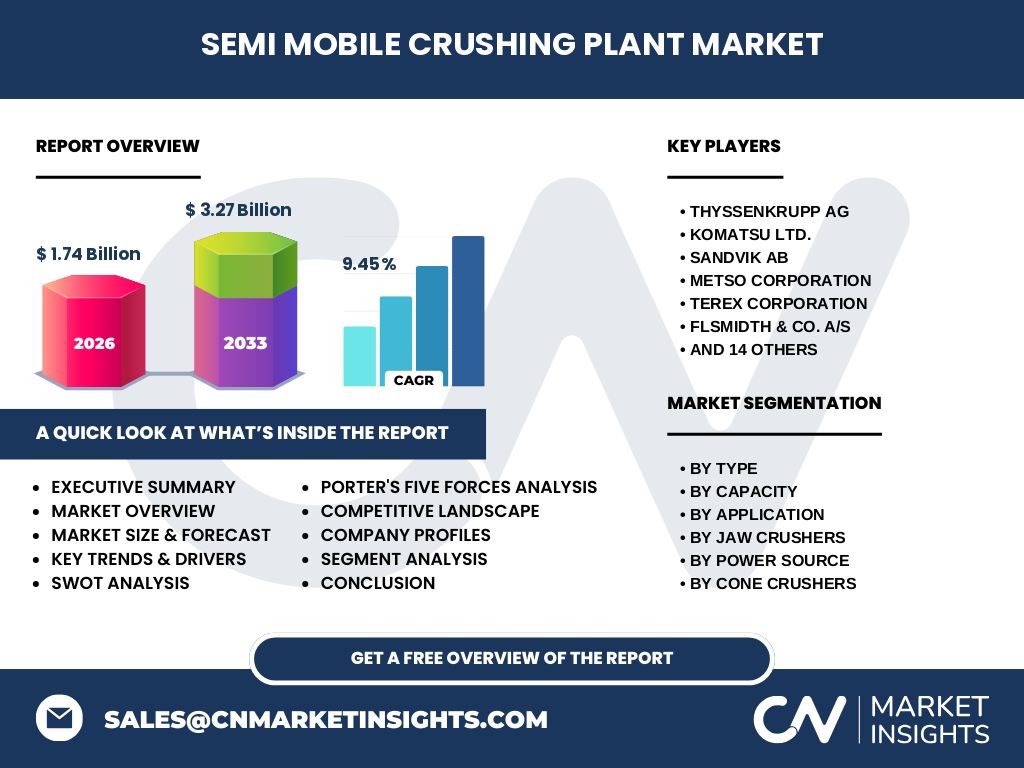
The Semi-Mobile Crushing Plant Market is currently valued at 1.74 Billion as of 2026. Our research highlights a robust growth phase, with the market projected to reach 3.27 Billion by 2033. This represents a compounded annual growth rate of 9.45%. Key findings suggest that mining and aggregate demand will remain the primary drivers of investment throughout the forecast period.
Projected Growth Trajectory 2027-2033
We project the market to expand from 1.74 Billion in 2026 to 3.27 Billion by 2033. This 9.45% CAGR reflects an aggressive increase in large-scale industrial adoption. Growth is expected to peak as emerging economies modernize their infrastructure portfolios, necessitating reliable, high-throughput systems capable of processing diverse raw materials like iron ore and granite.
Segmentation Analysis: Driving Operational Efficiency
Segmentation by capacity and crusher type allows for granular analysis. Jaw crushers remain the workhorse for primary reduction, while Cone and Impact crushers dominate secondary and tertiary stages. We categorize capacity into segments up to Above 400 Tons Per Hour, enabling operators to match specific hardware to the throughput requirements of their aggregate production or mining site.
Geographic Distribution of the Global Market
The Semi-Mobile Crushing Plant Market shows a concentrated performance across Asia-Pacific, North America, and Europe. Asia-Pacific leads due to rapid urbanization, while North America and Europe prioritize recycling and construction-led growth. Regional performance is intrinsically linked to local regulatory standards and the maturity of the regional quarrying sector, which dictate the specific equipment types in high demand.
In-depth Regional Review: Market Performance Drivers
In Asia-Pacific, strong demand for primary mining machinery drives volume, whereas European markets focus on environmentally compliant secondary and tertiary processing. North American trends demonstrate high interest in modular plants for road construction and demolition recycling. Each region reflects unique logistical hurdles, from dense urban construction requirements in Europe to the vast, remote terrain requirements typical of South American and Australian mining operations.
Strategic Positioning of Leading Companies
Companies like Terex Corporation and Astec Industries Inc. position themselves as full-lifecycle partners, focusing on product versatility and global distribution. Meanwhile, regional specialists such as Propel Industries and Hailstone Innovations optimize for local manufacturing cost-efficiency. This creates a competitive landscape where global innovation balances against localized serviceability, forcing firms to balance global branding with rapid regional maintenance support.
Porter’s Five Forces Analysis
The Semi-Mobile Crushing Plant Market experiences high competitive rivalry and moderate supplier power. Barriers to entry are significant due to the need for patented crushing technologies and deep engineering expertise. Buyer power is substantial for large mining conglomerates, yet threats from substitutes are low, as these specialized plants provide uniquely efficient mobility compared to traditional stationary, fixed installations.
SWOT Analysis of the Market Landscape
Strengths lie in technical maturity and scalability, while weaknesses stem from high capital intensity. Opportunities exist in the circular economy via high-demand recycling plants, whereas threats include volatile steel prices and raw material shortages. Successful firms leverage their strong R&D to mitigate weaknesses, turning technological agility into a sustainable competitive advantage in diverse global markets.
Value Chain Analysis: From Raw Materials to End-Users
The value chain for the Semi-Mobile Crushing Plant Market begins with specialized steel casting and component manufacturing (sensors, motors). It progresses through assembly plants, where modular structures are finalized. Distribution is handled through direct sales and dealer networks, culminating in the deployment at quarries, mines, and construction sites, where long-term service contracts provide the final value layer.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize digitalization and automation. High-potential areas include smart, AI-driven monitoring systems that predict maintenance, thereby minimizing downtime. Our analysis points to the recycling and demolition sector as a high-growth segment, particularly in urban centers where compact, low-emission semi-mobile plants have a unique advantage over heavier equipment. Focusing on sustainable hybrid power will ensure long-term relevance.
Conclusion and Key Takeaways
The Semi-Mobile Crushing Plant Market is poised for substantial growth, reaching 3.27 Billion by 2033. Our research confirms that flexibility and technological innovation are the ultimate performance drivers. Companies that integrate smart, hybrid systems while maintaining robust global supply chains will capture the largest market share. This industry remains vital to the global infrastructure development and mining lifecycle.
Research Methodology: Triangulating Market Estimates
Our baseline 1.74 Billion estimate for 2026 was derived by triangulating trade registry data, primary stakeholder interviews, and proprietary macroeconomic modeling. We cross-referenced regional demand with equipment delivery cycles and industrial output benchmarks. This multi-layered approach ensures our 9.45% CAGR forecast remains grounded in actual industry-reported shipment volumes and realistic capital expenditure trends observed across global mining and construction firms.
Scope and Parameters of the Report
This report focuses on semi-mobile plant configurations, excluding purely stationary plants. It provides a global lens on the mining, aggregate, and recycling sectors from 2027 to 2033. Limitations include the exclusion of secondary-market trade and localized small-scale informal mining operations. The study offers comprehensive segmentation by power source, capacity, and crusher technology to aid strategic decision-making for investors and stakeholders.
Recent Developments and Market Trends
Recent activity shows a surge in strategic acquisitions and product launches. Key innovators like McCloskey International Ltd and Lippmann-Milwaukee Inc. have unveiled highly mobile, high-capacity crushers designed for rapid setup. Partnerships between mining technology providers and AI software firms reflect a broader trend: integrating digital intelligence into the mechanical skeleton of the Semi-Mobile Crushing Plant Market to maximize output and reduce operational overheads.