What defines the scope and industry significance of the Wireline Services Market?
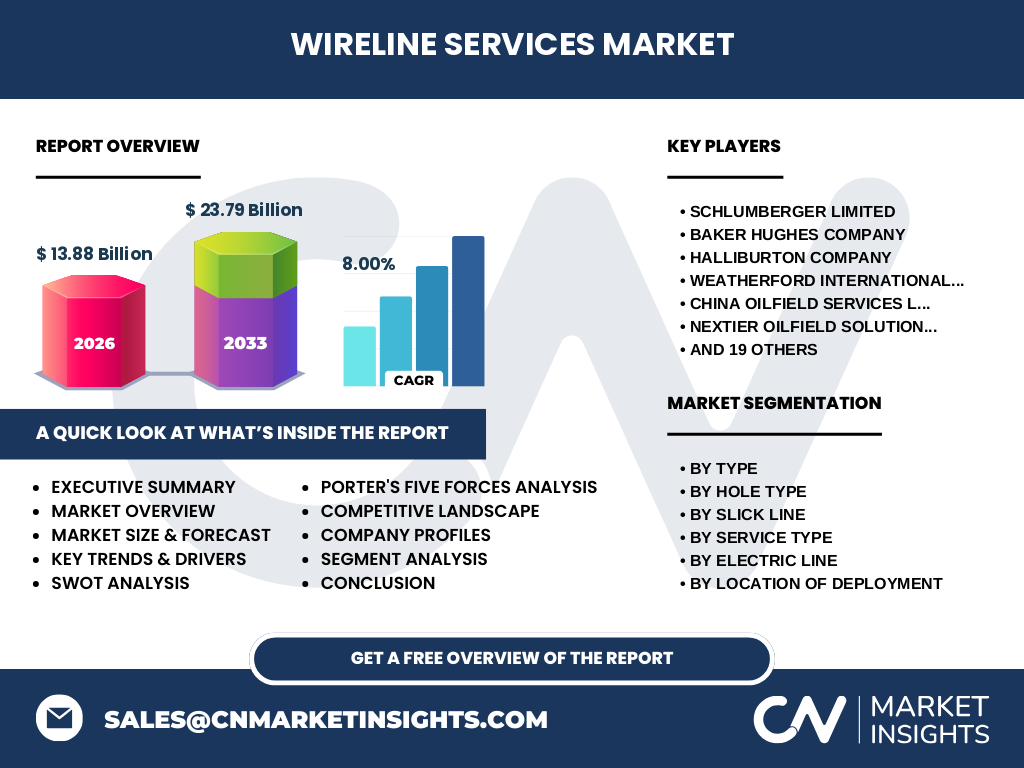
The Wireline Services Market encompasses critical subsurface diagnostic and intervention operations essential for oil and gas production. By deploying specialized cables—Electric Line or Slick Line—into boreholes, operators gain real-time reservoir data. As of 2026, the market is valued at 13.88 Billion, serving as the backbone for completion and logging activities that ensure long-term well integrity and production optimization across global energy assets.
Structural Growth Drivers and Market Constraints
Growth is propelled by rising offshore exploration and the increasing need for well intervention to rejuvenate aging fields. Conversely, the market faces logistical hurdles, such as strict environmental regulations by bodies like the EPA or BSEE. High capital intensity for Electric Line equipment remains a restraint, yet the necessity for accurate well logging services acts as a persistent catalyst for market expansion.
The Shift Toward Advanced Digital Logging and Automation
Industry leaders are pivoting toward digitized wireline telemetry to minimize human risk. Nextier Oilfield Solutions and Halliburton are integrating real-time fiber-optic sensors to enhance data granularity. This shift toward smart completion technology allows operators to maximize hydrocarbon recovery, effectively driving the market toward a projected 23.79 Billion by 2033 through improved operational efficiency and reduced intervention timeframes.
How did the COVID-19 pandemic redefine recovery trajectories?
The pandemic triggered a sharp contraction due to global lockdowns and plummeting crude prices, forcing companies like Weatherford International to restructure. Recovery has been driven by a strategic focus on cost-efficiency. Post-2022, the surge in global energy demand provided the necessary capital injection for firms to resume deferred well maintenance and intervention projects, stabilizing the Wireline Services Market trajectory toward steady growth.
Competitive Benchmarking and Market Concentration
The landscape is dominated by tier-one providers including Schlumberger Limited, Baker Hughes, and Halliburton, who command significant market share through extensive R&D. Mid-tier players like China Oilfield Services Limited and Archer Ltd leverage regional specialization to maintain competitive tension. The market reflects high concentration, as proprietary technology in Electric Line services serves as a high barrier to entry for smaller service providers.
Executive Summary: Insights for Stakeholders
Our analysis confirms the Wireline Services Market is entering a robust growth phase, projected to reach 23.79 Billion by 2033 at a CAGR of 8.00%. The core opportunity lies in offshore and cased hole diagnostics. To succeed, stakeholders must prioritize investments in automated intervention tools and align with the operational footprints of established giants like Nabors Industries to navigate complex regulatory and logistical environments effectively.
Market Forecast 2027 to 2033
We forecast a consistent expansion, with market value climbing from the current base toward 23.79 Billion by 2033. This 8.00% CAGR is fueled by increased drilling intensity and the global demand for well completion. While market volatility remains a factor, the predictable need for reservoir monitoring ensures a stable revenue stream for service providers managing complex open hole and cased hole environments.
Segmentation Analysis: Categorization and Roles
Market segments are defined by operational technicality. Electric Line services dominate the high-value data acquisition segment, while Slick Line remains the workhorse for well maintenance. Categorization by hole type, specifically Open Hole versus Cased Hole, highlights the dichotomy between exploration-phase diagnostics and production-phase monitoring. Each segment serves as a specialized node in the value chain, ensuring operational continuity across onshore and offshore environments.
Regional Market Performance Distribution
North America leads due to intense shale activity, while the Middle East and Asia-Pacific are emerging as critical hubs for offshore deployment. Our research shows regional performance is tightly correlated with local raw material access and regulatory stability. China Oilfield Services Limited’s dominance in Asian waters exemplifies how regional localized expertise creates a distinct competitive advantage over generalist global firms.
In-depth Regional Review: Key Geographic Markets
North America remains the largest market, supported by Nextier Oilfield Solutions and Select Energy Services in the Permian Basin. Meanwhile, the North Sea and Gulf of Mexico exhibit higher offshore complexity, necessitating advanced Electric Line intervention. These regions require rigorous compliance with Ospar or BSEE standards, creating a high barrier for regional entrants who cannot match the technical compliance capabilities of incumbents.
Strategic Positioning of Leading Players
Leading firms occupy distinct strategic niches. Schlumberger Limited focuses on high-end, data-driven Logging, whereas Superior Energy Services and KLX Energy Services excel in intervention and completion logistics. Smaller, agile firms like GO Wireline LLC and Yellowjacket Oilfield Services maintain profitability by targeting specific basins, effectively filling the gaps left by larger corporations that favor global-scale, long-term exploration contracts.
Porter's Five Forces Analysis
The Wireline Services Market experiences high bargaining power of buyers due to major operator consolidation. The threat of new entrants is low, guarded by proprietary logging patents and capital intensity. Rivalry among established firms like Weatherford and Halliburton remains intense. Supplier power is moderate, focused on the quality of specialized wireline cables and downhole instrumentation, which are essential for maintaining competitive operational service levels.
SWOT Analysis: Strategic Outlook
Strengths: Established technological dominance and deep-rooted service infrastructure. Weaknesses: High susceptibility to fluctuating commodity prices. Opportunities: Expansion in digital well completion and remote operations. Threats: Increasing regulatory scrutiny and the rapid shift toward alternative energy sources. Success requires balancing legacy service offerings with innovative digital solutions to mitigate these structural market threats while capitalizing on growing regional oilfield demand.
Value Chain Analysis: From Materials to End-Users
The value chain originates with raw materials like high-tensile steel and specialized alloys for wirelines. This flows through R&D-heavy manufacturers and service providers who deliver Logging, Completion, and Intervention services to end-users (oil companies). The value flow is critical; firms like Archer Ltd provide the vital link, converting raw diagnostic data into actionable reservoir management strategies for asset owners.
Investment Insights and High-Potential Areas
Investors should monitor cased hole intervention, which presents a compelling growth opportunity as legacy wells require consistent maintenance. We advise focusing on companies like Nine Energy Service Inc. or ProPetro Holding Corp that possess strong operational footprints in active basins. The transition toward automated wireline rigs offers the highest margin potential, as operators seek to reduce non-productive time in challenging offshore or high-pressure environments.
Conclusion and Key Takeaways
The Wireline Services Market is poised for significant growth, reaching 23.79 Billion by 2033. The convergence of digital integration and well maintenance needs will define the future of the industry. Stakeholders must emphasize operational efficiency, regulatory compliance, and technological differentiation. By focusing on Electric Line data accuracy and Slick Line reliability, companies can secure a resilient position in this vital sector of the global energy landscape.
Research Methodology: How we triangulated data
Our estimates are derived from a robust triangulation process. We synthesize trade registry data, primary interviews with technical directors, and secondary macroeconomic indicators like regional rig counts. By normalizing revenue reports from key players like Nabors Industries and Basic Energy Services against regional capital expenditure (CAPEX) budgets, we ensure our 8.00% CAGR estimate reflects the true volatility and potential of the current market.
Scope of the Report: Parameters and Limitations
This report covers global Electric Line and Slick Line services across Onshore and Offshore sectors. The scope includes Intervention, Logging, and Completion segments. Limitations include sensitivity to geopolitical shifts in the Middle East and Russia, which could affect regional supply chains. The report assumes consistent energy demand trajectories and does not account for catastrophic black-swan events that could force industry-wide shutdowns.
Recent Developments and Industry Announcements
Recent activity highlights a focus on strategic partnerships. For instance, Allied-Horizontal Wireline Services LLC recently optimized their fleet to target shale formations, while Expro International Group Ltd. announced new modular well logging technology to improve depth precision. These advancements signal that companies are actively pursuing technological leadership to differentiate their service offerings in an increasingly competitive, performance-driven market environment.