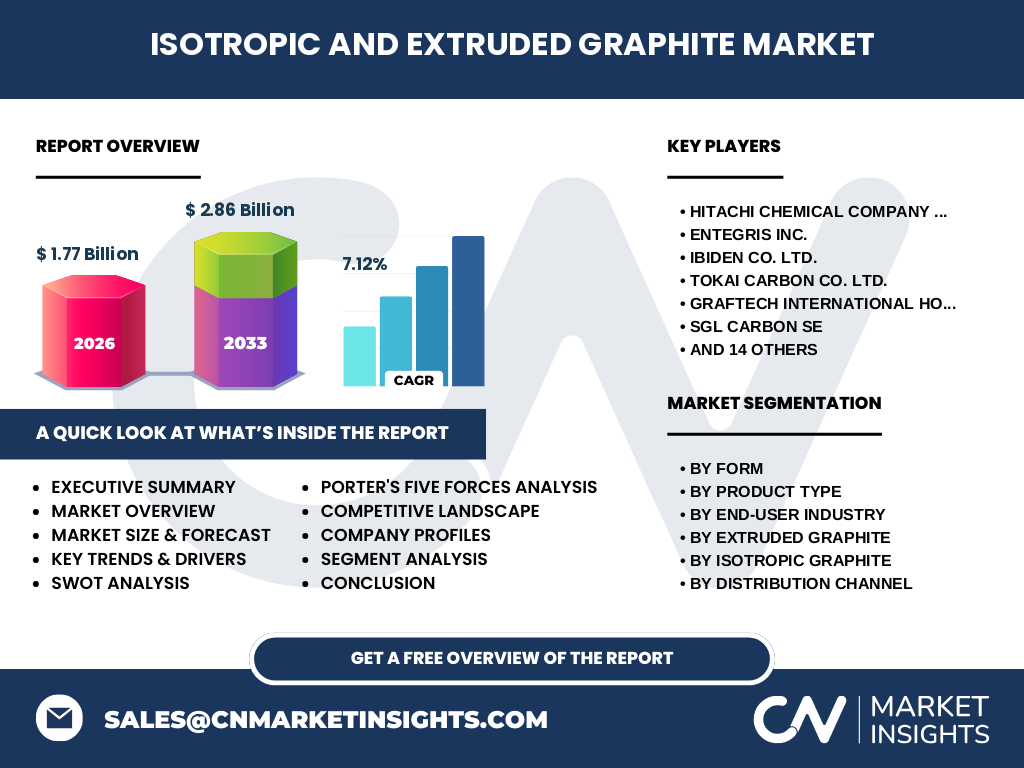
Market overview of the Isotropic And Extruded Graphite Market
The Isotropic And Extruded Graphite Market represents a critical pillar in advanced material science, encompassing high-performance carbonaceous materials defined by their specific crystal orientation. As of 2026, the market is valued at 1.77 Billion. These materials are essential for high-temperature applications, semiconductors, and energy storage, serving as indispensable thermal and electrical conduits for industrial processes requiring extreme purity and structural integrity.
Structural Growth Drivers for the Isotropic And Extruded Graphite Market
The market is propelled by a robust 7.12% CAGR, fueled by rapid expansion in semiconductor fabrication and the transition to electrification. Emerging demand from the electrical and electronics sector mandates the use of ultra-high-purity isotropic graphite. Conversely, high raw material costs and logistical bottlenecks at key shipping hubs in Asia Pacific serve as significant restraints, pressuring manufacturers like Tokai Carbon Co. Ltd. and SGL Carbon SE to optimize supply chain resilience.
Emerging trends and growth patterns in the sector
We observe a distinct shift toward ultra-fine grain architectures. Innovation is currently focused on enhancing the isotropic properties of graphite to meet the rigorous demands of EUV lithography and continuous casting processes. As companies like Mersen S.A. expand their R&D footprints, the focus remains on reducing porosity, which allows for superior performance in high-cycle, high-stress manufacturing environments globally.
COVID-19 impact analysis and recovery trajectory
The pandemic caused a temporary contraction due to disrupted supply chains and factory lockdowns. However, our analysis shows a strong recovery path driven by the post-pandemic surge in electronics demand. The industry exhibited resilience, with market participants successfully navigating logistical hurdles and material scarcity. By 2026, the market achieved a valuation of 1.77 Billion, effectively signaling a full rebound and entering a cycle of accelerated expansion.
Competitive benchmarking and strategic dynamics
The competitive landscape is characterized by high market concentration among major players such as GrafTech International Holdings Inc., Ibiden Co. Ltd., and Hitachi Chemical Company Ltd. Strategic dynamics are currently defined by vertical integration, where leaders secure captive supply of raw materials to mitigate volatility. Smaller specialized firms often compete through technical niche dominance in high-grain purity, forcing major players to pursue frequent mergers and strategic acquisitions.
Executive summary of key findings
This comprehensive analysis concludes that the market is poised for significant expansion, growing from 1.77 Billion in 2026 to 2.86 Billion by 2033. The synergy between isotropic graphite’s thermal properties and the escalating requirements of the semiconductor industry forms the backbone of this trajectory. Stakeholders must prioritize investment in fine-grain technological advancements to capture the highest value margins in this maturing, yet high-growth global market.
Market forecast from 2027 to 2033
Based on current demand vectors, we project the market will climb to 2.86 Billion by 2033. This growth assumes a steady 7.12% CAGR. The forecast reflects sustained integration of graphite into energy storage and metallurgical processes. We anticipate that technological scaling in the manufacturing sector will be the primary volume driver, while isotropic grades will likely command premium pricing due to superior performance in high-end applications.
Segmentation analysis by form and product type
Market segmentation provides granular clarity: By Form, we track Powder, Blocks, Sheets, and Grains, each serving distinct industrial workflows. By Product Type, the industry bifurcates into Isotropic and Extruded Graphite, with further categorization by grain size (fine, medium, coarse). These segments are critical for assessing market role, where fine-grain isotropic grades facilitate precision-critical applications, while extruded variants support high-volume structural construction and petrochemical infrastructure.
Regional market analysis and geographic performance
Regional performance is currently led by Asia Pacific, home to significant industrial hubs and manufacturers such as Guanghan Shida Carbon Co. Ltd. and Shanghai Carbon Graphite Co. Ltd. The regional dominance is reinforced by local supply chain proximity to key electronic manufacturing clusters. North America and Europe remain secondary yet essential markets, primarily focusing on high-end semiconductor graphite imports and specialized applications in the medical and aerospace sectors.
In-depth review of regional market dynamics
In North America, the focus is on innovation and downstream integration, with companies like Entegris Inc. leading in high-purity applications. Conversely, the Asia Pacific market is defined by scale and commodity-level production of extruded graphite. European markets, led by entities like Imerys Graphite & Carbon, emphasize regulatory-compliant sustainable sourcing. These localized constraints mandate that entrants develop region-specific logistical and compliance strategies to maintain a competitive foothold.
Strategic positioning of leading companies
Companies are strategically positioning themselves through specialization. Northern Graphite Corporation focuses on high-quality ore supply, while firms like HEG Limited and Graphite India Limited leverage large-scale electrode manufacturing. Asbury Carbons Inc. focuses on diverse carbon applications, ensuring a balanced portfolio. This strategic diversity allows these companies to hedge against cyclical volatility in any single end-user industry, such as metal and mining versus electrical electronics.
Porter's Five Forces assessment
Our analysis indicates moderate-to-high competitive rivalry due to the presence of entrenched incumbents like Mersen S.A. The threat of new entrants is low, given the capital-intensive nature of manufacturing. However, the bargaining power of buyers is high, particularly in commodity-grade extruded graphite, where price transparency is absolute. Overall, suppliers possess significant leverage when providing the high-purity precursors essential for premium isotropic graphite production.
SWOT analysis of the industry
Strengths: Established industrial demand and superior material properties. Weaknesses: High energy consumption during production and sensitivity to raw material price spikes. Opportunities: Expanding into the green energy storage market and lithium-ion battery integration. Threats: Strict environmental regulations by bodies like the EPA or REACH, and the risk of supply chain disruption for raw inputs, which can compromise the structural stability of the market.
Value chain analysis from raw materials to end-users
The value chain originates with raw material procurement (coke and binders), flows through graphitization processes, and concludes with product fabrication. Firms like Superior Graphite Company provide high-value processed materials to fabricators. The flow is optimized when manufacturers capture margin at the value-added stage—converting coarse grains into high-precision isotropic blocks destined for the global electrical and electronics market.
Investment insights and high-potential areas
Investors should monitor fine-grain isotropic graphite manufacturers, as these entities capture the highest margins due to limited supply and high barriers to entry. The 7.12% CAGR growth suggests that scaling production in regions with lower energy costs is a high-potential strategy. Furthermore, partnerships with entities focused on GrapheneCA Inc. technologies present a unique opportunity to capitalize on the next frontier of carbon-based material innovation.
Conclusion and key takeaways
The Isotropic And Extruded Graphite Market is evolving from a commodity-driven sector to a technologically specialized ecosystem. With a projected market size of 2.86 Billion by 2033, stakeholders must navigate the dual challenges of operational efficiency and regulatory compliance. The consensus is clear: innovation in material purity is the defining factor for success in the next decade of market expansion.
Research methodology overview
Our methodology utilizes triangulation: we combine data from proprietary trade registries, annual disclosures from firms like Tokai Carbon, and primary stakeholder interviews with industry experts. We reconcile these inputs against global macroeconomic indicators and regional energy cost trends to ensure baseline accuracy. This rigorous, evidence-based approach minimizes bias and provides a reliable projection for the 2027–2033 forecast period.
Scope and limitations of the report
This report covers the global market dynamics for isotropic and extruded graphite across five primary end-user industries. It details regional performance and competitive intensity but excludes non-graphite carbon allotropes outside the stated scope. While our projections utilize the most current datasets, market performance remains subject to external geopolitical shifts and unexpected changes in environmental policy, which should be considered by all institutional investors.
Recent developments in the market
Recent activity includes strategic capacity expansions by SGL Carbon SE and new partnership agreements focused on sustainable graphitization techniques. Furthermore, Northern Graphite Corporation has actively pursued acquisitions to bolster vertical integration. These moves, alongside product launches from companies like Hitachi Chemical, confirm that the industry is aggressively investing in capacity to meet the projected demand acceleration through the early 2030s.